A card appearing in a cashier is separate from an operator’s legal status, and Mastercard acceptance needs card-specific confirmation.
In Australia, the legal question behind an online casino payment is not simply whether a cashier displays a card brand or whether a transaction appears to go through. The central issue is whether an operator is permitted to provide real-money online casino gambling to people located in the country. Under the Interactive Gambling Act 2001, operators must not offer those services to Australian residents. The rule covers casino-style games such as poker, blackjack, roulette and pokies.
That distinction matters because a payment method does not confer legal status. A site describing itself as an Australian online casino, or presenting a cashier that appears to accept Mastercard, is not thereby authorised to provide online casino games in Australia. The operator’s location, branding or choice of payment channel does not change the prohibition. A functioning payment step and a lawful service are separate questions.
The Act is directed at providers. It makes supplying prohibited interactive gambling services to people in Australia unlawful for operators, including offshore businesses that target Australian customers. It does not explicitly make an individual player’s use of an offshore casino a criminal offence. That difference should not be mistaken for government approval or consumer protection. The absence of a player offence does not make an operator’s service lawful, nor does it mean a customer has the protections that would apply to a locally regulated service.
Choosing a Mastercard-friendly casino in Australia means checking the available payment details as well as the operator information provided. Use these short verdicts as a reference when reviewing the options.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, number OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming, with Roby Games Ltd as the operator.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curacao licence. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as licensed in Curacao and operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, number OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams lists a A$20 minimum deposit via POLi and holds a Curacao licence.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, number OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence; no other operator details were provided.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence, with TechSolutions Group N.V. named as the operator.
The Australian Communications and Media Authority, generally referred to as ACMA, administers enforcement of the Act. Its role is to act against prohibited services and the operators supplying them, rather than to certify a Mastercard casino or endorse a payment option. Enforcement can include measures intended to restrict access to illegal gambling services. As a result, a site that can be reached at one point may not remain accessible in the same way. Availability on a screen is not evidence of permission.
The Act also carries substantial penalties for breaches. Individuals who violate it may face a maximum daily penalty of $360,000, while the maximum for a body corporate is $1.8 million per day. These figures describe the legal exposure for those responsible for prohibited conduct; they are not a statement that players face those penalties for using an offshore site. The distinction between operator liability and player liability is essential when reading claims about Australian gambling law.
From inside the payments side of the industry, I learned that a successful transaction can create a misleading sense of legitimacy. Payment infrastructure answers a practical question about whether a transaction can be attempted or processed. It does not decide whether the service receiving the funds is legally permitted to offer online casino gambling to Australians. The same applies to phrases such as “Australian-friendly”: that is a marketing description, not a category established by the Act.
There is also a consumer-protection consequence. Australian consumer law does not protect players who use offshore casinos. If a dispute concerns an account, a balance, a withdrawal or the handling of personal information, an Australian customer may not have the ordinary local avenues of redress against an offshore operator. A polished website, familiar currency display or recognisable card logo cannot fill that gap. The legal position can be less visible than the payment interface. That is the practical risk.
This is why an online casino’s payment page should not be treated as a legal check. It may show available methods, but those options do not establish that an operator holds Australian authorisation. Nor does a card payment make the underlying gambling service lawful. For the Australian market, the statutory framework prohibits operators from offering real-money casino games to people in the country; the question of which card is shown in a cashier sits downstream from that rule.
Searches for Australian casinos that accept Mastercard often combine two different concerns: whether a payment route is presented, and whether a casino is legally allowed to serve Australians. Those concerns should remain separate. A site may make claims about local access or describe itself as suitable for Australian players, but such wording does not override the Interactive Gambling Act 2001. ACMA’s enforcement role is tied to the law, not to the labels an operator chooses for its website.
The result is a market in which payment availability can be mistaken for legal approval, even though the two have no such relationship. Australian law places the relevant prohibition on operators offering online casino gambling to people in the country. Players are not explicitly criminalised by that prohibition, but they are not protected by Australian consumer law when using offshore casinos. The cashier can show what a site will accept. It cannot settle what the law permits.
A card option appearing in a casino cashier is not the same thing as approval from the card issuer. The cashier is the operator’s interface for submitting a payment request. The issuer makes a separate decision about whether the transaction can proceed. Treating those as one check is a common source of confusion.
I separate the stages. A site may display a card brand, accept account details in its cashier, and let a payment request be submitted. Those actions show what the site’s interface permits at that moment. They do not prove that the issuer will authorise the charge, that the payment will complete, or that the card account is permitted to fund that kind of service. A submitted request is not a settled payment. A screen that reports a problem is not, by itself, a clear explanation of which party declined it.
That distinction matters when someone is looking for a casino deposit by Mastercard. The words “Mastercard accepted” can refer to the operator’s cashier configuration, not a promise that every Mastercard account can be used. The card brand is only one part of the decision. The card issuer, the account’s settings and the type of transaction can also matter. A cashier cannot override an issuer’s decision.
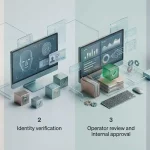
There is a separate identity check. Online casinos commonly require customers to undergo Know Your Customer checks before they carry out financial transactions. This is an assessment of the customer’s identity and account information, not a payment authorisation from the issuer. Completing it does not establish that a card transaction will be approved. Conversely, a payment screen being available does not show that the identity assessment is complete.
From the operator’s side, these checks answer different questions. The identity process concerns who holds the account and whether the operator has completed its required assessment. The cashier concerns the request being sent through the payment route available on the site. The issuer’s decision concerns the card account and the transaction presented to it. They can occur in the same broad payment journey, but they are not interchangeable approvals.
This is why a deposit process should not be read as a guarantee. Even if a cashier displays a card option and accepts a submission, that only establishes that the request reached a point in the process. It does not confirm the issuer’s final response or establish that the card may be used for gambling-related transactions. Nor does a decline necessarily mean that the card details were wrong; the interface may not expose the reason for a decision made elsewhere.
There is also a legal boundary that payment screens do not resolve. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people in Australia. The Australian Communications and Media Authority enforces the Act. The law does not make a player criminally liable merely for using an offshore casino, but Australian consumer law does not protect players who use offshore casinos. A working cashier does not change those conditions or make an offshore service lawful for its operator.
In practical terms, a cashier is a submission point, not a certificate of legality, identity approval, or issuer permission. I would not read a successful-looking screen as evidence that every check has passed. Payment interfaces are built to handle requests; they cannot speak for every institution involved.
The labels are not the decision. A card logo on a cashier is not proof that a Mastercard deposit will clear for a particular account, and completing an identity assessment answers a different question again. Each stage has its own scope. Confusing them turns a partial signal into a conclusion it cannot support.
For Australian residents, that distinction sits alongside the market’s legal position, rather than replacing it. A payment process can describe what a website’s interface appears to do, but it cannot confer legal status on the service or create consumer protections that do not apply. The mechanism and the permission are separate matters. A submitted request is still only a request.
Card acceptance is not a single property shared by every card bearing a familiar network logo. A comparison between Visa and Amex can describe how those two methods appear in casino payment information, but it cannot establish whether a particular operator takes Mastercard. The distinctions matter: network, issuer, operator and transaction type each sit at a different point in the payment chain.
A specialist review has reported that Visa may be accepted at more Australian online casinos than Amex. That is a comparison of Visa with Amex, not a measure of Mastercard coverage. It also describes a changing set of operator policies rather than a permanent rule. A site’s cashier and payment terms can be revised, and a statement about one card network should not be carried across to another by assumption.
In practice, acceptance claims often sound broader than the detail behind them. “Cards accepted” may mean one supported card type, or it may be a general label that leaves the network unspecified. A logo can indicate that a payment route exists somewhere in the service, but it does not by itself confirm that a particular card will be available to a particular customer. The label is not the transaction.
This is why a list described as the best Mastercard casino sites would need evidence tied to Mastercard itself. Evidence that Visa appears more broadly than Amex does not identify which sites take Mastercard deposits, whether the card is available to Australian customers, or whether the method remains available at the time of use. Ranking operators on that basis would turn a comparison of two other networks into a claim about a third.
The same restraint applies to “instant Mastercard withdrawal” descriptions. Deposit support and withdrawal support are different conditions, and a general card comparison cannot establish either the availability or speed of a Mastercard withdrawal. The word “instant” is especially easy to mistake for a network-wide promise. Processing depends on the service and the payment route; a Visa-versus-Amex observation gives no Mastercard timing.
Nor does card acceptance tell much about games. A casino’s catalogue and its cashier are separate parts of the service. A site may describe payment options without that description establishing which games can be accessed through a given card, or whether a card-funded account is treated differently. The payment logo is not a guide to the game catalogue.
The useful way to read comparative claims is to keep their scope intact. If a specialist review says Visa may be accepted more widely than Amex, the careful interpretation is precisely that: it is a reported comparison between Visa and Amex. It is not evidence that Mastercard is accepted at the same sites as Visa, more widely than Amex, or at any particular operator. Those are distinct claims requiring their own card-specific confirmation.
There is also a difference between a broad market comparison and a live cashier option. The former can signal how two methods are discussed across operators; the latter reflects what an individual service currently presents for a given account and transaction. Neither should be inflated into a universal rule. Payment pages can use familiar network names loosely, while the actual selection and terms determine what the operator is offering.
For anyone assessing a Mastercard claim, the decisive detail is whether Mastercard is expressly named in the operator’s current cashier or payment terms for the relevant use. Visa coverage cannot fill that gap. Nor can an Amex listing. Each network must stand on its own evidence.
That is a narrower conclusion than a ranked list, but a more accurate one. A comparison can be useful without answering every card question. Visa may be described as more broadly accepted than Amex in a specialist review; Mastercard coverage remains a separate matter, not a conclusion that follows from either side of that comparison.
A deposit appearing in a cashier and a withdrawal reaching an account are different stages, so their timing should not be treated as interchangeable. The available timing detail concerns Amex: casino deposits made with it are described as processing instantly, while a specialist review reports that an Amex withdrawal can take up to five days to clear. That withdrawal estimate is a source-specific statement, not a universal service standard.
The distinction matters because a quick deposit only describes the incoming transaction. It says nothing about how long a later payout takes, and it cannot be used to infer Mastercard withdrawal speed. A cashier may show that a payment has been submitted or recorded; clearing a withdrawal involves a separate process. “Instant” is a narrow claim. It is not a promise about the full account cycle.
The reported Amex withdrawal period is best read as an upper-end estimate from that specialist review, rather than as a guaranteed deadline for every casino or every cardholder. The wording does not establish when a particular request enters processing, whether the stated period begins at submission or approval, or when funds become available through an issuer. Those details should not be filled in by assumption.
That leaves a practical limit on what the comparison can say. The Amex detail gives a reference point for one card type: deposits are reported as immediate, while withdrawals may take longer to clear. It does not establish that Mastercard deposits or payouts follow the same pattern. Card networks, payment routes and operator procedures are not interchangeable simply because both methods involve a card.
Nor does the Amex timing tell us that a Mastercard payout is “instant”. Search phrases such as instant Mastercard withdrawals combine several different expectations: a rapid casino-side decision, quick transmission of funds and prompt availability at the receiving end. A timing claim needs to identify which stage it describes. Without that distinction, a short label can sound more definitive than the underlying process.
In my experience, the word “instant” tends to describe the most visible part of a transaction, not every step around it. Deposits are visible in the cashier; withdrawals have a clearance stage that is less immediate to observe. That is why an Amex deposit report and an Amex withdrawal estimate belong in separate columns, not in one general claim about card speed.
For Mastercard, the Amex figures provide no processing estimate. They cannot substantiate a promise of instant withdrawals, nor a particular clearance period. The meaningful comparison is limited to the documented Amex contrast: instant deposit processing and a withdrawal that a specialist review says may take as long as five days to clear.
Timing information also does not change the legal position. Australian consumer law does not protect players who use offshore casinos, so a reported payout window should not be mistaken for a protected service commitment. A timing estimate is just that. Not a guarantee.
A claim that a casino accepts cards is incomplete unless it identifies the card network and the type of card covered. Mastercard credit, Mastercard debit and other payment methods are not interchangeable labels. Evidence about one cannot establish acceptance of another.
A specialist review reports that deposits with American Express are available at some Australian-facing online casinos. That is a limited statement about Amex, not a finding that those same sites accept Mastercard. It also does not establish that Mastercard debit is accepted, or that a general “card payments” description applies to every card issued under a particular network.
I have seen broad payment labels do more work in advertising than they can support. “Card accepted” sounds definite; what it may actually leave unresolved is which network, card type and operator are covered. The distinction matters because acceptance is a property of a particular payment arrangement, not a feature that transfers automatically between brands.
The same discipline applies to claims about a casino that “takes Mastercard” or offers Mastercard pay. Unless the claim names the network and is tied to the specific operator, it cannot establish that Mastercard is available there. Nor can an Amex reference be repurposed as proof of Mastercard coverage. A comparison between the two would need evidence about both; a statement about only one leaves the other unanswered.
That is why a list of sites associated with Amex would not answer which sites accept Mastercard. It would answer a different question. Naming operators from an Amex claim in response to a Mastercard question risks giving a false impression of card-specific confirmation, even if the original Amex statement is accurately described. No ranking fixes that gap.
There is a separate legal context that should not be blurred by payment language. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. A payment-method statement is not an endorsement, a sign of lawful local provision, or evidence of consumer protection.
From an editorial standpoint, the careful wording is narrow: a specialist review reports Amex deposits at some Australian-facing online casinos; that does not verify Mastercard acceptance at any particular site. “Available” is not a synonym for “available on every card.” Small distinction. Material consequence.
A payment method and a catalogue of games answer different questions. A cashier may show a card brand as a deposit option, but that does not establish what games a site provides, whether any particular game is accessible, or whether the service may lawfully be offered to people in Australia. The card is one part of a payment process, not permission to use a real-money casino service.
That distinction matters when a site or review groups payment options and game access together. A statement that a casino accepts Mastercard, even if accurate for a particular transaction, would not prove that every part of its site is available to Australian residents. Nor would a game listing establish that Mastercard can fund an account. Those are separate claims, and each needs its own evidence.
I have seen payment labels treated as shorthand for a complete user experience. That is convenient for a sales page, but it hides the boundary between a cashier function and the service itself. A card logo says little about the status of the operator, the terms governing a deposit, or the legality of the underlying activity in Australia. It certainly cannot turn prohibited real-money online casino games into permitted services.
The same caution applies to Amex. A specialist review has reported that some online casinos do not accept it. That observation should not be stretched into a rule for every operator or treated as a permanent feature: cashier options can differ between sites and change over time. More importantly, an Amex statement does not establish anything about Mastercard-funded access or about which games a site offers.
Australian law draws a separate line around the service. Under the Interactive Gambling Act 2001, operators must not provide real-money online casino games to people physically located in Australia. Australian consumer law also does not protect players who use offshore casinos. Payment information does not alter either point.
So phrases such as “games with Mastercard” can blur two unrelated matters. The relevant questions are whether a payment method is offered for a particular transaction and whether a service can lawfully be provided in Australia. An answer to the first does not settle the second. No shortcut there.
In Australia, contactless credit and debit cards are accepted almost everywhere. That makes tapping a card a familiar part of ordinary retail payments, but everyday acceptance does not establish that a card can be used for every type of transaction. Payment habits and payment rules are separate things.
Mobile wallets, including Google Pay and Apple Pay, are also accepted almost everywhere in the country. They change how a payment credential is presented: the card may be stored on a phone rather than taken from a wallet. The underlying payment still depends on the service and transaction being supported. A familiar tap at a shop is not evidence about a separate online service.
Australian consumers are comfortable moving among physical cards, mobile wallets and services linked to bank accounts, such as PayPal. In practice, people tend to choose among these according to what a merchant offers and what fits the transaction. That flexibility is part of the wider payment environment, not proof that every provider accepts every method.
This distinction matters when Mastercard comes up in connection with an Australian casino. General card use across the country cannot establish that an online gambling service accepts Mastercard, nor should ordinary retail payment experience be treated as permission to use a credit card for online gambling. A method’s presence in a cashier, where one is displayed, is not a reliable substitute for understanding the law or the issuer’s position.
I separate the payment rail from the setting in which it is used. “Widely accepted” describes a broad consumer pattern; it does not mean universally available, lawful for every purpose or guaranteed to work in a particular transaction. The label does less than it seems.
There is also a consumer-protection distinction. Australian consumer law does not protect players who use offshore casinos. Familiar payment tools do not change that position, and their everyday convenience should not be mistaken for an endorsement of offshore gambling.
A card used to fund an account is not automatically an available route for receiving winnings. That distinction matters when reading claims about an online casino with Mastercard withdrawal: the deposit option and the withdrawal option are separate conditions, and one does not prove the other.
The available American Express information illustrates the point. A specialist review reports that not all Australian online casinos allow withdrawals to Amex. It also says that an Amex withdrawal may depend on having made a deposit with that card first. These are card-specific observations, not evidence about Mastercard. A cashier showing a Mastercard deposit option would not, by itself, establish that winnings can be returned to Mastercard.
Limits are separate again. A specialist review reports that individual casinos set their own Amex deposit and withdrawal limits, so the figures can differ between operators. A limit attached to deposits should not be read as a withdrawal limit, and a limit for Amex cannot be carried across to Mastercard. The terms may distinguish the two directions of payment.
I have seen payment labels treated as if they answered every practical question. They do not. Eligibility, the permitted route for a payout and the relevant limit are distinct terms. A broad claim about a “card withdrawal” can obscure those distinctions; the card network and the direction of payment both matter.
For Australian residents, there is also a wider qualification: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and Australian consumer law does not protect players using offshore casinos. Describing a payment condition is not an endorsement or an assurance of access.
The narrow conclusion is straightforward: Amex withdrawal availability and limits are not uniform in the specialist review’s account, and neither point establishes Mastercard withdrawal eligibility or limits. Separate terms. Different card.
A card deposit is submitted through a sequence of choices and entries in the cashier. In the described Amex flow, the player selects American Express, enters the card details, specifies the deposit amount in Australian dollars, then submits the payment. The sequence is straightforward; the method selection is the part that determines which card brand the request is being made with.
That distinction matters when interpreting a cashier screen. Seeing a card option does not establish that another brand is available through the same process. An Amex entry sequence is not evidence that a casino accepts Mastercard, nor does it show that Mastercard can be used as a casino payment method. Acceptance must be established for the specific card brand; the mechanics of entering one card’s details cannot fill that gap.
The cashier is the operator’s interface for collecting payment information. Selecting a method and submitting details describes how a request is sent, not whether an issuer permits it or whether the payment will be approved. Card eligibility and transaction approval are separate questions.
There is also a wider Australian context. The Interactive Gambling Act 2001 prohibits operators from supplying real-money online casino games to people in Australia, and Australian consumer law does not protect players who use offshore casinos. Describing a payment sequence does not make an offshore service lawful or provide consumer safeguards.
No invitation to deposit follows from the mechanics. The useful distinction is narrow: the Amex example shows a method choice, card-detail entry, an AUD amount and submission. It does not establish that Mastercard is offered, that a transaction will be accepted, or that a deposit can be used to access casino games. Different card, different question.
A bonus promoted alongside a card logo can look like a card benefit. In practice, those are separate terms. A casino promotion may set its own eligibility rules, while the cashier displays the payment methods the operator supports. Seeing Mastercard beside a bonus does not, by itself, show that paying with the card qualifies for that offer.
I have seen the wording do quiet work here. “Exclusive” can describe the promotion’s audience, not a special rate or reward attached to a payment card. The distinction matters: a bonus label is not proof of card-specific eligibility, and a card being accepted would not establish that it unlocks a separate bonus.
That leaves little basis for treating a Mastercard casino bonus as a defined product category. No particular offer, qualifying deposit, wagering condition, expiry or reward can be stated without terms tied to an identifiable promotion. Those details are not interchangeable between operators, or even between offers from one operator.
The safe reading is narrower: bonus terms and payment acceptance are different questions. A promotion’s own conditions determine who qualifies and what applies; the card brand alone cannot answer them. If a promotion explicitly names Mastercard, that wording still needs to be read with its full terms rather than treated as a general promise to cardholders.
No special card benefit follows automatically. Terms decide.
Limits are set by each casino and can vary. Check the casino’s cashier for its current Amex deposit and withdrawal limits.
Check the cashier for an Amex deposit option. Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as supporting Amex deposits for Australian players.
Amex deposits are processed instantly.
Yes, at casinos that accept American Express, but gift cards can be used for deposits only.
Amex deposits are processed instantly. Withdrawals can take up to five days to clear.
Amex deposits typically have no fee, but a casino may charge a 1.5% surcharge on transfers, and Amex cards incur a 3% currency conversion fee. Withdrawal fees may also apply.
Look for Amex in the casino’s cashier; several listed options for Australian players include Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo. Even if the cashier offers Amex, the issuer or an Australian bank may block the gambling transaction.