Security claims, payment checks and responsible gambling controls do not establish that an offshore casino is authorised to serve Australians.
“Secure” is a word that can conceal two different questions. One is whether a website uses safeguards for accounts and transactions. The other is whether the service is allowed to offer online casino games to people in Australia. The first does not answer the second. A polished site, an offshore licence or a reassuring security claim does not make an online casino licensed in Australia.
The legal boundary comes first. The Interactive Gambling Act 2001 prohibits operators from providing online casino games to Australian residents. That includes casino-style games offered for real money. The law does not explicitly criminalise individual players for using offshore casino sites, but that is not the same as saying those services are authorised or protected under Australian law. The obligation described here falls on operators; it does not turn an offshore service into a lawful Australian casino.
I have seen how easily the distinction gets blurred in promotional language. “Licensed” can sound like a complete answer, when it may mean only that an operator holds permission from a regulator elsewhere. An offshore licence is not an Australian licence. It does not displace the Australian restriction, nor does it establish that Australian authorities can resolve a dispute with the operator.
Choosing a secure online casino means checking the licensing information available and understanding the payment details that matter to you. This list offers a concise reference to the stated facts for each operator.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd.
Uptown Pokies
Uptown Pokies is listed as Curacao-licensed and operating since 2017. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams lists a Curacao licence and a A$20 minimum deposit via POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed as Curacao-licensed; no other operator details were provided.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence held by TechSolutions Group N.V.
That is the first practical meaning of security in this market: knowing what the service is, and what its legal status is not. A site may present itself as reliable, but a user interface cannot create Australian authorisation. Nor does the fact that a site can be opened establish that it is permitted to offer its games to people here. Access and authorisation are separate matters.
The Australian Communications and Media Authority, or ACMA, is the primary regulator for online gambling in Australia. Its role is not simply to publish general advice. Where an operator breaches the Interactive Gambling Act 2001, ACMA can issue fines and block websites. It can also ask internet service providers to block access to sites that offer prohibited interactive gambling services to Australian customers, or unlicensed gambling services to adults in Australia.
Blocking is an enforcement measure, not proof that a site has been made safe or that a blocked service has resolved its obligations. ACMA can issue blocking orders as a last resort when it considers customer safety to be at risk. A domain becoming unavailable, or changing, does not alter the legal position of the underlying service.
This matters because the word “accessible” is sometimes treated as a form of reassurance. In practice, a website may be reachable at one point and blocked later. Neither circumstance is a reliable test of whether it is licensed in Australia. The regulatory position is the stronger signal; a site’s design and availability are not substitutes for it.
An offshore licence may describe the rules that apply in the jurisdiction where it was issued. It does not confer Australian status. If an unlicensed service withholds winnings or handles a complaint poorly, Australian laws may not assist in recovering the money or securing a remedy. Unlicensed gambling services lack Australian consumer protections. That is a material risk, not a small-print technicality.
A VPN does not change this position. Using one to reach a casino site may result in winnings being voided, an account being closed, and a deposit being lost. It can also make it harder to establish what happened if a dispute arises. A tool that changes the apparent location of a connection does not supply a licence or provide consumer protection.
I would therefore separate claims about technical security from the protections that come with a regulated local service. In this market, an offshore site’s encryption or account features cannot answer the legal question. The available legal boundary remains the same: operators cannot offer online casino games to Australian residents under the Interactive Gambling Act 2001, and an offshore licence does not make that offer licensed in Australia.
The phrase “most secure” can suggest that a comparative ranking will settle the matter. It cannot. A site can appear orderly and still sit outside the Australian licensing framework. The meaningful starting point is not how confidently the site describes itself, but whether it is authorised to provide the service here. For online casino games, that boundary is restrictive.
Security begins with the boundary.
A deposit and a withdrawal are not mirror-image transactions. Money can enter an account before an operator has completed its checks, while a request to take money out can trigger a closer review of who controls the account and the payment method. I regard that difference as central to any assessment of claims about a secure online casino: a smooth deposit says little about what will happen when funds are requested.
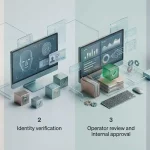
Online casino operators conduct know-your-customer checks, commonly called KYC, and require identity verification before withdrawals. The timing matters. A player may only discover that documents are required after a balance has built up and a withdrawal is submitted. That does not establish, by itself, that the request will be approved or how long the review will take. It does mean that depositing successfully should not be mistaken for having passed every account check.
Verification commonly involves three kinds of evidence:
The point is to compare the account details with the documents and payment information supplied. Where those details do not line up, the operator may seek clarification or further evidence before completing a withdrawal review. I have seen the distinction get lost in promotional language: “easy withdrawals” can describe the payment route, but it does not remove the identity check that sits before release.
Documents should be submitted only through the operator’s stated account-verification process, not sent casually in response to an unexpected message. The name, address and payment ownership details need to be consistent with the account information. A mismatch can turn a routine check into a back-and-forth exchange; that is a practical consequence of verification, not evidence that a payment is already on its way.
A legitimate-looking upload page is not enough to establish that a service is safe or authorised. Nor does the completion of KYC make an online casino lawful in Australia. The Interactive Gambling Act 2001 prohibits operators from offering real-money online casino games to people in Australia. An offshore licence is not an Australian licence, and identity checks do not change that position.
Australian law does not explicitly criminalise individual players for using offshore casino sites, but that is not the same as endorsement or protection. Unlicensed gambling services lack Australian consumer protections, and Australian laws may not assist if winnings are withheld. A service can collect identity documents and still leave a player with limited practical recourse in a dispute. The paperwork cuts both ways.
VPN access adds another risk: using a VPN to reach a casino may result in winnings being voided, the account being closed and the deposit being lost. It can also make the account’s location information inconsistent with the details provided during verification. A workaround is not a security feature.
When I look at withdrawal terms, I separate the verification condition from the payment promise. The first says what evidence may be demanded before funds can be released. The second may describe what happens after approval. Treating them as one event obscures the point at which a request can pause: the operator may be waiting for acceptable identity, address or payment-ownership evidence rather than processing a completed withdrawal.
That distinction matters particularly where a site presents itself as a safe place for real-money pokies or casino play. A polished account area and a completed deposit are not proof that a withdrawal will be uncomplicated, and verification is not a substitute for Australian authorisation. The checks explain what an operator may ask for; they do not confer legal status or guarantee access to funds.
Before any documents are provided, the service’s legal position and the consequences of sharing sensitive information need to be considered separately from the convenience of its cashier. For an offshore service, there is no Australian casino licence to rely on. KYC can establish identity for the operator’s purposes. It cannot create local consumer protection.
PayID can sound like a promise about the whole cash-out process. It is not. A transfer moving through a payment network and an operator approving and releasing a withdrawal are separate steps, controlled by different parties. A quick transfer cannot make an unresolved operator decision happen faster.
A specialist review describes PayID transfers as running over the New Payments Platform and says they can clear quickly, sometimes within minutes after release. That is a report of possible transfer timing, not a standard or guaranteed payout time. The distinction matters: the clock for the transfer starts only once funds have been released. It says nothing by itself about when an operator will approve a request or send it.
In payment operations, the network is only one part of the chain. A withdrawal request may still be awaiting action before any transfer is sent. Once released, the transfer may move quickly; before release, the payment network has no role in the delay. Treating those stages as one event is how “instant” claims become misleading. Fast movement, later start.
That is also why PayID does not establish that a payment arrangement is secure. A recognisable payment method can describe how funds move, but it does not verify the operator, settle a dispute, or establish that the service is authorised in Australia. Payment speed and lawful access are different questions. The Interactive Gambling Act 2001 bars operators from providing real-money online casino games to people in Australia, and an offshore licence is not an Australian licence.
The practical reading of a PayID claim is therefore narrow: it concerns the possible speed of a transfer after release, not a promise that a withdrawal will be approved or arrive immediately. A headline that joins “PayID” and “instant withdrawals” compresses separate decisions into one phrase. The omitted part is usually the point at which the operator still controls the process.
I have seen payment language do this work in other settings: it makes the visible step sound like the whole service. “Fast” can accurately describe a transfer in motion while leaving the waiting period before it begins untouched. Without a stated release, there is no basis for treating a network’s potential speed as a payout schedule.
There is a further limit in Australia. Online casino services offered to residents by offshore operators are not made lawful by accepting PayID, and an offshore payment route does not provide the protections of an Australian-authorised casino service. Unlicensed services lack consumer protections, and Australian laws may not assist if winnings are withheld. A VPN does not change that position; using one to access a casino may lead to winnings being voided, an account being closed, and deposits being lost.
For anyone assessing a PayID description, the useful question is not whether the payment method can move quickly. It is whether the claim clearly distinguishes transfer time from operator approval and release. If those stages are blurred together, “fast” describes only part of the journey.
When I assess a claim that a gambling website is “secure”, I separate two questions that promotional copy tends to fold together: whether a service is authorised to offer a particular product in Australia, and what protections exist if something goes wrong. A polished site or a foreign licence does not answer the first question.
ACMA directs people to its public register and related information about legal gambling products. The register is a practical starting point for checking whether a wagering service holds a valid Australian licence. The check needs to match the service and the product being offered; a listing connected to lawful wagering does not authorise online casino games.
That distinction matters because real-money online casino games cannot lawfully be offered to people in Australia. An offshore licence is not an Australian licence, and it does not turn a prohibited offering into an authorised one. So a search for the best-protected casino site cannot be resolved by comparing badges or licence claims. There is no Australian licence that makes an online casino lawful for local customers.
A register check has limits. It can help establish whether a wagering service has the relevant Australian authorisation; it cannot certify every security feature, guarantee that a business will pay, or make an unlicensed casino lawful. I have seen “licensed” used as though it were a universal quality mark. It is not. The issuing jurisdiction and the permitted product are what count.
Unlicensed services lack Australian consumer protections. If winnings are withheld, Australian laws may not assist in recovering them. That is not the same as saying an individual player is criminally liable for using an offshore site: the Interactive Gambling Act does not explicitly criminalise players for that use. The exposure lies in the limited recourse when the operator and customer are outside the Australian regulatory framework. Little leverage.
Access can also be disrupted. ACMA can seek website blocking for prohibited or unlicensed services, and it may issue a blocking order as a last resort when customer safety is considered at risk. A site loading today therefore says nothing reliable about its authorisation or continued availability. Nor does a working payment page establish that the service is lawful.
VPN use does not solve the licensing problem. It may breach the operator’s terms and can lead to winnings being voided, an account being closed, or deposits being lost. It can also make account access and any later dispute harder. A connection that appears to work is not proof of permission.
In practice, a credible check begins with the product, not the design: consult ACMA’s public register for Australian-authorised wagering services, and do not treat an offshore licence as local approval for online casino games. The check can clarify regulatory status. It cannot certify a casino as safe, create protections where none apply, or promise a payout. A neat badge proves little.
A welcome offer can make a casino page look reassuring: the language is polished, the terms are laid out, and the bonus is presented as a reason to sign up. In my experience, that presentation can pull attention towards the reward and away from the more basic question: what is the service offering, and is it lawful to offer it to people in Australia?
The Interactive Gambling Act 2001 prohibits domestic operators from providing online casino games to Australian residents. A bonus does not alter that position. It is a promotional condition attached to an offer, not a licence or an exception to the law. Calling pokies “secure”, adding a welcome package, or advertising a special for Australians cannot turn a prohibited service into an authorised one.
That distinction matters because promotional copy often borrows the language of safety. “Trusted” may describe how a brand wants to be perceived; “secure” may refer to technical features or account processes. Neither word, by itself, establishes that the operator is licensed in Australia or allowed to provide online casino games here. Marketing language is not regulatory status.
The mechanics of an offer can also occupy the whole page. The headline gives the bonus prominence, while eligibility rules and withdrawal conditions sit elsewhere in the terms. Those details may affect what an offer means in practice, but they do not answer the legal question. A generous-sounding promotion is still only a promotion.
I would separate the claims rather than read them as one promise. A site may make statements about account security, describe a bonus, and use Australian-facing wording. Each is a different claim; none proves the others. In particular, an offshore licence is not an Australian licence, and an Australian-themed promotion does not make an offshore service authorised here.
Accessing an offshore casino through a VPN does not change the service’s legal status. It may also lead to winnings being voided, an account being closed, or a deposit being lost under the operator’s terms. That is a material risk, not a technical workaround.
The same caution applies to phrases such as “safe casino with a bonus for Australians”. They package a safety claim and a sales incentive together, but neither resolves the underlying restriction. The bonus is the hook. The legal position remains unchanged.
A payment method can make a transfer straightforward without making the full withdrawal quick. I separate the operator’s approval stage from the time a payment network or bank takes to move released funds. They are different parts of the process, and a fast wallet transfer does not remove the wait before approval.
A specialist review describes PayID and some e-wallet withdrawals as potentially quick once approved, while bank transfers and card payments may take several business days. That is an account of reported payment mechanics, not a service standard or a promise. The operator still has to approve and release a withdrawal, and the payment processor then handles its part. The practical point is simple: the clock does not start at the same moment for every method.
E-wallets can be useful where a service accepts them for both deposits and withdrawals, but that should be checked in the payment terms rather than inferred from a deposit screen. A deposit option does not prove that the same route can be used to receive funds. Nor does the word “secure” in a wallet or casino description establish that a service is authorised to offer online casino games in Australia.
POLi is mainly described as a deposit method in specialist payment reviews. It should not be treated as a withdrawal route unless the service’s terms explicitly say that withdrawals are supported through it. That distinction matters: a payment method shown at the point of funding may not appear when funds are being returned.
Cards have their own uncertainty. Specialist payment reviews note that card withdrawals can be slower, or unavailable, depending on the processor. If a card route is not offered for withdrawals, the operator may specify another method; the available terms determine what can be used. A bank transfer is another possible route, but the timing described for bank transfers is measured in several business days, not as an immediate release.
I would read the withdrawal terms as a sequence, not as a single speed claim: which method accepts a payout, what approval must happen first, and what processing follows release. A fast transfer claim addresses only one link. It says nothing by itself about the whole interval.
There is also a more basic limit to any wallet comparison. Real-money online casino games are prohibited offerings in Australia, and an offshore service is not licensed in Australia. Unlicensed services lack Australian consumer protections, and Australian laws may not assist if winnings are withheld. Payment convenience cannot repair that gap.
Responsible gambling controls address a different risk from account security: they are intended to help contain gambling-related harm. I have seen “safe play” used as a reassuring label, but the useful question is what controls and support information are actually available—and whether the service can lawfully offer the product in Australia.
That legal distinction matters. The Interactive Gambling Act 2001 prohibits operators from offering real-money online casino games to people in Australia. An offshore licence does not make an online casino licensed in Australia. So controls described by an offshore casino should not be mistaken for protections supplied by an Australian-authorised online casino market.
Deposit limits are one example. A specialist affiliate review reports that some online casino services let players set daily, weekly or monthly deposit limits. That is a description of a reported feature, not a reliable statement about every service or a guarantee that a limit can be changed or enforced in a particular way. The setting may help restrict new deposits, but it does not by itself establish that a service is lawful or that other protections apply.
The wider framework also matters. Licensed operators are required to follow responsible gambling regulations under the Act. Reputable platforms provide information about gambling-related harm and direct people to professional support services across Australia. In practice, that information is more meaningful when it is easy to find and clearly separates support from promotional material. A responsible gambling link buried in account menus is not the same as a prominent route to help.
I look for plain explanations of what a control does, where it applies and how support can be reached. General claims such as “player protection” are not enough on their own. Nor does a deposit setting prevent every form of gambling-related harm. It is one tool, not a complete safety system.
For Australians, the central point is not that a particular offshore site has a limit feature. It is that responsible gambling measures cannot turn a prohibited online casino offering into an Australian-licensed service. Treat the presence of controls and support information as relevant to harm reduction, while keeping their limits—and the legal position—clear.
A polished mobile interface does not alter the legal position. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people in Australia. That covers online slots—often called pokies—as well as casino games such as blackjack. The restriction concerns the service offered, not whether it is opened on a phone, tablet or desktop.
I have seen mobile design do a lot of quiet persuasive work: a familiar game screen can make a service feel ordinary, while the legal status sits outside the frame. “Mobile-friendly” describes how a page behaves on a device. It says nothing about whether the game may lawfully be offered to Australians.
For game information, the RTP is a separate matter. A pokie’s help or information screen may show its return-to-player setting, often opened through an “i” symbol or a menu. That figure describes a theoretical game setting; it is not a promise about an individual session or a way to establish that a service is lawful.
There is another detail easy to miss. A provider may issue the same title in several RTP versions, and the operator selects which version to make available. So recognising the game name—or finding a published RTP for that title elsewhere—does not confirm the setting in the version being shown. The in-game information is the relevant place to check what that version displays.
Useful, but limited. A displayed RTP can tell something about the game configuration; it cannot turn a prohibited online casino offering into an authorised one. Nor does a small-screen layout provide evidence about the operator’s legal status. Those are different questions, even when the interface places them side by side.
The practical distinction is simple: game information describes a game, while the law governs the service offering it. A familiar design can blur that line. The screen cannot.
A casino described as Canadian may appear relevant to someone comparing online gambling services, but the country attached to a brand does not answer the Australian legal question. The rule that matters here concerns the service offered to people in Australia: the Interactive Gambling Act 2001 prohibits domestic operators from offering online casino games to Australian residents.
I have seen how labels do their work. “Canadian” can sound like a useful credential, but it identifies neither Australian authorisation nor the legal status of an offer made to someone in Australia. A company’s location, branding or intended audience does not change the Australian rule. The relevant point is where the customer is located and what kind of service is being offered.
That distinction is easy to lose when the same site is discussed across different countries. A description that may be meaningful in one jurisdiction cannot simply be carried across the border as proof that the service is permitted in another. Nor does a national label establish that an online casino is secure in any broader sense. Those are separate questions, and the Australian legal position cannot be inferred from the word “Canadian.”
The practical limit is clear: a Canadian connection does not turn an online casino offer to Australians into an authorised Australian service. The Interactive Gambling Act addresses operators providing online casino games to Australian residents, rather than granting an exception based on where a business is based or how it presents itself.
I would treat country labels as context, not as a legal conclusion. They may describe a business or its market language; they do not replace the Australian rule. That is the point worth keeping in view whenever a casino is presented as Canadian while the service is being considered from Australia.
The two questions must remain separate. For an Australian resident, the relevant boundary is the prohibition on domestic operators offering online casino games to Australian residents—not a foreign label that sounds reassuring.
Different jurisdiction. Different question.
A secure internet connection and a lawful gambling service are separate things. SSL encryption can protect transactions and sensitive information while they move between a site and its users. That is a useful technical safeguard. It does not establish who operates the site, how the business handles disputes, or whether it is authorised to offer online casino games in Australia.
I learned to treat “secure” as a narrow claim, not a verdict. Encryption addresses part of the connection; it does not turn an offshore licence into an Australian licence. Nor does a polished design or security wording change the legal position: the Interactive Gambling Act 2001 prohibits operators from providing online casino games to people in Australia.
That distinction is easy to miss because the visible signs are reassuring. A site may describe transactions as protected and still be an unlicensed service for Australian customers. The protection offered by encryption cannot substitute for consumer protections under Australian rules. Unlicensed gambling services lack those protections, and Australian laws may not assist if winnings are withheld.
A VPN does not fix the problem. Using one to reach a casino may lead to winnings being voided, an account being closed and deposits being lost. The technical ability to open a page is not evidence that access is lawful or that the operator will honour an account.
This is why a secure casino site should be assessed in layers. SSL has a limited, concrete role: safeguarding information and transactions. Legal authorisation and recourse if something goes wrong are different questions, and a padlock or encryption claim cannot answer them. The distinction matters most when promotional language uses “safe” as if it covered every risk.
I would not infer legitimacy from the appearance of a site or from the presence of encryption alone. A connection can be protected while the service remains outside Australia’s lawful market and outside the protections available through Australian regulation.
A technical safeguard. Not authorisation.
Australian players are not explicitly criminalised under the Interactive Gambling Act 2001 for using offshore casino sites. However, those services are not authorised in Australia and lack Australian consumer protections, making it harder to resolve disputes or recover withheld winnings.
Licensed operators provide deposit limits that players can set daily, weekly or monthly, and information about gambling-related harm with referrals to professional support services across Australia.
You may be asked for photo identification, proof of address and proof that the payment method belongs to you.
PayID, e-wallets, bank transfers and cards may be used, while POLi is mainly for deposits. PayID and some e-wallet withdrawals can be quick once approved; bank transfers and card withdrawals may take several business days, and card withdrawals may be unavailable.