Amex availability, deposit checks and withdrawal eligibility vary by casino, while offshore operators face a separate legal restriction in Australia.
The legal issue sits with the operator, not with the choice of card. Under Australia’s Interactive Gambling Act 2001, a business must not provide real-money online casino games to people in Australia. That prohibition covers casino-style services such as poker and table games as well as other forms of online casino gambling. An overseas address or licence does not make an offshore service lawful to offer to Australian residents.
The Act does not explicitly make an Australian player’s use of an offshore casino a criminal offence. That distinction matters, but it is not a sign that the service is approved or that playing carries the protections attached to a lawful local product. Australian consumer law does not protect players using offshore casinos. If a dispute arises over an account, a balance or a promised payment, the usual local consumer protections cannot be assumed to apply.
I have seen marketing blur these two points: “available to Australians” can sound like “permitted in Australia”. It means no such thing. The law places the prohibition on the operator, while the player’s position is different. No player penalty is specified by the Act for simply using an offshore casino, but that does not turn the operator’s service into a regulated Australian offering.
When choosing a casino site that accepts Amex in Australia, check the available payment details and operator information before deciding where to play. This list provides a concise reference to the facts available for each site.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is licensed by Curacao eGaming, with Roby Games Ltd named as the operator.
Uptown Pokies
Uptown Pokies operates under a Curacao licence and has been operating since 2017. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams has a Curacao licence and a A$20 minimum deposit via POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed as operating under a Curacao licence.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence, with TechSolutions Group N.V. named in the licensing information.
Enforcement rests with the Australian Communications and Media Authority, commonly called ACMA. It is the regulator charged with applying the Act and can take action against prohibited services. Offshore casino access is actively blocked and enforced against; it is not a market where a foreign licence substitutes for local authorisation. Access may therefore be interrupted, and the fact that a site can be reached at a particular moment does not establish that it is lawful to provide its games in Australia.
There is a further boundary around promotion. Advertising real-money interactive gambling services, including online casinos, to Australian audiences is prohibited. That restriction also matters when a page appears to be neutral information but directs people towards offshore play. A guide to casino sites that accept Amex in Australia can easily cross from describing a legal issue into promoting a service. The payment label does not change the underlying activity.
The practical conclusion is narrow. Australians are not explicitly criminalised by the Act merely for using an offshore casino, but the service itself is prohibited from offering real-money casino games to people here. Access may be blocked, local consumer law does not protect offshore players, and a foreign licence does not create Australian approval. Those are separate points, and combining them into a reassuring claim about “legal access” would misstate the position.
This is the line I would keep in view when reading any claim about casino access: an operator’s willingness to accept a customer is not evidence that Australian law permits the operator to serve that customer. Card acceptance, account access and a regulator’s position are different matters. The law is about the service being provided, not the brand name attached to a payment method.
In Australia, payment choice is part of ordinary routine rather than a decision made from scratch each time. Contactless credit and debit cards are accepted almost everywhere, so tapping a card has become a familiar way to pay in person. Mobile wallets, including Google Pay and Apple Pay, are accepted almost everywhere too. The physical card and the phone sit side by side as everyday options.
I have seen how that familiarity shapes expectations online. A person who moves between a card, a phone wallet and a bank-linked service is not necessarily committed to one payment brand. The choice depends on what is available at the point of payment and what feels straightforward in that moment. PayPal is one example of a service linked to a bank that Australians are comfortable using alongside cards and wallets.
That flexibility matters when people encounter an online cashier. Familiarity with contactless payments does not, by itself, tell anything about the methods an online service accepts. A wallet used at a shop and a card entered for an online transaction are different payment routes, even if both draw on the same underlying account. The interface may make them look equally simple; the processing arrangements are not identical.
Amex sits within this wider habit of switching. It is a card choice, not a guarantee that every online cashier will offer the same route as a physical terminal or mobile wallet. In my experience, the useful distinction is between being comfortable with a payment method and finding that method available for a particular transaction. Those are separate things.
The broader pattern is practical: Australians commonly move among cards, mobile wallets and bank-linked services without treating the switch as unusual. That does not make every option interchangeable. Each has its own place in a payment flow, and availability depends on the service being used. Familiarity is not acceptance.
Amex deposits are reported as available at some online casinos, but that does not establish acceptance across the Australian market. A specialist review has identified operators said to support the payment method, while another such review notes that some casinos do not accept it. These are time-sensitive descriptions of individual services, not a reliable rule for every operator or account.
That distinction matters because “Amex accepted” can sound like a market-wide feature when it is actually an operator-specific claim. One casino may include Amex among its payment options; another may not. The fact that a payment brand is familiar in Australia does not, by itself, show that a particular gambling service accepts it. Nor does a broad claim about Australian online casinos settle what is available at any one site.
I have found that payment labels can carry more weight in advertising than they deserve. “Available” describes a stated option, not a promise that it will remain available or that every customer can use it. A general review may summarise an operator’s advertised methods, but that is different from a current, account-specific confirmation. The wording is narrow. The implication often is not.
For that reason, claims about an Australian online casino accepting Amex need to be read as claims about a particular operator at a particular point in time. They should not be turned into a directory or recommendation. Naming operators as suitable choices would go beyond the limited availability information and could make a prohibited gambling service look like an endorsed option.
There is also a difference between a deposit option being mentioned and the full payment relationship being established. Acceptance for deposits does not, on its own, tell anything about withdrawals, fees, transaction limits, or whether other terms apply. Those are separate questions. The label answers only the narrow question of whether Amex is presented as a deposit method.
The same caution applies to wording such as “best” or “top”. Those descriptions suggest comparison, quality, and suitability, not simply that a payment method has been reported. A review’s mention of Amex does not establish that a site is better than another, or that the service is appropriate for Australian residents. Payment availability is not a quality measure.
Australian law sets a more fundamental boundary. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and the Australian Communications and Media Authority enforces the Act. The fact that a foreign service is described as accepting Amex does not change that position. Australian consumer law does not protect players who use offshore casinos.
In practical terms, the defensible answer is limited: specialist reviews have reported Amex deposit availability at some online casinos, and other reviews report that some do not accept it. Neither statement supports a universal claim. The market descriptions can change, and a payment-method mention should not be mistaken for a guarantee, recommendation, or indication of legal protection. No broader conclusion follows.
A cashier may display Amex as a payment option, but seeing it there does not by itself establish what the transaction will cost. The amount credited and the amount charged to the card can differ if a casino adds a surcharge or the payment involves currency conversion. Those details belong to the transaction terms, not to the card logo.
Descriptions of Amex deposits at casinos report a straightforward sequence: select Amex in the cashier, enter the card details and an amount in Australian dollars, then submit the payment. The deposit is described as being processed instantly. That refers to the payment being credited promptly; it should not be read as a guarantee that every transaction will be approved or that every cashier will handle it identically.
The mechanics are simple. The price is less so.
An amount entered in AUD gives the cashier a clear starting figure, but the currency in which the casino processes the payment still matters. If the transaction is converted into another currency, the card may incur a conversion fee. A specialist review reports a 3% currency-conversion fee on Amex transactions. That figure should be treated as a reported charge, not a universal fee applying to every casino or card account. The applicable rate and the point at which conversion occurs depend on the terms governing the particular transaction.
That distinction can be easy to miss. A cashier can show an Australian-dollar deposit while a payment is handled in a different currency behind the scenes. The displayed amount therefore does not, on its own, settle the final cost. The transaction currency and any conversion charge need to be visible in the payment terms before a payment is submitted.
A separate cost may come from the casino itself. A specialist review reports that a casino may apply a 1.5% surcharge to Amex transfers. This is a possible casino-side charge, not a fixed Amex fee. Other specialist review material describes Amex deposits as generally fee-free, while noting that casino charges can differ. These reports are not contradictory: one describes a fee-free deposit arrangement, while the other identifies a surcharge that may apply in a particular cashier. The cashier’s own terms determine which applies.
Amex Deposit Process
Selection
Select Amex as the payment option in the casino cashier.
Entry
Enter the card details and the desired deposit amount in Australian dollars.
Submission
Submit the payment to have the deposit processed instantly.
It is useful to keep the potential charges in separate buckets: a casino surcharge, a card currency-conversion fee, and any other fee specified in the relevant payment terms. Combining them into a single “Amex fee” obscures who sets the charge and when it may be added. A deposit can be credited instantly and still cost more than the amount entered.
The distinction also matters when comparing a displayed deposit with a card statement. If a surcharge is charged by the casino, it is associated with the casino’s payment terms. If currency conversion is involved, the card’s conversion terms may affect the final amount. The cashier should not be assumed to show every card-side cost in the same place as a casino surcharge. Check the figures and currency presented at checkout, and retain the transaction record.
A $10 deposit, where a cashier permits that amount, is still subject to the same questions: whether a surcharge applies, whether the transaction is converted, and what the card’s terms say. The figure entered is not evidence that the final card charge will be identical. No particular minimum deposit or fee can be inferred from the fact that a small amount is requested.
There is also a legal boundary to this description. Australian law prohibits operators from offering real-money online casino services to people in Australia, and consumer law does not protect Australians who use offshore casinos. The cashier mechanics described here are not an invitation to make such a payment or a claim that a displayed option makes it lawful. A working payment screen is not a safeguard.
The practical point is that “instant” describes processing speed, not certainty about the final cost or the legal status of the service. A reported no-fee deposit does not rule out a casino surcharge or currency conversion, while a surcharge reported by a specialist review should not be treated as a universal charge. The terms attached to the specific payment are decisive.
A failed Amex transaction does not necessarily mean the cashier has rejected the card. The decision can sit with the card issuer or with American Express itself, and those are different points in the payment chain.
Australian banks may block gambling-related transactions on Amex cards at issuer level. In that case, the payment can be stopped before the website receives approval. A cashier may show a decline, but that message alone does not identify which party made the decision. From the other side of the counter, I learned not to treat every failed attempt as a technical fault at the merchant.
There is also a separate possibility: a specialist review has reported that Amex may block payments to a particular website. That is a site-specific restriction, not proof that every casino accepting Amex will handle the card in the same way. Payment arrangements can change, so a past report should not be read as a standing assurance that an Amex transaction will be accepted now.
“Accepted” is a narrow word. It can describe a payment option shown in a cashier, but it does not guarantee that an attempted transaction will pass the issuer’s checks. An Amex casino payment may therefore fail even when the method appears as an option. The visible menu is only one part of the decision.
Gift cards work differently from ordinary Amex cards. An Amex gift card may be used for deposits at a casino that accepts American Express, but its stated role is limited to funding an account. It cannot be treated as a route for receiving casino winnings. A deposit method and a withdrawal method are not interchangeable.
That distinction matters because the word “card” can make two products sound equivalent when their functions are not. A gift card may support a deposit while offering no way to receive money back. Nor does its use remove an issuer-level block: the payment can still be subject to the restrictions applied to the transaction.
I would separate the possible outcomes rather than assume a single cause: a bank may block the gambling transaction, or American Express may block payment to a particular website. The gift-card point is different again; it concerns what the product can do after a deposit is accepted. No single cashier label settles all three questions.
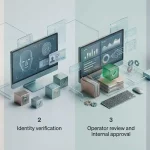
Choosing Amex in a cashier and submitting a payment are not the only steps that can matter. Online casinos typically require customers to complete a Know Your Customer (KYC) assessment before financial transactions. The assessment concerns the account holder; it is separate from the card choice.
That distinction is easy to miss. A payment method can appear in a cashier while an account check remains outstanding. The interface presents a transaction as a short sequence of clicks, but the operator may treat the payment as one part of a broader account review. A submitted transaction and a completed customer assessment are not the same thing.
KYC is the label for checks intended to establish who is using an account. In practical terms, it places an identity assessment between having an account and carrying out financial activity. The requirement is not specific to Amex. Selecting a different card would not, by itself, remove an operator’s customer-verification requirement.
From behind the counter, I would read this as a control point, not as a payment feature. A cashier describes available actions; it does not necessarily indicate that every account condition has been met. That difference matters whenever a transaction is being considered: the payment option answers how an attempt is submitted, while KYC relates to whether the customer assessment required by the operator has been completed.
The assessment can also change how an account’s status is understood. An account may be open, and a payment method may be selectable, without that implying that all checks for financial activity are complete. The wording on a screen can make these stages look like one process. Operationally, they are distinct.
This is why “quick setup” can be a misleading description. It speaks to the act of creating an account, not necessarily to the checks that sit before financial transactions. The label sounds complete. The process may not be.
Know Your Customer (KYC) is an identity assessment required by online casinos to verify the account holder before financial transactions can be carried out.
There is no Amex-specific shortcut in the stated KYC requirement. It applies to customers before financial transactions, rather than being a special condition created by one card brand. Treating KYC as a feature of an Amex casino website would confuse account verification with payment acceptance.
There is also a broader consumer-protection issue in Australia. Australian consumer law does not protect players who use offshore casinos. That does not change what KYC means, but it matters when assessing the significance of an operator’s internal checks: an account assessment should not be mistaken for local consumer protection or local approval.
The practical point is narrow: account verification and payment selection are separate gates. A cashier can show a route for submitting a transaction, while the operator’s customer assessment remains its own requirement. No card label settles that distinction.
An Amex withdrawal is not simply the reverse of an Amex deposit. The first question is whether the casino’s payment rules permit a withdrawal to that card at all. Specialist reviews report that this option is not available at every Australian-facing online casino, and payment arrangements can change. A cashier that accepted an Amex deposit therefore does not, by itself, establish that the same card can receive a payout.
There is also a prior-use condition: a withdrawal through Amex requires an earlier deposit made with Amex. That makes the transaction history relevant to eligibility. If the account was funded through another method, an Amex payout may not be available under the stated rule. In practice, the deposit method and withdrawal method need to be considered together, rather than treating the card as an interchangeable destination for winnings.
I have found that payment labels can make this distinction easy to miss. A method may appear in the cashier for deposits without being offered for withdrawals, or the rules may attach a condition to its use as a payout route. “Amex accepted” is not a complete description of the payment path. The direction matters.
Timing is a separate issue from eligibility. A specialist review gives a reported clearing period of up to five days for casino withdrawals using Amex. That is a source-specific figure, not a promise that every request will reach a card within that time. It also does not mean a withdrawal is instant: the relevant wording concerns clearing, after the casino permits and processes the request. The review’s statement should be read as an indication of reported timing, not as a universal service standard.
This distinction matters when a search for an instant Amex withdrawal points towards language that sounds more certain than the payment process can support. “Instant” may describe a cashier action, a request being submitted, or an internal status change; none of those phrases alone confirms that funds have cleared to the card. The reported period is measured in days, not an instant transfer. I would not treat a fast-looking button or status label as evidence of completed settlement.
Eligibility and timing can therefore be checked as two different questions. First: does the operator’s current withdrawal policy allow Amex, and does the account meet the prior-deposit condition? Second: once a valid request is accepted, what clearing period does the operator state? A positive answer to the first does not settle the second. Nor does a reported timeframe establish that every request will qualify.
The policy can also change between the time a deposit is made and the time a withdrawal is requested. Since specialist reviews reflect the information available when they were prepared, they are not a substitute for the current cashier terms. The practical point is not to infer withdrawal access from deposit access. They are separate functions, with separate conditions.
There is a wider limit to any payment explanation in this market. Australian consumer law does not protect players using offshore casinos, so a payment dispute or delay does not carry the same local consumer safeguards that might apply to an ordinary domestic purchase. That is material when assessing claims about an Amex payout. An advertised route and a reported clearing period are not guarantees of recovery or delivery.
No instant label removes the eligibility condition. The card must have been used for an earlier deposit, and the casino must permit Amex withdrawals under its current rules. The available reporting describes clearing as taking up to five days, but the precise treatment depends on the particular service and transaction. Eligibility first. Then settlement.
A withdrawal route is not guaranteed just because a deposit route appears in a cashier. A specialist review reports that some casinos may not return winnings to Amex, or may attach an additional fee to that withdrawal. Those are separate conditions: one determines whether the card can be used to receive funds, while the other affects the amount paid out.
The wording in a cashier can make the distinction easy to miss. “Amex accepted” may describe deposits only; it does not, by itself, establish that withdrawals to the card are available. A specialist review also reports that Amex deposit and withdrawal limits vary between casinos. The figures and terms therefore belong to the individual operator’s payment rules, not to a universal Amex schedule.
I have seen payment pages treat deposits and withdrawals as different products even when both carry the same card logo. The deposit may be allowed while the withdrawal is restricted, or the withdrawal may be subject to a separate fee. A headline claiming an “Amex withdrawal casino” does not settle either point. The cashier terms do.
Before any transaction, the relevant details are the minimum and maximum amounts permitted for the specific direction of payment, whether a withdrawal fee applies, and whether Amex is listed as an eligible payout method. These details can change, so an old review is not a substitute for the current terms. No single limit can be assumed across online casinos.
There is also a wider Australian protection issue. Australian consumer law does not protect players using offshore casinos, and the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino services to people in Australia. Payment terms do not alter that position.
The practical distinction is simple: deposit acceptance, withdrawal eligibility and withdrawal cost are separate rules. Read as separate terms.
An Amex option is only one part of a casino’s payment setup. A specialist review reports that Visa may be accepted at more Australian-facing online casinos than Amex, but that comparison is a snapshot, not a fixed rule. Payment menus can differ between operators and change over time. A card logo on a page does not settle whether a particular transaction will be available.
I have seen payment choice treated as a simple matter of preference. In practice, each route has its own trade-off: a card may be familiar but not supported everywhere; a bank transfer may provide a different route for moving funds, yet specialist reviews describe transfers as potentially slower and more expensive. The timing and charges depend on the service involved. “Straightforward” is not the same as frictionless.
Cryptocurrency is another route sometimes shown alongside cards and transfers. Bitcoin and Ethereum can provide instant deposits and withdrawals, with limited or no fees. That speed does not make the route interchangeable with a card: the payment is handled differently, and the casino has to support the currency. The headline description “instant” refers to the stated payment capability, not a guarantee that every account or transaction will clear without checks.
Amex can therefore be compared with other payment methods only at the operator level. A site may list one card brand but not another; a bank transfer may carry its own delay or cost; a cryptocurrency option may reduce payment fees while requiring a separate process. The cashier is where those differences become concrete, rather than something that can be inferred from a general claim about a method.
There is also a broader boundary to keep in view: Australian law prohibits operators from providing real-money online casino services to people in Australia. Offshore access does not bring Australian consumer-law protection. Payment convenience does not change that position. No shortcut.
A higher card limit can look like a straightforward advantage, but it is only one part of the payment arrangement. A specialist review reports that Amex transaction limits are higher than the limits offered for Visa and Mastercard. That comparison is not a standing rule for every casino: limits are set by individual operators and can differ between payment methods and accounts.
In practice, the cashier’s displayed limit is the useful figure for a particular transaction. A card’s general spending capacity does not establish what a casino will accept. The operator can set its own minimum and maximum for deposits, and those terms may change. A limit shown for one card or one account should not be assumed to apply to another.
I have seen “higher limits” used as a selling point. The detail behind the phrase is narrower: it describes a comparison reported by a specialist review, not a guarantee that every Amex deposit can be larger than a Visa or Mastercard deposit. Nor does a higher ceiling mean a payment will be approved. The issuer and the cashier each have a role, and the transaction still has to meet their respective conditions.
This is why card limits should be read as payment-specific terms, not as a promise of access to a particular amount. The difference matters most when the amount entered is close to the cashier’s stated ceiling: the relevant limit is the one attached to that payment option at that time, not a general claim about Amex.
There is no universal Amex limit to carry from one casino to another. The comparison may favour Amex in a particular review, while the actual figure remains operator-set. A useful distinction.
Look for American Express in the casino cashier’s deposit options. If it is available, select it, enter your card details and deposit amount in AUD, then submit the payment.
Limits are set by each casino and can vary. Check the cashier’s Amex payment details for that operator’s deposit and withdrawal limits.
Acceptance varies by casino, and Amex or your Australian bank may block gambling transactions to a particular website. A casino that accepts Amex generally may still be unable to process a specific payment.
Amex casino deposits are reported as instant. Withdrawals are different and can take up to five days to clear.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as accepting Amex deposits. These are offshore services, and Australian law prohibits operators from offering online casino games to Australian residents.
Amex casino deposits are processed instantly. Withdrawals can take up to five days to clear.
Some casinos do not allow withdrawals to Amex, and withdrawals may carry a fee. Where Amex withdrawals are supported, you generally need to have deposited with Amex first.