Withdrawal timing depends on both casino handling and payment movement, with PayID and operator conditions shaping what an under-an-hour claim means.
“Under an hour” can describe more than one point in a withdrawal. It might mean that an operator reviews a request within that period, that approved funds are sent to a payment provider within it, or that the money becomes available in the receiving account. Those are separate events. A claim is useful only when its start and end points are clear.
I separate a withdrawal into two broad stages: the casino’s handling of the request and the movement of the money after release. The first is an internal decision and processing stage. The second depends on the payment arrangement and the receiving account. A fast transfer can shorten the second stage; it cannot, by itself, complete the first.
That distinction is easy to lose in promotional wording. “Instant” sounds like a description of the whole journey. In practice, the word may refer only to the transfer after approval. A specialist review has reported cases where a site promoted instant withdrawals but internal review took as long as 24 hours. That report is an illustration of the gap between the label and the full process, not a timing guarantee for every operator.
Withdrawal times can depend on the payment method, so check the stated payout details before choosing a casino. This list highlights what is known about each operator; licensing information alone does not confirm withdrawals in under an hour.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. No withdrawal-speed details are provided.
Ricky Casino
Ricky Casino lists crypto payouts as taking under an hour, while PayID payouts take 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming, with Roby Games Ltd as the operator. No withdrawal-speed details are provided.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curacao licence, with a minimum deposit of A$20. No withdrawal-speed details are provided.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V. No withdrawal-speed details are provided.
SpinsUp
SpinsUp is listed with Curacao Gaming Control Board licence OGL/2023/174/0082, held by Dama N.V. No withdrawal-speed details are provided.
Lucky Dreams
Lucky Dreams is listed with a Curacao licence and a A$20 minimum deposit when using POLi. No withdrawal-speed details are provided.
LuckyVibe
LuckyVibe is listed with Curacao Gaming Control Board licence OGL/2023/176/0095, held by Hollycorn N.V. No withdrawal-speed details are provided.
Golden Pokies
Golden Pokies is listed as Curacao-licensed. No withdrawal-speed details are provided.
Bizzo Casino
Bizzo Casino is listed as licensed by the Curacao Gaming Control Board, with TechSolutions Group N.V. as the operator. No withdrawal-speed details are provided.
A withdrawal request is not necessarily the moment funds begin moving. The request may first enter an operator’s system, where it can be recorded as submitted, pending, under review or awaiting approval. Those labels describe the request’s position in the operator’s process; they do not establish that money has left the operator.
The payment clock starts at a different point: when an approved withdrawal is released through the chosen payment route. The receiving bank or payment service then has its own part to play. A withdrawal could therefore be submitted promptly but remain pending before release, or be released quickly and still take longer to appear in the recipient account. “Under an hour” measured from release is not the same promise as “under an hour” measured from clicking the withdrawal button.
A clear timing claim should identify both endpoints. Does the stated period begin when the request is submitted, when the operator approves it, or when the payment is sent? Does it end when the operator marks the payment as complete, when the payment provider receives it, or when the account holder can use the funds? Without those definitions, a short figure can sound more comprehensive than it is.
This is not a technicality. If a site counts only the interval after it releases a payment, its own processing time may sit outside the advertised measurement. The player experiences one continuous wait; the operator may divide it into separate stages. Both descriptions can be internally consistent, yet only one answers how long the complete withdrawal takes.
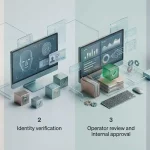
Before a payment can be released, the operator may need to assess whether the request is ready to proceed. Identity checks are part of that stage. Casinos must verify player identity through KYC procedures before processing withdrawals. A first withdrawal can trigger a request for identity verification, as described in specialist reviews. If documents or other required information are still outstanding, the request cannot be understood as a payment already in transit.
That makes a first cashout a poor test of a headline speed unless the verification status is known. Completing identity verification early can significantly speed up future withdrawals. The mechanism is straightforward: a later request is less likely to be held up by an identity check that has not yet been completed. It does not eliminate every possible review, nor does it turn operator approval into a payment transfer.
The review stage may also involve checks specific to the request. A specialist review identifies first-time KYC checks, withdrawals exceeding $2,000 and bank processing windows among possible causes of delay. These are distinct points in the process: identity verification and amount-related review can affect whether an operator releases a payment, while a bank processing window concerns what happens after it has been sent. Grouping all of them under “payment time” hides where a delay actually occurred.
A payment status can be informative if it names the stage accurately. “Pending” suggests that the request has not yet reached completion, but it does not, by itself, explain why. “Approved” indicates a decision by the operator; it does not necessarily confirm that the receiving account has been credited. “Sent” indicates a further step, but a status label is not a substitute for clear terms defining when the operator considers its part complete.
From inside a payment operation, the distinction matters because each stage has a different owner. The operator controls its review and release decisions. A payment provider or financial institution handles subsequent movement. A delay can occur at either point, and a clock that combines them may obscure which one is responsible. The useful question is not merely whether a status changed, but what event that status represents.
Payment infrastructure can move funds quickly once a transaction is released. That fact does not make the operator’s prior review disappear. The phrase “instant withdrawal” can therefore describe a fast payment stage while leaving the total elapsed time dependent on approval.
Consider two separate intervals. The first runs from submission to release. It may include a queue, account checks or a request for identity documents. The second runs from release to receipt. It concerns the transfer itself and the receiving account. A claim about the second interval cannot establish the duration of the first. If the first interval consumes most of the wait, an instant transfer at the end will not make the complete journey an under-an-hour withdrawal.
The reverse distinction matters too. A lengthy transfer does not necessarily mean the operator took a long time to approve the request. The cashout may have been reviewed and sent promptly, while the receiving route takes longer to show the funds. A fair account of timing should not attribute every delay to the casino, just as it should not treat rapid delivery after release as proof of rapid approval.
 $10 Minimum Deposit Casinos in AustraliaLearn why a casino’s advertised $10 floor may not work on every payment route: the effective minimum is the higher of the…
 $20 Minimum Deposit Casinos in Australia: Payment RulesLearn why a casino may state no minimum deposit while a selected payment method still sets a floor, and how the cashier…
For this reason, the word “instant” needs a boundary. It should refer to the payment phase after operator approval, not the full period from request to receipt. Casinos must not claim that withdrawal requests are processed immediately from request to receipt. A statement that leaves the boundary unstated risks implying exactly that.
The total elapsed time is the sum of the periods before release and after release. Each can vary independently. A quick approval paired with a slower payment route may exceed the advertised window. A slow review followed by a rapid transfer can also exceed it. Only when both stages fit within the stated period does the end-to-end withdrawal meet that measure.
The phrase “within an hour” can be read as a promise about elapsed time, but the wording may not say whether the period means continuous clock time or a service window used by the operator. Nor does the phrase alone explain whether it applies to every request, only to eligible requests, or only after verification. Those distinctions belong in the terms and conditions, together with processing times, fees and withdrawal limits.
There is a material difference between a target and a guarantee. A target describes an intended or reported result; a guarantee would imply that the full process will finish inside the period whenever its conditions are met. A short timing statement should not be read as the latter unless the terms actually define it that way. Promotional language often foregrounds the fastest stage, while the operational details determine when that stage begins.
A specialist review has reported that some sites’ “instant” descriptions sat alongside internal review periods that could reach 24 hours. The point is not that every operator follows the same schedule. It is that the adjective can attach to the transfer mechanism without describing the time spent waiting for approval. Once the two stages are kept separate, the apparent contradiction is easier to understand.
“Processed” is another word that can hide a boundary. An operator may use it to mean that a request has been reviewed, that funds have been sent, or that the payment is complete from its perspective. The receiving account may not show the money at the same moment. The terms should make clear which meaning applies rather than leaving the customer to infer it from a status update.
A measured average, where one is published, also says something different from a ceiling. An average does not establish that every request finishes within the stated period. A record time says even less about an ordinary request. For an individual cashout, the relevant questions remain whether the account is verified, whether the request has been approved and released, and what event the operator uses to mark completion.
First withdrawals deserve separate treatment because verification may enter the process for the first time. Specialist reviews describe identity requests as a common feature of initial cashouts. If identity checks have not been completed, a payment-speed estimate measured after approval cannot be applied to the whole request.
Once identity checks are complete, that particular source of delay may no longer apply in the same way to later withdrawals. Completing verification in advance can materially improve the timing of future cashouts. It does not promise that a later request will be released immediately: the operator may still need to assess the request, and the payment stage still begins only after release.
A speed claim that combines first and later withdrawals without distinguishing them can be difficult to interpret. If the first request includes a document review and later requests do not, the elapsed times are not directly comparable. Likewise, an account that is already verified may have a different starting position from one waiting for checks. A useful comparison needs to say which situation the stated time describes.
The process also has a basic compliance boundary. A withdrawal cannot be treated as ready for payment before the required identity verification is complete. That is not a detour from the timing question; it defines what “approval” can mean. A request submitted before verification is finished is still at an earlier stage than a request that has cleared the operator’s checks.
Timing descriptions do not change the legal status of the service being described. In Australia, the Interactive Gambling Act 2001 prohibits operators from supplying real-money online casino games to people physically located in the country. The prohibition covers casino-style offerings such as slots, poker, blackjack and roulette. Advertising real-money interactive gambling services, including online casinos, to Australian audiences is also banned.
This legal context matters when reading material that presents an offshore service as an ordinary local option. A payment claim is not evidence that the service is lawful to provide in Australia, and a fast transfer does not alter the legal position.
The same distinction applies to operator claims about availability. A description of a payment process does not establish that a real-money casino service may legally be offered to people in Australia. Payment mechanics and the legality of providing the underlying gambling service are separate matters.
The clearest reading of an under-an-hour claim is to identify the exact event that starts the clock and the exact event that stops it. If the clock begins only after approval, the claim measures the payment stage, not the time from request to receipt. If the end point is an operator status rather than funds available in the receiving account, it may not measure the full customer experience.
Next, distinguish a request that is ready for payment from one still awaiting verification or review. The first withdrawal can involve identity checks; completing those checks before a later request can reduce one source of delay. A specialist review also reports amount-related review for withdrawals above $2,000 as a possible delay, while bank processing windows can affect the later transfer stage. These factors should not be collapsed into one unexplained figure.
Finally, read “instant” as a limited description unless the terms define otherwise. The word can refer to funds moving rapidly after release. It does not, on its own, tell how long approval takes, whether verification is complete, or when the money becomes available. The stages matter more than the adjective.
That is the measure behind the headline. A complete withdrawal is not just a fast rail, nor just a quick approval. It is the time from a valid request through operator review and release to receipt of the funds. Anything narrower may still describe one real part of the process, but it should not be mistaken for the whole journey. A clock needs endpoints.
Payment speed depends on the rail, but a payment method cannot make an unlawful service lawful. Under Australia’s Interactive Gambling Act 2001, operators may not provide real-money online casino games to people in Australia. The comparisons below describe how payment methods are reported to work; they are not an endorsement of offshore casino services.
E-wallets such as PayPal and Skrill sit between a casino balance and a bank account. A specialist review described e-wallet transactions as completing within hours rather than days, while broader payment guidance puts e-wallet withdrawal processing within 24 hours. Those are not promises for every transaction: timing varies by service and circumstance. The practical advantage is that, once a payment has been sent to the wallet, it does not have to follow the same route as a conventional bank transfer. The wallet may then have its own transfer or withdrawal arrangements.
Traditional bank transfers have a longer reported range. A specialist review said a transfer could take as many as five business days to complete; other payment guidance describes bank transfers as taking several days. The distinction matters because “bank transfer” can describe different stages: a business sending funds, a bank receiving them, and the account showing the cleared balance. A short operator-side estimate does not necessarily describe the full journey.
Transactions are reported to complete within hours or within 24 hours.
Can take several days, with some reports indicating up to five business days.
Payments may take several days; credit cards must not be accepted for online gambling in Australia.
Capable of near-instant transfer at the network level.
Cards also appear in payment comparisons, but the timing descriptions are not as favourable as those for e-wallets. Payment guidance says card payments may take several days. More importantly for Australia, credit card payments must not be accepted for online gambling services. A card’s presence in a general payment list should therefore not be read as permission to use it for a real-money casino transaction. Debit cards are a separate product, but their mention does not change the legal status of the service itself.
Cryptocurrency can move quickly at the network level. A specialist review described crypto transactions as capable of near-instant transfer. That speed is not equivalent to a guaranteed near-instant cashout: the receiving service must support the asset and network, and a transaction’s completion depends on the relevant processing route. The apparent contrast with a bank transfer is real, but it concerns payment mechanics, not a blanket promise about total withdrawal time.
Instant banking services are another category. A specialist review reported that some real-money casino services aimed at Australians offered banking through providers such as POLi. That describes a method available in some offers, not a general feature of Australian bank transfers. Nor does an instant deposit route prove that withdrawals use the same route or move at the same speed. Depositing and cashing out are different directions of payment, with different arrangements.
Vouchers sit at the other end of the comparison. A specialist review described prepaid products such as Neosurf as generally suited to deposits rather than withdrawals. A voucher can therefore be convenient for putting money into an account while offering no direct route for taking money back out. The eventual payout may need to go through a different method, so the voucher itself contributes little to withdrawal speed.
The useful comparison is therefore not simply “fast” against “slow.” E-wallets have reported processing measured in hours, with payment guidance placing them within 24 hours; bank transfers and cards may take several days, and one specialist review reported bank transfers taking as long as five business days. Crypto and instant banking can be described as fast at the transaction level, while vouchers are commonly deposit-only according to a specialist review. Each statement refers to a different mechanism and evidential basis.
A payment label is not a complete timing estimate. “Instant” can describe a transfer rail without describing the entire withdrawal journey, and a method used to deposit may not be available for payout. Comparing methods responsibly means separating those claims rather than treating a fast network as proof that money will reach an account within an hour.
PayID can make the final movement of money quick, but it does not make every part of a withdrawal quick. The useful distinction is between a casino authorising a request and the payment network carrying the released funds. Those are separate actions, handled by different systems.
PayID is Australia’s bank-to-bank instant payment system, operating through the New Payments Platform (NPP). Transfers are processed in real time through the Osko network. In practical terms, that describes the payment rail: once a transaction has been released and correctly directed, the network can move it rapidly. It says nothing by itself about how long an operator takes to review a withdrawal before release.
That difference is easy to lose in the word “instant”. In payment copy, it commonly refers to the transfer after approval, not the full interval from submitting a withdrawal request to seeing funds in a bank account. A request can be waiting for operator action while the payment network is doing nothing, because it has not yet received an authorised payment instruction. Fast rail. Separate queue.
A specialist review of Australian PayID casinos reported withdrawal processing times below five minutes for the leading services it assessed, against one to three business days for standard bank transfers. Another specialist review reported average PayID payout times in a range of 30 to 90 seconds for its selected services. These are reported benchmarks, not a universal service standard or a promise that a particular request will meet the same timing. The measurements depend on what the reviewer counted as the start and end of a withdrawal, and on the services examined.
The key point is not that every PayID withdrawal finishes in seconds. It is that the payment phase can be brief once the operator has released the funds. If a casino keeps a request pending for checks, the elapsed time from clicking confirm can be much longer than the bank transfer itself. An advertised rapid payout and a rapid end-to-end withdrawal are not interchangeable claims.
From the operational side, I would read a payout-time statement as incomplete unless it makes clear which clock it describes. “Processed” may mean the request was reviewed, approved, or sent to the payment provider; “received” means the funds reached the linked account. Those milestones can sit close together, but they are not the same event. The wording matters.
For a PayID withdrawal, the general request path is to sign in, open the wallet or withdrawal area, enter the PayID identifier, set the amount and confirm. That submission starts the operator’s process; it does not itself trigger an instant bank transfer. After approval, the funds can move through the real-time payment infrastructure. Before approval, the request remains with the operator.
This also explains why two withdrawals using the same payment method can take different amounts of time. A payment network can carry an approved transaction quickly, while the operator’s handling of the request determines when that transaction is sent. A first withdrawal may involve additional identity checks, for instance, and the operator may have a manual review process. Those are approval-stage matters, not evidence that PayID itself has slowed down.
There is another distinction between a method being technically fast and a real-money platform being lawful to use in Australia. The Interactive Gambling Act 2001 prohibits operators from providing online casino games, including slots and table games, to people physically located in Australia. A fast payment system does not change that legal position. PayID is a bank payment service, not an endorsement of any casino service that might accept it.
For any general assessment of a claimed under-an-hour payout, the useful question is therefore not simply whether PayID is listed. The relevant details are whether the stated time begins at request or approval, whether the operator sends funds as soon as it approves them, and whether the timing refers to the payment phase or arrival in the account. Without that separation, “instant” can describe only the fastest part of a process whose total duration remains uncertain.
“Under an hour” is only meaningful when the conditions attached to a withdrawal request are clear. A payment can move quickly after release, yet the account may still need checks or the request may fall outside the operator’s rules. In my experience, the small print matters most when a promise sounds unconditional.
There is also a legal boundary that cannot be blurred: Australian law prohibits operators from providing real-money online casino games to people in Australia. The Interactive Gambling Act 2001 covers casino-style services such as slots, poker and table games. The conditions below describe how withdrawal terms are framed; they are not an endorsement or offer of such services.
Identity checks are a common point of friction, particularly on an initial withdrawal. Operators must verify a player’s identity before processing withdrawals, and a request for documents at that stage can interrupt any expectation of rapid payment. Completing verification early can significantly speed up later withdrawals, because the account is less likely to be held while those details are reviewed.
The practical distinction is between a payment method being capable of fast transfers and an account being cleared for payout. “Instant” describes the payment phase after operator approval. It does not mean that the request, account checks and receipt all happen at once.
Payment details also need to match the account. Operators generally direct funds back to the same method used for the deposit where possible. For PayID, the withdrawal details should be the same as those used to deposit, and the destination should be linked to the casino profile. A mismatch can prompt a security review rather than a quick release.
Bonus wagering rules affect when funds become withdrawable. The terms may apply wagering to bonus funds alone or to the combined deposit and bonus. The former is preferable because it limits the amount of funds subject to the requirement.
A withdrawal request made before the applicable wagering is complete may be rejected, delayed or handled under the bonus rules. The important detail is not simply whether a bonus was accepted, but what balance the wagering applies to and what must be completed before a cashout is permitted. Those clauses can matter more than the advertised payment speed.
There is no shortcut around an unmet requirement. A fast payment rail cannot make restricted bonus funds eligible for withdrawal.
The per-transaction maximum is only one part of the cashout rules. Weekly or monthly withdrawal caps may apply separately, so a request can fit within a single-payment ceiling but still be constrained by the amount already withdrawn during that period. Large withdrawals may also be released in instalments under an operator’s policy.
A specialist review has reported automatic approval for some higher-tier PayID services on withdrawals below AUD 5,000. That should be treated as a reported practice, not a general rule: approval thresholds and eligibility depend on the operator’s published terms, and automatic approval does not remove identity or account requirements.
Minimum and maximum withdrawal amounts should be stated clearly in the terms. Fees deserve the same attention. A report by filmink.com.au notes that a fee may apply to a PayID cashout; the amount and circumstances should therefore be checked in the operator’s own fee information rather than assumed from the payment method alone.
Before judging a withdrawal promise, the relevant clauses are those that determine whether a request can be released without further action:
The wording should distinguish the operator’s review from the payment stage. “Instant withdrawal” without that distinction can sound like a promise about the whole journey, when it may refer only to the transfer after approval. The difference is substantial.
A casino’s terms, not a short promotional label, determine the conditions attached to a payout. Where the review stage, limits, fees or bonus rules are unclear, an under-an-hour claim is difficult to assess. No guarantee.
Australian players can use credit or debit cards, PayPal and Skrill, bank transfers, and—in some casinos—cryptocurrency. PayID and POLi instant banking are also offered by some casinos; prepaid vouchers such as Neosurf are generally for deposits, not withdrawals.
They are casinos that make cashouts straightforward and release approved payments quickly, with clearly stated withdrawal limits and supported payment methods. PayID casinos can transfer funds in real time once the casino releases a withdrawal, although operator review may still add waiting time.
Check when the casino’s advertised withdrawal clock starts and ends, which payment methods it supports, and whether it clearly publishes withdrawal limits. Completing identity verification early can help avoid delays on later cashouts; also check whether fees or cashout limits apply.
PayID withdrawals can arrive almost instantly after casino release, with leading options averaging 30–90 seconds; the casino’s review may take longer. E-wallet withdrawals are typically processed within 24 hours, while bank transfers and card payments can take several days, and traditional bank transfers may take up to five business days.