A wallet transfer may move quickly, while crediting a deposit and reviewing a later withdrawal remain separate steps.
Bitcoin can make the payment leg feel simple: a transfer is initiated from a wallet, and the casino account may show a deposit after the transaction is recognised. That speed is separate from identity checks. A payment reaching an account does not establish that the account holder has passed verification, nor does it remove checks that may arise later.
A specialist review describes cryptocurrency transactions as capable of near-instant movement. That is a statement about the payment method, not a promise about the full account process. The wallet transfer, the operator’s decision to credit a balance, and any later review are different steps. An advertising phrase such as “instant Bitcoin deposit” often compresses those steps into one claim. The distinction matters. Fast movement of funds does not mean fast approval of an account or a withdrawal.
I have seen payment language do a lot of work with very little detail. “No KYC” can sound like a description of the whole relationship, when it may refer only to what is requested at registration or before a deposit. Bitcoin does not make identity checks impossible, and using it does not guarantee that no documents will be requested. Operators must verify player identity before processing withdrawals. A deposit accepted without an immediate document request therefore says little about what will happen when money is later requested back.
Choosing a no-KYC casino in Australia calls for checking the available details rather than assuming every operator handles accounts or payments the same way. This list offers a concise reference to the information provided for each operator.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd.
Uptown Pokies
Uptown Pokies is listed as operating under a Curacao licence since 2017. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as operating under a Curacao licence, with Dama N.V. as its operator.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams lists a Curacao licence and a A$20 minimum deposit when using POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence; no further operator details are provided here.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence, with TechSolutions Group N.V. named as the licensee.
There is also a legal boundary specific to Australia. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia. Bitcoin does not change that rule. The payment rail is not a workaround: a crypto transfer does not make a prohibited casino service lawful. This is a material distinction, not a footnote about payment preferences.
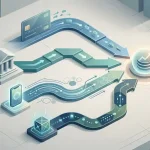
The practical mechanics are easier to read when separated into stages:
A fast first stage cannot guarantee that the later stages happen at the same pace. The operator’s internal handling still matters, and the deposit itself does not answer whether the account can be used or whether a later payment will be approved. This is why a “no KYC Bitcoin casino” claim should not be treated as a promise that verification will never occur.
Bitcoin also changes the way a payment is described, not the obligations that apply to the service. A card, bank transfer, e-wallet or cryptocurrency may be offered as a funding method in some real-money casino listings; a specialist review of Australian payment options has reported that mix. Availability varies by operator and does not establish that the service is lawful for Australian residents. The method should not be confused with an endorsement of the operator.
For anyone assessing a claim about a bitcoin casino with no KYC, the useful question is not simply whether the deposit form asks for documents. It is what the terms say about identity checks, account restrictions and withdrawals. A site can accept a crypto payment and still require verification before releasing funds. It can also place an account under review after a deposit. “No documents at sign-up” and “no verification at any stage” are not interchangeable claims.
I would treat the word “fast” just as narrowly. It can describe movement on the payment network, but it does not establish when an account balance will be credited or when a later withdrawal will be cleared. Those depend on separate processes. The headline may be short. The conditions are not.
The phrase “best no-KYC casino” is especially poor as a decision rule. It combines a promotional ranking with a claim that can be narrower than it sounds. Neither Bitcoin nor another cryptocurrency removes the Australian legal restriction on online casino services, and neither makes a no-verification promise reliable by itself. A payment method is not a compliance status.
The central point is straightforward: Bitcoin’s potential transaction speed concerns the transfer, while identity verification concerns the operator’s account controls. They are separate questions. For Australians, there is an additional issue before either one: real-money online casino provision to people in the country is prohibited under the Interactive Gambling Act. A quick crypto payment does not alter that position.
“No KYC” is a claim about identity checks, not a reliable description of every stage of an account. In crypto-casino marketing, it can mean that registration does not immediately ask for identity documents. It does not establish that the operator will never request them, or that a withdrawal will be released without a review.
I treat the label as narrow until the terms say otherwise. A crypto casino may let someone create an account and make a deposit without completing document checks at that point. The position can change when the account requests a payout. A specialist review has reported that first withdrawals often prompt identity-verification requests. That is a report, not a promise that every operator follows the same process.
The distinction matters because depositing and withdrawing are separate decisions for an operator. A deposit being accepted does not prove that the account has passed every check relevant to a later payout. Nor does using cryptocurrency, by itself, remove the possibility of a request for documents. “No KYC” can describe the initial sign-up experience while leaving the withdrawal process subject to verification.
The phrase can conceal several different policies. It might describe an account that asks for no documents at registration; one that requests checks only when a withdrawal is made; or a service that reserves the right to ask for information when it considers a review necessary. Those are materially different arrangements, even if the same short label is used for all of them.
The practical question is not simply whether a site calls itself a no-KYC crypto casino. It is when its terms allow verification, what happens to a pending withdrawal during that process, and what information may be requested. If those points are not clear, the slogan does not answer the questions that matter when money is being withdrawn.
That uncertainty is especially easy to miss when a payment method appears straightforward. Crypto describes how funds are transferred; it does not, on its own, define an operator’s identity policy. A transaction can be recorded on a network while the operator separately decides whether to release a withdrawal. Fast payment mechanics are not the same thing as approval.
I have seen how wording does its work: “no KYC” sounds absolute, while the operational meaning may be limited to the first step. The gap is not necessarily hidden in the phrase itself; it is often in what the phrase does not specify. No documents at sign-up is not equivalent to no checks at any point.
An account may function without a document request until its first payout is submitted. At that moment, the operator can ask for identity verification before processing the withdrawal. The request can interrupt the sequence even when deposits and play have already taken place. That is why the absence of an earlier check should not be read as confirmation that one will never occur.
Completing verification early can significantly speed up later withdrawals. The benefit is procedural: if the account has already cleared the relevant checks, a later request may not have to pause for the same step. It does not mean that every withdrawal will be approved instantly, or that additional review is impossible. It means one potential source of delay has been dealt with before a payout is waiting.
A first withdrawal can therefore expose a mismatch between the advertising phrase and the account’s actual conditions. The operator may treat registration as low-friction while retaining verification as part of its payout process. From the player’s side, that can feel like a new rule appearing at the last moment. From the operator’s side, it is a check that was deferred rather than removed.
The useful distinction is simple: “no KYC at sign-up” is a statement about registration; “no KYC ever” would be a much broader claim. A label alone does not establish the broader version. Terms governing verification and withdrawals carry more weight than a short promotional description.
For people physically in Australia, there is also a separate legal issue that a payment label cannot resolve. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino services to customers in Australia, including casino-style games such as slots, poker, blackjack and roulette. A cryptocurrency payment does not change the nature of the service or remove that restriction.
This is not a recommendation to seek out an offshore crypto casino, nor does “no KYC” make such a service lawful to provide in Australia. It is a description of how the term is used and why it should not be mistaken for a guarantee about checks or payouts. The label may sound like a complete policy. In practice, it is only as meaningful as the conditions behind it.
For a careful reading, separate three claims that are often compressed into one: whether documents are requested at registration, whether identity checks may arise before a withdrawal, and whether completing those checks ahead of time can make later withdrawals move more smoothly. They are related, but they are not interchangeable. The first says little about the second; the third explains why timing matters.
No KYC at entry. Not necessarily at exit.
“No KYC” is a claim about when an operator asks for identity documents, not a reliable promise that no check will happen. KYC means “know your customer”: the process of confirming who holds an account. A service may allow account registration or play before requesting documents, then pause a cashout until the checks are complete. The label describes a point in the process, not necessarily the process as a whole.
That distinction matters most at the first withdrawal. Specialist reviews of casino withdrawal processes report that an initial cashout request often brings an identity-verification request with it. The operator may ask for documents before releasing funds, even where the account was opened without them. In practical terms, “no KYC” can mean “no documents requested at sign-up” rather than “withdrawals are exempt from verification.”
I separate the advertised sign-up experience from the cashout procedure. An account can appear ready for use while remaining unverified for withdrawals. The first request then becomes a checkpoint: the operator reviews the account and asks for whatever is needed to establish identity. Until that step is complete, a pending withdrawal is not the same as a payment that has been approved for release.
The timing can also affect later requests. Completing identity checks early can significantly speed up future withdrawals because the operator has already dealt with the verification step. It does not remove every possible review, nor does it mean a withdrawal is automatically approved. It does mean that a later request is less likely to be held up by the same outstanding identity check.
This is why I read “no KYC” as a narrow description, not a guarantee. The useful distinction is whether checks are delayed until a withdrawal, not whether the operator will ever ask for them. Any wording that treats the absence of a sign-up document request as proof of unrestricted cashouts leaves out the part that matters when money is requested.
There is also a legal context specific to Australia. Under the Interactive Gambling Act 2001, operators are prohibited from supplying real-money online casino games to people located in Australia. That covers casino-style services such as slots, poker, blackjack and roulette. A “no KYC” label does not change the legal status of an offshore service or make it a lawful Australian real-money casino.
For that reason, this phrase should not be read as a local consumer protection or a sign that a service has been cleared to operate in Australia. It says nothing by itself about the legality of the operator, the checks attached to withdrawals, or whether funds will be released. The mechanics are separate.
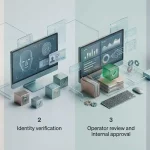
A careful reading focuses on the withdrawal terms: when identity checks can be requested and whether approval is required before payment. “Instant” or “no KYC” language cannot collapse those stages into one. Verification, operator approval and payment are distinct steps, and a delay at the first can prevent the later ones from starting.
The practical meaning is narrower than the slogan. Some operators defer identity checks until a withdrawal, but a first cashout can still trigger them, and completing verification early can make subsequent requests move faster. No shortcut in the wording.
A “no-deposit” label describes how an offer is presented, not what must happen before any resulting balance can be withdrawn. Free spins and bonus credits may look separate from a cash deposit, but the relevant condition is the wagering basis: which funds the requirement applies to. A specialist review describes two possible structures—wagering on bonus funds alone, or wagering on the combined deposit and bonus. The first is the more favourable arrangement for the player because it does not add the deposit to the amount subject to wagering.
That distinction is easy to miss when terms use a single headline figure or place the calculation deep in the offer rules. The practical question is not simply whether a bonus has wagering attached. It is whether the rule counts the promotional funds alone or treats those funds and deposited money as one combined base. The same bonus value can therefore carry a different commitment depending on how the operator defines that base.
A no-deposit bonus can sound cost-free because no initial payment is required to receive it. That description does not settle whether the bonus is withdrawable, what activity is required before withdrawal, or which balance is used in the calculation. Those details belong to the terms. “Free” is the advertising word; the calculation is the condition that gives it practical meaning.
With bonus-funds-only wagering, the deposit is outside the wagering base. With combined wagering, the deposit and bonus are counted together. That difference matters because the second structure attaches the condition to a larger pool of funds. It is not a minor wording preference: it changes what must be wagered before a withdrawal can be attempted.
The wording should make the base identifiable. Terms that refer to “the bonus” point toward bonus-only treatment; wording that refers to “the deposit and bonus” describes a combined base. If the text switches between those expressions, or leaves the base unclear, the offer cannot be assessed from its headline alone. Ambiguity is not a favourable term.
Free spins are a promotional format, not proof that the resulting balance is free of conditions. Their presence does not answer the key question: whether any wagering applies to the bonus funds, and whether the deposit is included in that calculation. The label may describe the way the promotional play is delivered, while separate terms determine what happens to any balance connected with it.
The same distinction applies to offers described as no-KYC or crypto bonuses. Those labels concern other aspects of an offer; they do not establish whether wagering applies to bonus funds alone or to a combined deposit and bonus. A claim about verification or payment method cannot substitute for reading the bonus calculation. Different conditions, different questions.
There is also a legal boundary that promotional wording should not obscure. Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games to people physically located in Australia is prohibited for operators; casino-style services such as slots, poker and table games fall within that restriction. A bonus description does not change the legal status of the underlying service.
When wagering applies only to bonus funds, the deposited amount is not added to the wagering base. That is why this structure is preferable to one that combines both balances: it narrows the funds covered by the condition. It does not make an offer automatically worthwhile, nor does the phrase “bonus-only” answer every question in the terms. It identifies one important part of the calculation.
A useful reading order is to locate the definition of the wagering base first, then check whether the offer refers to bonus funds alone or includes the deposit. Next, separate that definition from the promotional headline. The headline may make the offer sound simple; the rule determines the actual scope of the commitment. If the terms do not clearly establish which balance is counted, there is no sound basis for assuming the more favourable interpretation.
The “best” no-deposit offer cannot be determined from the no-deposit label, a free-spins headline, or a no-KYC claim alone. For this specific comparison, bonus-funds-only wagering is preferable to combined deposit-and-bonus wagering. That is a limited but meaningful test: it distinguishes a narrower wagering base from a broader one without pretending that promotional language settles the full value of an offer.
The point is not the size of the headline. It is the base.
In Australia, the timing of a casino payout is not just a question of which payment method appears in the cashier. Real-money online casino games are prohibited services under the Interactive Gambling Act 2001, and offshore sites are subject to active blocking and enforcement. The payment mechanics still matter when interpreting claims about “instant” withdrawals, but they do not make the service lawful.
Withdrawal Process
Operator Review
The operator assesses the request, which may include identity checks and internal processing.
Fund Release
The operator approves the request and releases the funds to the payment network.
Network Delivery
The payment network (such as PayID or an e-wallet) delivers the funds to the user's account.
I separate a withdrawal into two stages: the operator’s decision to release the funds, then the payment network’s delivery to an account. The first stage can include checks and internal processing. The second depends on the method and, for bank transfers, the bank’s processing window. “Instant” often describes only the transfer after approval—not the full time from submitting a request to receiving money.
PayID is Australia’s bank-to-bank instant payment system, running through the New Payments Platform. That infrastructure can move funds in real time, but it cannot make an operator approve a request immediately. A specialist review describes PayID funds as arriving instantly after the casino releases them; that is a claim about the payment phase, not a promise about the whole withdrawal.
The distinction is operational, not cosmetic. A request may remain pending while identity checks or other internal reviews take place. One specialist review also reported sites advertising “instant” payouts that took as long as 24 hours because of internal review. The label did not remove the queue. It described the intended payment speed once the queue was cleared.
PayID details also need to match the deposit details. Using different details can prompt a security review, and funds should go only to an account linked to the casino profile. A withdrawal request may involve opening the wallet or withdrawal area, entering the PayID identifier, specifying an amount and confirming. The steps are simple; approval is the variable.
E-wallet withdrawals are often handled within 24 hours, while bank transfers and card payments can take several days. Those timings are not equivalent: “processed” may mean the operator has approved or sent the payout, not that the recipient can already see it. Bank processing windows can add time after release.
A specialist review identified first-time identity verification, requests above $2,000 and bank processing windows as possible causes of delay. Identity checks are not an optional add-on to a no-KYC promise: casinos must verify identity before processing withdrawals. A request that triggers a first-time check can therefore pause before the payment method has any role.
For the same reason, a casino no-KYC withdrawal should not be read as guaranteed cash arriving without checks. Payment speed and verification status are separate matters. Completing verification early can make later withdrawals faster, but it does not turn a bank transfer into a real-time payment or guarantee an operator’s approval time.
I have seen the wording do more work than the payment system. A cashier may display a fast method, yet the operator still controls when the payout is released. After release, PayID’s real-time infrastructure can help the funds reach a bank account promptly; an e-wallet has its own processing path, and a traditional transfer can take longer.
The practical comparison is therefore not “instant versus slow” in isolation. It is operator review, payment processing, then receipt. Withdrawal limits, fees and processing times belong in the operator’s terms, and large withdrawals may be subject to manual review under the operator’s policy. The clock starts later than the headline suggests.
Payment labels describe different jobs. A card, e-wallet or bank transfer may be offered for adding funds, while the route for taking funds out can be narrower. A specialist review of payment options for Australian players describes debit cards, PayPal, Skrill and bank transfers, with cryptocurrency offered by some operators. Availability is not uniform, and a payment logo does not establish that the same method works in both directions.
Draws on bank account funds; availability for withdrawals varies by operator.
Services like PayPal and Skrill that move funds between accounts; often processed within 24 hours.
Direct movement between bank accounts; may be subject to bank processing windows and delays.
Deposit-focused options like Neosurf; generally cannot be used to receive withdrawals.
The legal position matters more than the menu. Under Australia’s Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in Australia. This includes slots, poker and table games. Payment information about offshore real-money platforms is therefore descriptive, not an invitation or a recommendation. Credit cards are not an appropriate payment route for online gambling services.
A debit card draws on funds held in a bank account; it is not the same as borrowing on a credit card. Even where a payment page lists a card option, the distinction between deposit and withdrawal remains important. A method that can fund an account does not necessarily give the operator a way to return money to that card.
PayPal and Skrill are e-wallets. Their role is to hold or move funds between accounts, rather than to operate as a bank transfer itself. Whether an e-wallet is offered depends on the platform and its payment rules. It is also possible for a cashier to accept a method for deposits but not display it for withdrawals. The interface tells only part of the story.
“Available” is not the same as “available both ways.” That detail matters.
A bank transfer moves funds between bank accounts, but its function is different from a wallet’s. It may be presented as a deposit route, a withdrawal route, or both; the operator’s terms determine which. Banks can also impose their own checks or restrictions, separate from any platform process.
Payment pages can make bank transfers look interchangeable with e-wallets. They are not. The accounts involved, the information required and the route for returning funds can differ. Any withdrawal method should be considered alongside the platform’s stated conditions, rather than inferred from the deposit screen.
Prepaid cards and vouchers, including Neosurf, are described in specialist reviews as deposit-focused options, generally not a way to receive withdrawals. The practical reason is straightforward: a voucher can provide a code or stored value for paying in, but it may not be linked to a personal account capable of receiving a payout. A deposit option is not a cashout option.
That makes prepaid products distinct from bank transfers and e-wallets, which may support movement in both directions depending on the operator. The distinction is useful when reading a payment menu, but it does not change the legal status of real-money casino services in Australia. Nor does using a wallet, voucher or other payment rail make a platform “no KYC.” Payment method and identity checks are separate matters.
Ethereum, Ripple and Tether are names often encountered when comparing crypto payment options, but their appearance in a payment menu cannot be assumed. A casino may support one currency and not another, and the same asset can be handled through different networks. The payment details need to identify the currency and network together; a familiar ticker alone is not enough to establish how a transfer should be made.
A specialist review describes cryptocurrency transactions as capable of being near-instant. That refers to the transfer stage, not necessarily to the time a service takes to recognise, credit or release funds. A transaction may move quickly while a platform’s own processing remains separate. “Instant” is a narrow claim. It is not a promise about the whole payment journey.
The distinction matters when a service describes itself as a no-KYC casino. The label does not establish that Ethereum, Ripple or Tether is accepted, nor does it guarantee that funds will be available as soon as a transfer is sent. Currency support, network compatibility and the service’s own handling are separate questions. No shortcut around those distinctions.
There is also a legal boundary specific to Australia. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in the country. That prohibition covers casino-style games such as slots, poker and table games. Crypto payment capability does not change the legal status of the service.
In practical terms, “Ethereum casino” or “Ripple casino” describes a payment idea, not evidence that a particular operator accepts the currency or can lawfully serve Australian players. The transfer technology and the service accepting it are different things.
USDT may appear alongside crash games on sites advertising access without identity checks, but the payment method does not establish that a service is legitimate or available to Australians. The distinction matters: a token transfer and a casino’s decision to accept, hold or release funds are separate steps.
A specialist review describes cryptocurrency transactions as capable of being near-instant. That refers to the transfer, not necessarily the full path from a deposit request to usable balance or from a withdrawal request to money received. A platform may still have its own processing stage. “Instant” is a narrow claim, not a description of every step.
Crash games do not change those mechanics. A game’s format says nothing about whether USDT is accepted, whether an account can be used without checks, or how a withdrawal will be handled. The same caution applies to offers framed as no-deposit access: the wording alone does not explain the payment route or the conditions attached to funds.
Prepaid options work differently. A specialist review reports that cards and vouchers such as Neosurf are generally described as deposit methods rather than withdrawal routes. That can leave a separate method necessary for cashing out; the advertised deposit option is not necessarily a complete payment cycle.
There is also a legal boundary. Under Australia’s Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including crash-style casino play, to people physically in Australia. A USDT label, a no-KYC claim or a free-entry offer does not alter that rule. Payment wording is not permission.
A live dealer changes how a game is presented; it does not change the payment controls behind an account. The presence of a streamed table, a human dealer or real-time chat is not evidence that a platform will waive identity checks when funds are requested.
A specialist review noted that first withdrawals often prompt a request to verify identity. That can apply even when the account has been used only for live casino play. From the operator’s side, the withdrawal is a separate decision from whether a player could enter a game: the account and the payment request may still need to be checked before funds are released.
I have seen “no KYC” used as if it described every stage of an account. In practice, the wording can refer to registration or initial play, while leaving the first cashout subject to review. The game format does not settle that distinction.
The useful detail is therefore not whether a live casino advertises minimal sign-up checks, but what its withdrawal terms say about identity documents and review. A request for verification can delay a first payout, regardless of whether the balance came from a live table or another game. Different format. Same checkpoint.
In Australia, real-money online casino games are prohibited services when provided to people in the country. A “no KYC” label does not alter that legal position or remove withdrawal checks.
E-wallet withdrawals are typically processed within 24 hours, while bank transfers and card payments can take several days. PayID withdrawals may be released in seconds, but first-time verification, internal reviews and withdrawal limits can cause delays.
PayID casinos with real-time transfers and clearly published withdrawal limits may offer quicker payouts; reported examples averaged 47 seconds at Fastpay Casino and 68 seconds at PlayAmo. These figures do not guarantee a payout time, and real-money online casino services are prohibited for people located in Australia under the Interactive Gambling Act.
Check that withdrawal limits and payment conditions are clearly published, and complete identity verification early to reduce the chance of delays later. Also check whether withdrawals must go back to the deposit method and whether separate weekly or monthly cashout limits apply; real-money online casino services are prohibited for people located in Australia.
Options reported at Australian casino listings include credit and debit cards, PayPal and Skrill, bank transfers, and sometimes cryptocurrency. PayID and instant banking services such as POLi may also be available; prepaid cards and vouchers are generally for deposits, not withdrawals.