A familiar mobile wallet does not prove a gambling cashier supports it, and deposit availability does not guarantee the same withdrawal route.
Google Pay is familiar to many Australians because mobile wallets are accepted almost everywhere across the country. Apple Pay is also widely accepted, and people are comfortable moving between mobile wallets, cards and bank-linked services such as PayPal. That everyday experience can make a wallet seem like a natural option whenever an online payment screen appears.
But acceptance in one setting does not carry over automatically to another. A wallet working at a shop, café or other ordinary merchant does not establish that a particular online service supports it. The same distinction applies to an online gambling cashier: broad familiarity with Google Pay says nothing conclusive about the payment methods available at an individual cashier.
I learned to separate the name of a payment method from the route that actually appears in a transaction. A familiar logo can set an expectation, but the logo is not the transaction. What matters for any service is whether that service presents the method as an available option under its own conditions. General use across Australia cannot answer that service-specific question.
Google Pay availability can vary by casino and payment setup, so check the cashier before choosing how to deposit. This guide offers a concise reference to the listed operators using the details available for each.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts under one hour and PayID payouts in 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed under a Curacao eGaming licence held by Roby Games Ltd.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curacao licence. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed under a Curacao licence and is operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams is listed under a Curacao licence. Its minimum deposit is A$20 when using POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed under a Curacao licence.
Bizzo Casino
Bizzo Casino is listed under a Curacao Gaming Control Board licence held by TechSolutions Group N.V.
Mobile wallets often feel less like a separate payment product than a digital version of a card already in use. That makes them easy to recognise and simple to reach for. Yet recognition is not evidence that every online checkout has connected the wallet to its payment process. A service may display some payment methods and not others; another may present a different set. The national popularity of a wallet does not standardise those choices.
This is where broad statements can become misleading. “Accepted almost everywhere” describes the wide availability of mobile wallets in Australia, not universal acceptance by every type of business or by every online cashier. The phrase has a geographic, everyday meaning. It is not a guarantee about a particular transaction.
In operational terms, there are two separate questions. Is Google Pay commonly used in Australia? Yes. Does that establish that a specific online casino cashier accepts it? No. The first is about consumer familiarity and general merchant acceptance. The second is about an individual service’s payment setup. Combining them turns a true general observation into a claim it cannot support.
That distinction matters even when the interface looks straightforward. A payment logo on a page may be a general symbol, an option that applies only in certain circumstances, or a method that is not available in the relevant transaction flow. Without seeing it presented as an active option for that service, a logo alone should not be treated as confirmation. Familiarity can narrow the reader’s expectation; it cannot substitute for evidence.
Descriptions such as “Australian online casino” can also blur separate ideas. The word may refer to an audience, a site’s marketing language, or the location of the people looking at it. It does not, by itself, establish how the cashier is configured or what payment methods it offers. Adding “Google Pay” to the description does not fill that gap.
I have seen the same reasoning slip into broad claims about online pokies: because people use Google Pay widely in Australia, a service aimed at Australians must accept it. That conclusion does not follow. Consumer habits describe what people are accustomed to using across many settings. They do not prove that a particular gambling cashier has made the wallet available.
There is a practical difference between an option being familiar and an option being supported. Familiarity concerns the user’s experience with the wallet generally. Support concerns a specific service and its own transaction interface. The two can coincide, but one does not prove the other. No amount of local comfort with mobile payments changes that basic distinction.
Nor does a preference for mobile payments make an online service’s payment menu predictable. Australians may move readily between cards, wallets and bank-linked services, but that flexibility describes consumer behaviour—not a shared payment arrangement across unrelated services. Each cashier remains a separate case.
The useful starting point, then, is modest: Google Pay is widely accepted in Australia, and people are accustomed to using mobile wallets alongside other payment methods. That context explains why someone might expect to see the wallet offered online. It does not establish that any particular online gambling cashier accepts it, and it should not be turned into a list or recommendation based on assumption.
That is the boundary I keep in view. National familiarity is real. Service-specific acceptance is a separate matter. A familiar wallet is not proof.
A statement that a casino accepts Google Pay for deposits is only useful if it describes a real payment option in the cashier. A wallet can be familiar to Australian consumers without appearing in a particular service’s deposit menu. I treat those as separate facts: one concerns how people pay generally; the other concerns what a specific cashier offers at the point of deposit.
The wording matters. “Google Pay accepted” may refer to a merchant’s general payment facilities, a payment processor’s capabilities, or a feature available only in certain circumstances. It does not, on its own, establish that Google Pay is selectable for a casino deposit. The claim needs to identify the transaction it covers: depositing funds through the cashier using Google Pay. Without that link, the label leaves too much unsaid.
I learned to read payment language as a description of a process, not a badge. An operator’s payment page may mention a wallet, while the cashier presents a different set of options. The cashier is where the deposit choice is made, so that is the relevant place to verify whether the method is currently offered. A general logo or a broad statement about accepted payments is weaker evidence than an actual, clearly labelled option within the deposit flow.
Even then, a visible option does not explain every condition attached to it. A useful deposit claim should make clear what the method is being used for and where its terms can be checked. It should not blur deposits with other financial functions or imply that one payment label covers every stage of an account’s activity. That distinction keeps the claim narrow and testable.
The deposit instructions should also be specific enough to describe what the user is being asked to do. For a wallet-based payment, the relevant information would include selecting Google Pay in the cashier, confirming the transaction through the payment interface, and seeing whether the deposit is accepted. Those are steps to look for in a stated process, not a promise that every cashier follows the same sequence. If the description skips from “wallets are supported” straight to “deposit made,” it has compressed several separate checks into one sentence.
The amount and currency are another part of the claim’s scope. A headline about a deposit should not be read as proof that every amount or currency will be available under identical conditions. Those details belong to the cashier’s displayed terms. I would not infer a minimum, maximum, or a particular transaction value from the mere presence of a Google Pay reference. A search phrase containing a specific amount is not evidence that the cashier permits that amount.
Verify a Deposit
Select method
Choose Google Pay within the casino cashier.
Confirm transaction
Complete the payment through the mobile wallet interface.
Check balance
Verify that the deposit is accepted and recorded in the account.
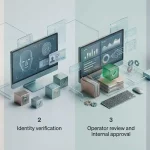
There is also an account-level step that can affect when financial activity is allowed. Online casinos commonly ask customers to complete identity checks before permitting financial transactions. In practice, that means the payment method is not the whole process: account verification may form part of the conditions around a deposit. A description that presents wallet selection as the only relevant step leaves out that separate requirement.
This is why the word “instant” can be misleading even when it appears beside a deposit method. A payment interface may complete its part of a transaction quickly, but that phrase does not explain whether an account has met the service’s checks or whether the cashier has accepted the deposit. I avoid treating a speed label as a complete account of the transaction. The operational question is whether the deposit is actually recorded, under the stated terms.
A precise claim therefore has boundaries. It says that Google Pay is listed in the cashier for deposits, identifies the relevant terms as the place to confirm conditions, and avoids implying that general wallet acceptance settles the matter. If the wording does not specify the cashier or the deposit function, it may describe a payment capability in the abstract rather than an available deposit route.
In reviewing payment copy, I have found that the most reassuring phrase is often the least informative. “Easy,” “seamless” and “accepted” sound definitive, but they do not tell us what option appears, what transaction it applies to, or what account checks remain. Clear wording is less glamorous: it states the payment purpose and points to the conditions that govern it.
The standard is modest but important. A deposit claim should be tied to the cashier and the deposit process, not inferred from the broad presence of a mobile wallet in everyday commerce. If those details are absent, the claim has not established the specific point it appears to make. A label is not a transaction.
A comparison of payment acceptance only works when it measures the same thing on both sides. Contactless credit and debit cards are accepted almost everywhere in Australia, but that describes everyday payments at physical points of sale. It does not establish which methods an online casino cashier supports. The word “accepted” changes meaning with the setting.
That distinction is easy to miss because a tap-to-pay transaction can feel like a direct test of whether a card or wallet will work online. It is not. A merchant’s contactless terminal and a website’s cashier are different payment environments. Broad acceptance in shops cannot be carried across as evidence about a particular online service.
I have seen comparisons go wrong when they put unlike measures in the same table: one column reflects everyday card use, another a claim about a specific online cashier, and the result is presented as though both were counted on the same basis. The layout looks tidy. The comparison is not.
A useful comparison has to identify what “support” means. Is it an option shown to customers in the cashier, a method that can be selected for a particular transaction, or a general statement that a service takes a certain payment type? Those are not interchangeable claims. Nor does a broad label such as “mobile payments” confirm that Google Pay itself is available. The precise method matters.
The same standard applies across services. A comparison should keep its scope consistent: Australian customers, the same kind of online transaction, and acceptance assessed at the same point in time. If one entry refers to a current cashier and another repeats a general description, the apparent difference may be a difference in evidence rather than in actual support. Payment menus can change; a comparison without a clear basis can age quickly.
Card comparisons require similar care. A specialist review has suggested that Visa may be more widely accepted at Australian online casinos than American Express. That is a limited observation from a particular type of source, not a fixed rule for every service or a substitute for checking an individual cashier. It also says nothing by itself about Google Pay. One method’s reported reach cannot be used to fill in another method’s availability.
The label “best” adds another problem. A payment comparison can describe whether a method is reported as accepted, but that alone does not establish which service is best. Acceptance is one narrow attribute. A ranking would need a defined basis and comparable evidence, rather than an assumption that the broadest-looking payment menu settles the question. A polished table cannot repair a weak comparison.
For Google Pay, the same boundary holds. Widespread contactless card use in Australia gives useful context about familiar payment behaviour, but it cannot verify online support. A service’s payment options need to be assessed as that service’s own options; they cannot be inferred from the prevalence of taps at shops or from acceptance of cards in general.
The practical distinction is modest but important: everyday availability is not online availability, and a general payment category is not confirmation of a named method. Compare like with like. Otherwise, the table may answer a different question from the one its headings appear to ask.
A payment can appear immediate at the deposit stage and still tell little about when money would be returned. The cashier’s payment label describes one part of a transaction, not a complete timetable from payment to payout. I learned to read those as separate processes: an incoming payment may be authorised promptly, while a withdrawal has its own handling and clearance steps.
Amex provides a useful contrast. Casino deposits made with Amex are described as processing instantly. A specialist review, however, gives a different timeframe for withdrawals made through Amex: they can take up to five days to clear. That is a reported condition, not a universal promise for every service or transaction. The difference matters more than the word “instant”. It shows how a quick deposit does not establish quick access to a withdrawal.
The word “instant” is often doing narrow work. It may refer to the point at which a deposit is accepted or credited, rather than the full movement of funds through every stage. A cashier can confirm that a payment has gone through without confirming when a later payout would arrive. Different processes; different clocks.
That distinction also limits what can responsibly be said about Google Pay. A Google Pay symbol, if shown in a payment context, would not on its own prove that withdrawals are sent through the same channel, or that they arrive instantly. The Amex timing is a contrast about payment processing; it is not evidence of Google Pay’s casino acceptance or payout speed. A payment method cannot stand in for a confirmed withdrawal route.
I have seen how a single label can flatten several operational questions into one attractive claim. “Fast” sounds like a promise about the whole journey, but the underlying terms may be talking only about deposit authorisation. For a withdrawal, the relevant detail is the stated payout method and its own processing conditions. Without those, a claim of instant withdrawal is not established by the speed of a deposit.
There is a practical difference between a transaction being accepted and funds being cleared. The first concerns whether the payment proceeds at the point of deposit; the second concerns when a withdrawal is completed. Treating them as interchangeable creates a false expectation, especially when a page puts both under a broad heading such as “instant payments”. The wording may be technically narrow while the impression is much wider.
So an instant deposit statement should be read as a statement about that deposit alone. It does not guarantee that a later withdrawal will use the same method, follow the same timing, or be instant. For Google Pay, no payout-time claim follows from the Amex comparison. A label is not a timetable.
A search for a casino that takes Google Pay can sound like a narrow question about a payment option. In Australia, however, the legal status of the service sits behind that question. A payment method does not change the rules governing who may provide real-money online casino games to people in the country.
The Interactive Gambling Act 2001 prohibits operators from offering online casino games to Australian residents. That covers casino-style services such as poker, table games and pokies. The law is directed at the provider: it does not explicitly make an individual player’s use of an offshore casino a criminal offence. Those are separate points, and collapsing them into “legal” or “illegal” obscures how the restriction works.
The Australian Communications and Media Authority, or ACMA, is the body charged with enforcing the Act. Its role concerns enforcement of the law; it does not turn an offshore operator into an Australian service or give that service local approval. A site’s availability to visitors, or its presentation of a familiar payment option, is not evidence that it is authorised to offer casino gambling in Australia.
There is another distinction that matters when assessing the practical risk. Australian consumer law does not protect players who use offshore casinos. That means the ordinary protections associated with dealing with an Australian business cannot be assumed to apply if a dispute arises with an offshore gambling operator. A polished website, customer support channel or recognisable brand does not replace those protections.
I have seen how payment language can dominate a page: “accepted” sounds like a complete answer, when it describes only a transaction condition. It says nothing about the legal position of the gambling service itself. The legal question comes first. The cashier comes later.
This is why descriptions of offshore sites should not be read as endorsements or as a route around Australian restrictions. A claim that a service accepts Google Pay, whether framed as a casino that allows Google Pay or as a way to pay with a mobile wallet, does not establish that the operator may lawfully provide online casino games to people in Australia. Nor does the fact that a player is not explicitly criminalised make the service lawful for the operator or protected for the customer.
The distinction is straightforward, even if promotional wording often blurs it: the Act restricts operators from providing these games to Australians, ACMA enforces that framework, and players using offshore casinos do not receive Australian consumer-law protection. A payment label cannot alter any of those boundaries.
A payment label describes how money is handled, not what a gambling service provides. Google Pay is a mobile wallet. Its presence in a payment menu, if present, would indicate a payment option; it would not identify the service’s catalogue, establish which products are available, or say anything about how those products are classified.
The distinction is easy to blur because interfaces place payment logos beside product names and promotional language. From the cashier side, though, these are separate systems. A payment method sits in the transaction flow. A game catalogue is a separate part of the service. One cannot be used as evidence for the other.
Mobile wallets, including Google Pay and Apple Pay, are accepted almost everywhere in Australia in everyday commerce. That broad familiarity does not turn Google Pay into a type of casino game, nor does it show that a particular gambling service offers any particular product. Payment acceptance and product availability are different claims, and each needs its own basis.
I have seen how a short label can do more work in a headline than it does in an actual interface. “Google Pay casino games” can sound as though the wallet defines a category of games. It does not. At most, the phrase joins a payment method to a gambling context; it cannot establish what is offered or whether the payment method is supported by that service.
The same applies to mobile services. A service being designed for a phone does not mean its games are a special Google Pay category. Device access, payment handling and the content offered are separate attributes. Conflating them makes a payment reference look like a product description.
That is the useful distinction. A wallet is a payment instrument, not a catalogue label. The fact that a mobile wallet is commonplace across Australian shops and services cannot be carried over as proof about online gambling products. Nor does a payment name, by itself, verify any game’s availability.
When I assess wording around payment and product, I keep the two claims apart. One concerns the transaction method; the other concerns the service itself. The label does not bridge that gap. No hidden category.
A payment label and a gambling service are separate things. Google Pay and Apple Pay are accepted almost everywhere in Australia, but that widespread everyday use says nothing about whether a particular gambling website accepts either wallet. It also cannot establish whether the service may lawfully offer its products to people in Australia.
That distinction matters when a page pairs Google Pay with casino games or a “bonus”. The wording may describe a payment option, an advertising claim, or a search category; it does not, by itself, confirm that a cashier offers Google Pay or that a promotion is available. A familiar logo is not a transaction record. Nor does a payment label verify the conditions attached to a claimed offer.
From the other side of the counter, labels often do more work than they appear to. “Google Pay” can attract attention because the method is familiar, while the important question—what service is being offered, and under what conditions—sits elsewhere. The payment brand does not certify the operator, its claims or the legality of its activity. It is a narrow piece of information, not a seal of approval.
The legal boundary is decisive in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from offering real-money online casino games to Australian residents. The law does not explicitly criminalise players for using offshore sites, but that is not the same as authorising those services. Australian consumer law does not protect players who use offshore casinos.
So a list described as Google Pay casinos, or a headline joining the wallet to a casino bonus, should not be read as proof of an approved or lawful service. A payment method cannot change the status of the gambling product, and a promotional label cannot make a prohibited offer permissible. Different claims require different checks. The logo proves little.
A payment option shown at the deposit stage does not, by itself, establish that the same route is available for a withdrawal. In the cashier, these are separate transaction types, and the conditions attached to each can differ. I have seen the distinction obscured by payment badges: a method may be visible when funds go in, while the withdrawal rules impose a separate eligibility test.
Amex illustrates the point. A specialist review reports that not all Australian online casinos allow winnings to be withdrawn to Amex. That is a source-specific observation, not a fixed rule for every service or a guarantee about what a cashier will show later. Payment arrangements can change, so the withdrawal terms matter in their own right.
There is also a prior-use condition: an Amex withdrawal requires an earlier deposit made with Amex. That condition links the payout route to the transaction history; it does not mean that every Amex deposit can later be returned to the card. If the cashier does not offer Amex for withdrawals, or the applicable terms exclude it, the deposit method alone cannot settle the question.
This is why a label such as “withdrawal available” needs context. It may refer to a payment method in general, rather than confirming that a particular account is eligible to receive funds through it. The distinction is operational, not cosmetic. A deposit is an incoming payment; a withdrawal is a separate instruction, subject to its own route and conditions.
I would not transfer this Amex example to Google Pay. The Amex conditions establish only that deposit and withdrawal options can diverge; they do not establish whether Google Pay is accepted for casino withdrawals, or whether any service offers a Google Pay payout route. A claim about that route needs confirmation in the relevant cashier and terms. A deposit icon is not payout evidence.
The practical reading is narrow: check the withdrawal method as a withdrawal method, and treat any Amex-specific rule as applying to Amex only. Separate routes. Separate conditions.
In Australia, tapping a card is part of ordinary payment life. Contactless credit and debit cards are accepted in almost every setting where people pay in person. Mobile wallets, including Google Pay and Apple Pay, are similarly familiar across the country. That everyday exposure shapes expectations: a payment tool that works at a shop can feel like a natural option elsewhere.
The habit is not simply loyalty to one card or app. Australians are comfortable moving between cards, mobile wallets and services connected to banks, including PayPal. The choice can depend on what a particular checkout offers, what is already set up on a device, or which account is being used. Switching between methods is ordinary behaviour, not a sign that every service supports each one.
That distinction matters when considering an Australian casino with Google Pay. A person may use the wallet routinely for contactless purchases and still find that an online service presents a different set of payment choices. The physical payment environment and an online platform’s arrangements are separate. Familiarity with the first does not establish anything about the second.
From behind a payment counter, the useful distinction is between customer comfort and merchant configuration. Comfort grows through repeated use across many everyday situations. Configuration is specific to each service. A recognisable logo, a phone with a wallet installed, or a habit of tapping to pay cannot substitute for a service showing that method as available.
So the phrase “widely accepted” needs a boundary. In Australia, it describes the broad reach of contactless cards and mobile wallets in everyday payments. It does not mean that every online checkout—or every casino using Google Pay as a label in its marketing—has the same payment options. Those are different claims.
Habit, not proof.
Google Pay is widely accepted across Australia as a mobile wallet. That describes its reach in everyday payments; it does not establish that an online casino’s cashier accepts it. The distinction is easy to miss because the same wallet name appears across many kinds of payment, while acceptance is determined separately by each service.
In payment operations, a familiar logo can create an impression of continuity: if a wallet works at shops and other services, it may seem reasonable to expect it to work wherever online payments are offered. But general availability and a particular cashier’s supported methods are different claims. One cannot stand in for the other.
So “Google Pay accepted” needs to refer to the specific transaction context, not merely to the wallet’s presence in Australia. Broad acceptance does not show that a casino offers Google Pay, that the option appears for Australian customers, or that it applies to a particular payment route. Those details belong to the service’s own payment terms and cashier.
The same boundary applies to phrases such as “Google Pay casino.” They connect a payment brand with a type of service, but the wording alone does not confirm a working payment option. Nor does the wallet’s widespread use establish anything about a casino’s payout arrangements. A payment label is not a complete account of how money moves.
The dependable conclusion is narrow: Australians can use mobile wallets such as Google Pay in many everyday settings, but that does not verify Google Pay acceptance at an online casino. Familiarity is not confirmation.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are listed as supporting Amex deposits for Australian players. Check the casino’s cashier, as some casinos do not accept Amex.
Amex deposits typically have no fee, but a casino may apply a surcharge, and currency conversion fees can apply. Withdrawal fees may also apply, depending on the casino.
Yes, Amex casino deposits are processed instantly. Withdrawals to Amex can take up to five days to clear.
Check the casino cashier for Amex as an available deposit method, then select it and enter your card details and deposit amount. A deposit may still be declined if Amex blocks payments to that website.