A broad payment-method comparison cannot confirm operator support, transaction type, or whether online casino games may lawfully be offered in Australia.
A specialist review has suggested that Visa may be accepted more widely than American Express at Australian online casinos. That is a limited comparison, not a directory of services or confirmation that any particular operator accepts Visa. The wording matters: “may be more widely accepted” describes a possible difference between payment methods, not a guarantee that a Visa card will work at a specific site.
I have seen how easily a broad payment claim can become a practical promise once it is stripped of its qualifications. A comparison can sound like a clear result while leaving the important details unresolved: which operator is being discussed, what kind of transaction is supported, and whether the service can lawfully offer online casino games to people in Australia. Those are separate questions. A general statement about Visa does not answer them.
The comparison with Amex should be read narrowly. It suggests that Visa could have broader acceptance in the market than Amex, but it does not establish how common either method is, or identify any service that accepts one or the other. It also says nothing about whether acceptance applies to a particular card, account, or transaction. Turning that qualified comparison into “Visa is accepted everywhere” would go beyond what it supports.
Visa availability and payment terms can vary, so check the casino’s current cashier options before signing up. The details below highlight what is known about each operator without assuming that Visa deposits are supported.
Neospin
Neospin is listed under a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. The supplied information does not confirm whether it accepts Visa.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus; Visa acceptance is not specified.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming under Roby Games Ltd. No Visa payment details are provided.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curacao licence, with a minimum deposit of A$20. The supplied details do not state whether Visa is accepted.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V. Visa availability is not specified in the supplied information.
SpinsUp
SpinsUp is listed under a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V. The information provided does not confirm Visa support.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi and is described as Curacao-licensed. No details confirm whether it accepts Visa.
LuckyVibe
LuckyVibe is listed under a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. The supplied information does not specify Visa payment availability.
Golden Pokies
Golden Pokies is listed as Curacao-licensed. No further operator details or Visa payment information were provided.
Bizzo Casino
Bizzo Casino is listed under a Curacao Gaming Control Board licence held by TechSolutions Group N.V. The supplied details do not state whether Visa is accepted.
Nor does a payment label establish that a service is available in the relevant sense. A site might display a card brand, or a payment method might appear in general descriptions, but neither point by itself confirms that an Australian customer can use it for online casino play. Payment capability and lawful availability are distinct. One cannot be used as proof of the other.
That distinction is especially important in Australia. A page describing a service as an Australian online casino does not, simply by using that label, establish that the service may provide real-money casino games to people located here. Equally, the possibility that Visa is accepted more broadly than Amex does not change the status of the service. The payment comparison cannot serve as a licence, approval, or assurance of lawful access.
The same caution applies to phrases such as “Visa casino” or “Visa pokies”. They can blur two ideas: a card brand and a gambling service. The card may be the subject of a payment claim; the service is a separate matter. Combining the terms does not verify that a particular operator supports Visa, that a transaction would be processed, or that the operator may provide the underlying games to Australians.
I would not read the comparison as a recommendation to seek out a Visa-accepting site. It contains no operator names and does not assess individual services. More importantly, a payment method cannot make an otherwise unavailable or prohibited service appropriate. A card is a means of payment, not evidence of the status of the business receiving it.
There is also a difference between a general market statement and a current operator-level condition. Acceptance policies can be presented at a broad level, while the actual payment options shown for a service may depend on that service’s own arrangements. The limited comparison does not pin down those arrangements or establish that they remain unchanged. It should not be stretched into a current list, a ranking, or an expectation that Visa will be offered wherever Amex is not.
The practical conclusion is modest. A specialist review has made a qualified comparison between Visa and Amex, but that comparison does not identify an Australian service that accepts Visa. It does not confirm individual payment support, and it does not establish that a service may lawfully offer online casino games to Australians. Those points should remain separate rather than being folded into a single claim about availability.
A comparison is not confirmation.
A reference to a Visa deposit describes a payment category, not a complete account of how a transaction works. The label alone does not establish that a particular service will accept a card, what information its cashier requests, or what conditions apply before a payment can be made. Those details depend on the service and its payment arrangements. A familiar card brand does not fill in the operational gaps.
That distinction matters because deposit descriptions often compress several separate decisions into one phrase. There is the question of whether a payment method is displayed, whether it is available to a particular account, whether the card issuer permits the transaction, and whether the payment is ultimately processed. These are not interchangeable. A method shown on a screen does not, by itself, settle every other part of the transaction.
I have seen how payment wording can make a process sound more settled than it is. “Visa deposit” reads as if the card, account, cashier and transaction all line up automatically. In practice, a payment label tells only part of the story. The wording is neat. The process is conditional.
A cashier is where payment options and transaction fields are presented, but its display is not a universal specification. Services can differ in the methods they show and the account conditions attached to them. A general description of paying by card cannot be treated as a precise Visa procedure: it does not establish which fields appear, what sequence follows, or what a particular cashier accepts.
The same caution applies to a stated deposit amount. A search for a small Visa deposit does not establish that a service permits that amount. Nor does the fact that a card is familiar tell anything about the minimum or maximum a particular cashier may set. Those are service-level terms, not qualities that can be inferred from the Visa name.
Fees and processing time are separate questions, too. A card brand does not, on its own, specify whether a service charges a fee or how quickly a transaction is handled. Even where a payment appears straightforward, its treatment can depend on the service and the financial institutions involved. No single rule should be assumed from the label.
I would keep these claims separate rather than bundle them into a promise: acceptance, transaction steps, amount, cost and timing each require their own terms. Without those terms, a confident-sounding description adds certainty that the payment label does not provide.
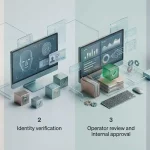
A separate part of the process is customer verification. Online casinos commonly require a Know Your Customer assessment before permitting financial transactions. KYC is an identity and account review, not a Visa feature. Its place in the process should not be confused with the mechanics of entering card details or submitting a payment.
That distinction is useful because payment descriptions often focus on the moment of deposit and omit the account checks around it. Verification can be a condition of financial activity even when the payment method itself is presented as available. In other words, a card option and an account’s readiness for transactions are different matters.
KYC is also not a fixed Visa checklist. The general requirement does not establish which documents a particular service requests, how an assessment is conducted, or how long it takes. Those specifics should not be inferred from the existence of a card payment option. Payment method and identity review sit alongside each other, but one does not explain the details of the other.
An identity and account review process, known as Know Your Customer, commonly required by online casinos before permitting financial transactions.
This is where wording can mislead without making an explicit false promise. A short phrase can make it sound as though a card is the only condition between an account and a deposit. It may not be. The verification stage is a separate gate, and the general fact that such checks are commonly required says nothing about the precise procedure for any given account.
In plain terms, “deposit by Visa” can be understood as a reference to a possible card payment route, where that route is offered. It should not be read as confirmation of a named service’s acceptance, a particular deposit amount, a fee schedule, a processing window or a set of instructions. Those conclusions need service-specific terms; they do not follow from the card brand.
Nor does the phrase establish that a transaction will be approved. A cashier option, an account check and a payment decision are distinct parts of the process. A clear description keeps them distinct instead of making a broad claim sound like a guaranteed outcome.
I prefer that narrower reading because it avoids turning a payment label into a promise. The practical meaning of any deposit description is limited to what its terms actually state. Visa identifies the card network. It does not, by itself, explain the cashier’s rules or settle what happens to a transaction.
A ranking of Visa-accepting casino sites would look precise, but precision depends on evidence that can be compared from one operator to another. A payment logo, a general statement about card support, or a claim that Visa is widely used cannot establish which particular service accepts the card. Nor does it show whether the same payment option is available to customers in Australia. Without operator-specific confirmation, ordering names from “best” to “worst” would turn an assumption into an apparent finding.
That distinction matters because card acceptance is not an attribute of Visa alone. It depends on the operator’s cashier, the payment arrangements it uses and the conditions applied to a particular account or transaction. The word “Visa” on a page may refer to a brand accepted somewhere in a business, rather than a payment route available for every customer. A ranking cannot bridge that gap by repeating the brand name with a star rating.
I have seen comparison tables make this look simpler than it is. A site is placed in a row, a payment mark is added, and the mark begins to stand in for several separate questions: whether deposits are supported, whether the support applies in Australia, and whether the same card can be used in other parts of the payment process. Those are different claims. Combining them under a single “Visa accepted” label makes the table tidy, not necessarily informative.
The word “best” adds another layer. It could mean broad card support, clear cashier terms, predictable processing or something else entirely. Unless the same criteria are checked for every named operator, the order reflects editorial judgement rather than a like-for-like comparison. A polished score does not fix that problem. It can conceal it.
The limits are sharper for searches asking for an instant Visa withdrawal casino. A claim about a card being accepted for deposits cannot, by itself, prove that withdrawals can be returned to the same card or establish how quickly they would arrive. Deposit support and withdrawal support are separate functions. Treating one as evidence for the other is a familiar comparison error.
The same caution applies to requests for a “Visa casino” or “Visa casino website.” Visa is a payment method, not a measure of an operator’s overall service. The label does not say what games are available, whether a particular cashier option works for an Australian customer, or what other conditions apply. It also does not support a meaningful ranking of sites based on quality.
I would not use a list of operator names to fill the space where comparable evidence should be. That would create an impression of endorsement and could make a payment claim seem settled when it is not. In this market, a list presented as a set of available casino choices would be especially misleading: payment branding does not establish that an operator may lawfully provide online casino games to people in Australia.
So the sensible editorial decision is not to award first place to a site, or to dress a collection of names as a shortlist. A ranking requires confirmed, comparable operator-level information and a clear definition of what is being ranked. Without those foundations, “best Visa casino sites” is a confident heading attached to an unsupported order.
No ranking. No borrowed certainty.
“Instant withdrawal” sounds like a clear service feature. In payment operations, though, the word can blur several separate stages: a casino approving a withdrawal, a payment provider processing it, and the funds appearing in a card account. A fast result at one stage does not establish how quickly the whole transaction completes.
Visa is often discussed as though a deposit card must also be a rapid route for withdrawals. That does not follow. Card payments can travel in different directions under different rules, and the label on the card alone says nothing about the time required to return funds. An instant Visa withdrawal is therefore not a benefit that can be treated as established.
The distinction matters because “instant” is an advertising word with a narrow operational meaning at best. It may refer to a request being submitted or approved, rather than money being available to use. Those are not the same event. The clock can stop in one system while the customer is still waiting in another.
Some payment-method descriptions contrast cryptocurrency with bank transfers. Bitcoin and Ethereum are described as supporting instant deposits and withdrawals with limited or no fees. Bank transfers, by contrast, may take longer and carry higher fees; that comparison has been reported in a specialist payment review, but it does not set a universal timetable.
Neither example predicts Visa performance. Cryptocurrency rails, bank networks and card systems are distinct. A speed claim attached to one method cannot be transferred to another merely because all of them appear in a casino cashier. Different route. Different processing.
From the counter side, the practical mistake is treating a payment icon as a timetable. A listed method can show what a system may accept, but it does not explain every step after a withdrawal request. Nor does a fast deposit demonstrate a fast return: incoming and outgoing transactions are separate processes.
That is why phrases such as “instant Visa withdrawal” need care. A casino may process a request promptly, but that wording alone does not tell what happens after approval or when funds become available.
The same caution applies to searches for instant withdrawals at Australian pokies or casino sites. They combine a game category, a payment brand and a speed claim, but those terms do not prove that a particular service offers the full combination. “Best” adds a ranking claim, which would require comparable, current evidence about each operator and its withdrawal process. A quick-sounding label is not a measurement.
Promotional wording can also conceal the difference between processing speed and settlement. If a withdrawal is described as immediate, the key question is what event is immediate: submission, review, release, or receipt. Without that distinction, the headline compresses a chain of steps into one attractive adjective.
So the honest description is not that Visa is slow, nor that it is instant. It is that the speed cannot be inferred from the payment method’s name, from cryptocurrency comparisons, or from bank-transfer caveats.
A precise claim needs a defined start point and end point. Otherwise “instant” describes mood, not money.
A Visa symbol answers a narrow payment question. It does not establish that an online casino may lawfully serve people in Australia. That distinction matters because payment language can make a service sound like an ordinary retail option, when the legal position concerns the operator’s offer of gambling itself.
Under the Interactive Gambling Act 2001, operators are prohibited from offering online casino games to Australian residents. The restriction covers real-money casino play; it is not a rule about which card brand appears in a cashier. From the industry side, I have seen how easily a payment badge can dominate a page and push the more important question into the background. It cannot change the legal status of the service.
The Australian Communications and Media Authority, or ACMA, administers enforcement of the Act. Its role is not to certify a Visa payment route or endorse a casino. Offshore services may be subject to blocking and enforcement action, so a site appearing online does not amount to evidence that it is an available or lawful option for Australian residents.
The Act’s position on operators should be kept separate from the position on individual players. It does not explicitly make a person criminally liable simply for using an offshore casino. That distinction is not a recommendation to use one, nor a guarantee that every consequence disappears. It describes where the law places the prohibition: on providing the service to people in Australia.
There is also a practical consumer-protection gap. Australian consumer law does not protect players using offshore casinos. If a dispute arises over an account, a payment or an unpaid balance, the usual protections available in domestic consumer dealings cannot be assumed to apply. A familiar card logo does not bridge that gap, and a payment being technically possible would not make the underlying gambling service lawful.
This is why a phrase such as “Visa casino” can be misleading when treated as a complete description. It combines a payment brand with a service, but says nothing by itself about whether that service can legally be offered in Australia, whether access is being restricted, or what protections exist if something goes wrong. The legal question comes first.
I learned to treat payment availability and market availability as separate checks. In a prohibited market, the first cannot settle the second. A card transaction is not a licence, an approval or a consumer safeguard. No shortcut there.
The word “Visa” can appear beside a casino-game term because two different subjects have been pushed into one phrase: what a game is, and how a payment might be made. That wording does not establish a Visa-branded game, a special version of a game, or access to any particular game through a card. It describes neither a game feature nor a confirmed service.
I have seen this distinction matter in the way payment pages are organised. Game information concerns the content and rules of a game; payment information concerns whether a transaction method is supported. Putting both ideas together in a heading can make the relationship look stronger than it is. A reference to Visa beside a game name is not evidence that the game is linked to Visa, or that a payment through Visa is available.
The same applies to phrases about casino payment options. A method’s name appearing in general copy does not confirm that an operator supports it, that an issuer would authorise a transaction, or that the service itself may be provided. Those are separate questions. The wording alone settles none of them.
There is also a limit to what can be inferred from comparisons with other cards. A specialist review has reported that some online casinos do not accept American Express. That is a time-sensitive observation about Amex, not a rule for the wider market. It cannot be turned into a claim that Visa is accepted wherever Amex is not. Different card networks, operators and issuers may have different conditions.
“Visa-compatible” can sound like a clean technical label. In practice, it may conceal several separate decisions: the operator’s payment settings, the card issuer’s controls and the nature of the service being offered. A general statement about one layer does not settle the others. Nor does a game catalogue demonstrate anything about card support.
This is why a phrase joining Visa and games should be read narrowly. It may signal that someone is asking about payment alongside casino content, but it does not verify a particular game, a Visa-linked feature or a lawful real-money service for Australians. I do not treat the card as part of the game itself, and I do not treat game descriptions as proof of payment availability.
Different categories. No shortcut.
In Australia, contactless credit and debit cards are accepted almost everywhere. Mobile wallets, including Google Pay and Apple Pay, are similarly widespread. That describes the everyday retail environment, not the payment options of a particular online service.
I have seen how a familiar payment habit can shape expectations: a card works at a shop, so its holder assumes it will work wherever a card number can be entered. But acceptance is decided service by service. A cashier’s available methods depend on the operator’s setup and the transaction being attempted; broad use of cards in the country does not settle what appears there.
The same distinction applies to mobile payments. Australians are comfortable moving among physical cards, phone wallets and bank-linked services such as PayPal. That flexibility is a consumer habit, not evidence that each online business supports every option—or that Visa is available at an Australian casino. Habit is not confirmation.
There is also a difference between a payment rail being familiar and a payment being accepted for a specific purpose. A method’s presence in daily commerce cannot establish that a gambling service offers it, that a particular card will pass, or that a payment route is available to Australian customers. Those are separate conditions.
The practical point is narrow. Australia’s high acceptance of contactless cards and mobile wallets explains why card-based payment searches feel ordinary. It does not identify an online casino that accepts Visa, or confirm that a named service has Visa in its cashier. Everyday acceptance ends at the edge of the individual service.
A card accepted for deposits is not automatically available for withdrawals. Those are separate cashier functions, and an operator may apply different conditions to money going out than to money coming in. That distinction matters when assessing whether a casino offers Visa withdrawals: Visa deposit support alone does not establish that winnings can be returned to the same card.
The available withdrawal details concern Amex, not Visa. A specialist review reports that an Amex withdrawal may be restricted to customers who previously deposited using Amex. It also says that some Australian online casinos do not offer withdrawals to that card. These conditions illustrate why payment-method labels can be incomplete: the card may appear as a way to fund an account without serving as an available payout route.
That does not establish equivalent rules for Visa. Amex conditions cannot be transferred to another card network, and a casino with Visa withdrawal support cannot be identified simply because it accepts Visa deposits. The reverse assumption is no safer: a missing Visa payout option does not tell anything about the operator’s Amex arrangements.
I have seen payment descriptions compress these distinctions into a single word such as “supported”. At the counter, that wording can mean only that a method is available at one point in the transaction, not that it works in both directions. The cashier’s withdrawal choices are the relevant detail for a payout, alongside the operator’s stated conditions. A logo or deposit option is not enough.
For Visa, then, the practical question is specifically whether the card is listed for withdrawals, not merely whether it appears among deposit methods. The Amex example shows that prior use and payout eligibility can be linked, while also showing that withdrawal support can differ between casinos. It does not show that Visa has the same prerequisite, that every Visa deposit can be returned to the card, or that any particular online casino offers this route.
The distinction is narrow but important. Deposit support and withdrawal support are separate claims. One does not prove the other.
A Visa logo can make a payment option look settled. It is not. A card brand, an operator’s cashier and the rules governing a service are separate parts of the transaction, and one does not confirm the others.
I treat “Visa casino payment method” as a claim that needs specific terms behind it, not as a general promise that a card will work. Visa-specific payment steps, charges and limits cannot be stated reliably without terms for the particular service and transaction. The same applies to claims that paying by Visa is free, immediate or available to every account. Those are not details that can be inferred from the card name.
That distinction matters because payment wording often compresses several conditions into one neat label. A cashier may display a method, while the issuer may apply its own rules; an operator may set separate transaction conditions. None of those possibilities establishes what would happen in a particular case. No universal Visa process follows from the phrase “pay by Visa”.
Nor does the phrase “play casino with Visa” settle whether an online casino service may lawfully be offered in Australia. Payment capability is not a substitute for lawful availability. I have seen those ideas blurred together in promotional copy; the wording makes access sound simpler than the underlying position.
So a broad claim that a casino accepts Visa is not enough to describe the payment arrangement. It does not, on its own, establish the applicable steps, fees or limits, and it should not be read as assurance that a service is available to Australians. Separate claims need separate support. The card name is only one piece.
A Visa payment method does not, by itself, make a promotion available. A card and a bonus are separate parts of a transaction: an advertised offer may have its own eligibility conditions, while the cashier determines which payment methods are accepted. Treating a Visa deposit as an automatic route to a bonus turns an assumption into a sales claim.
I have seen promotional wording do its work through implication rather than an explicit promise. “Deposit bonus” can sound as though the payment method unlocks the offer, even when the terms may not say that. The distinction matters: a Visa-branded bonus should not be presented as a benefit unless its conditions actually establish that connection.
There is also a wider boundary around gambling promotions in Australia. Advertising real-money online casino services to Australian audiences is prohibited, and promotions must not be used to promote offshore casino services from within the country. The restrictions on inducements and gambling advertising include a time window: advertising rules are especially strict between 5:00 am and 8:30 pm. A payment-card theme does not create an exception.
That makes neutral wording important. Describing an offer as a reason to deposit would move from explaining payment terminology into promotion. The same applies to suggesting that a card can secure extra play or improve the value of a gambling transaction. Without established terms, those claims are not analysis; they are inducements by implication.
The practical distinction is simple: Visa identifies a payment network, not a bonus entitlement. No special status.
Amex deposit and withdrawal limits are set by each casino and can vary. Check the limits shown in that casino’s cashier or payment terms.
Check the payment methods displayed in the casino’s cashier. Some casinos accept Amex, but a payment option being listed does not guarantee that a particular transaction will be processed.
Your card issuer may be blocking gambling payments to that website. Australian banks can block gambling-related Amex transactions at the issuer level.
Yes, some Australian online casinos accept Amex deposits, and those deposits are typically processed instantly. Acceptance is not universal, and an issuer may still block a transaction.
Amex deposits typically have no fee, but a casino may charge a surcharge, and a currency conversion fee may apply. Withdrawal fees can also apply, depending on the casino.
Amex deposits typically have no fee, though a casino may add a surcharge. Withdrawals may incur fees, and currency conversion fees may apply.
Some casinos allow Amex withdrawals, but not all do, and they may charge a fee. You generally need to have made a previous deposit with Amex to use it for a withdrawal.