PayID, conventional bank wires and bank-authorised services use different routes, while Australian law applies regardless of payment label.
“Bank transfer” can describe several different payment routes, not one uniform method. In discussions of online pokies, it may mean a payment service linked to a bank account, a conventional transfer between accounts, or a bank-authorised payment method such as POLi. The distinction matters: these routes differ in how they are initiated and in whether the same channel can be used to return funds.
There is also a legal point that changes the context in Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people in Australia is illegal for operators. Payment labels do not alter that position. A service being described as an Australian bank transfer, or a casino claiming to accept one, does not make the underlying offer lawful.
PayID is a payment service operating through the New Payments Platform (NPP). It uses an identifier, such as a mobile number or email address, to route a payment between bank accounts. A conventional bank wire, by contrast, requires bank-account details and is a separate transfer route. Both involve banks, but that shared feature does not make them interchangeable.
For Australian players considering instant bank transfers in 2026, payment options and processing details can shape which casino is worth investigating. Use this list as a starting point, and check each operator’s current banking terms before depositing.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists PayID payouts at 1–3 business days and crypto payouts under one hour. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming, with Roby Games Ltd as the operator.
Uptown Pokies
Uptown Pokies is listed as operating under a Curacao licence since 2017. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as Curacao-licensed and operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams lists a Curacao licence and a A$20 minimum deposit for POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence; no further operator details are provided here.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence, with TechSolutions Group N.V. as the operator.
POLi is another bank-linked option, but it should be understood primarily as a deposit method. Its presence in a payment menu is not evidence that it can also handle withdrawals. In practice, payment pages can place distinct services under a broad “banking” heading, which makes them look more alike than they are. The label describes a category; it does not tell the whole story.
From the operator side, payment methods are often grouped according to how they connect to an account or payment processor. That can be convenient for a menu, but it is not a reliable guide to the route a transaction takes. “Bank transfer” may refer to a direct transfer, while another option may send the player into a bank’s own authorisation flow. Different mechanics. Different outcomes.
Visa and Mastercard are card networks, not bank-transfer rails, even when a card draws funds from a bank account. Specialist reviews describe these cards as widely accepted for deposits in gambling-payment contexts, but say that withdrawals back to a card can be slower or unavailable depending on the processor. That distinction is useful when comparing payment categories: an account-funded card payment is still a card transaction.
E-wallets such as Neteller and Skrill form another category. They hold or route funds through an e-wallet account rather than operating as a direct transfer between the player’s bank account and the merchant. Their presence alongside bank options in a cashier does not make them bank transfers. Nor does a menu listing establish that every method is available for both directions of payment.
This is where broad claims about “online casinos with bank transfer” become imprecise. The phrase might refer to PayID, a bank wire, POLi, or a bank-funded card, each with different handling. A payment page can make these distinctions visible, but the category name alone cannot.
In Australia, the more important distinction is between how a payment moves and what it is paying for. The Interactive Gambling Act treats online casino-style games, including pokies, as prohibited interactive gambling services when provided to customers in Australia. A bank transfer does not change the legal character of the service, and a payment processor’s involvement should not be read as approval of an operator.
That is why payment comparisons need careful wording. A discussion of PayID or bank wires can explain the mechanics of payment infrastructure without endorsing or advertising an offshore casino. The same caution applies to terms such as “instant,” “secure,” or “accepted”: they describe claims or transaction features, not whether an Australian-facing casino service is lawful.
For a clear comparison, separate the method into three questions: whether it is a bank transfer, card, or e-wallet; whether it is described as a deposit route or also as a withdrawal route; and whether the casino’s offer is lawful for people in Australia. Those are different issues, often blurred together in payment menus. Keep them separate.
In Australia, real-money online casino games are prohibited services when offered to people in the country. The mechanics below describe how a PayID deposit is processed; they are not an endorsement of using an online casino.
Where a payment screen offers PayID, the deposit flow is generally short: select PayID, enter the amount, then confirm the transfer in the banking app. The casino’s page supplies the payment details, while the bank app is where the payment is authorised. The two steps happen in separate places. That distinction matters: entering a deposit amount on the casino screen does not itself move money.
Before confirming, the recipient details need to be checked against what the casino displayed. A mismatch is not a cosmetic issue; the transfer may go somewhere other than the intended recipient. The payment reference deserves the same care. Some operators use the player ID or account username in that field to match an incoming payment with the right casino account. When the identifier is absent or incorrect, the payment may not be credited automatically. It can sit pending until support staff manually identify it.
That is the point where an apparently simple bank transfer becomes an administrative task. A bank can show that the payment was sent, while the casino account still shows no deposit, because the operator’s records have not matched the transaction to the player. A receipt may help explain what happened, but it does not replace the reference the operator requires. The cleanest transaction is the one whose recipient and reference both match the payment instructions before authorisation.
The minimum shown on a casino deposit page is set by the operator, not by a universal PayID rule. PayID deposits commonly begin in the AUD 10–20 range, while some bank-transfer options accept AUD 5. The amount therefore needs to be read from the payment screen for that particular account. A figure used by one site does not establish the minimum at another.
Once the amount is entered, the banking app presents the transfer for confirmation. The account holder confirms it through the bank, then the casino waits for the payment notification and applies its own account-matching process. A payment can reach the recipient while the casino balance updates later, particularly if the reference is missing or does not identify the account clearly. “Instant” describes the transfer experience, not necessarily the entire sequence from pressing confirm to seeing a casino balance change.
I have seen the reference treated as a minor form field, when operationally it is the transaction’s label. The amount says how much moved; the reference helps explain whose deposit it is. A correct amount with an unusable reference can still create a reconciliation problem. Small detail. Real consequence.
A pending deposit does not automatically mean the bank rejected the payment. The issue may be that the casino cannot associate the incoming funds with a player record without the requested identifier. In that case, manual support processing may be needed. The timing and handling then depend on the operator’s process, so a bank confirmation alone should not be mistaken for proof that the casino has credited the balance.
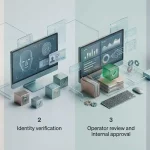
PayID Deposit Process
Selection
Select PayID on the casino payment screen and enter the deposit amount.
Authorization
Open your banking app and confirm the transfer to the provided payment details.
Verification
Check that the recipient details and the required payment reference match the casino's instructions before finalizing.
The useful records are the transaction confirmation and the exact reference used. They make it possible to describe the payment accurately if support has to investigate. Repeating the transfer to force an update can create a second transaction rather than resolve the first one; the original payment’s status should be established before any further action.
This is also why the deposit screen and banking app should be treated as one continuous process. The amount is chosen on the casino side, the transfer is authorised through the bank, and the reference links the result back to the account. A break in that chain—especially at the reference field—can leave money sent but not yet credited.
A bank-transfer option says something about how a payment can be sent; it says nothing reliable about whether the operator is lawful, dependable or suitable. That distinction matters in Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people physically in Australia is illegal. Offshore access may also be actively blocked. A foreign licence does not make an online casino lawful to offer its service here.
I would treat a payment logo as a narrow operational claim, not an endorsement. A site can describe itself as the best online casino accepting bank transfer, but the wording does not establish that Australians can lawfully use it or that a payout will be handled well. The same applies to mobile casinos promoting instant bank transfer: a payment method and an attractive label are not evidence of lawful availability.
A licence claim needs context: which authority issued it, which company holds it, and whether the stated permission covers the service being offered. A foreign licence is not an Australian authorisation. In this market, presenting a licence check as a way to find a “regulated” real-money online casino would give the wrong impression. The legal restriction applies to the operator providing the prohibited service, not just to how the account is funded.
I separate two questions that are often blended together in promotional copy: whether a company has a licence somewhere, and whether it may offer online casino games to people in Australia. The first does not answer the second. A polished payment page cannot bridge that gap.
A payout record is useful only when it has enough detail to assess. A bare claim that withdrawals are fast does not show when the clock starts, whether the account had completed checks, or whether the figure describes review time or money arriving at the bank. I look for clear explanations of how a payout is handled and whether the operator’s stated process matches its own terms.
Independent player reports can add context, but they are not a verified ledger. Complaints may describe unusual cases; positive comments may omit delays or conditions. The useful signal is consistency and detail, not a high volume of praise. A “best” label is marketing unless its comparison criteria and evidence are visible. No ranking changes the Australian legal position.
Operators may require a withdrawal to go back through the deposit method where that is possible. A specialist review describes this as an operator-dependent condition, not a universal rule. It can affect the practical route for receiving funds, so the payment terms should explain what happens if the original method cannot be used. The deposit option alone does not establish that the same route will be available for a withdrawal.
KYC verification is another point to check before any withdrawal request. Specialist reviews report that identity checks are commonly required before a first payout, and that completing them beforehand can reduce paperwork delays. That is a process observation, not a promise of approval or timing. The separate withdrawal procedure belongs to the operator’s terms.
From the other side of the counter, the distinction is plain: a payment method can make a deposit look straightforward while leaving the important conditions elsewhere—in the account rules, identity checks and payout clauses. I would not use bank-transfer acceptance as a proxy for trustworthiness. Payment is not permission.
When a payment is described as “instant” in an Australian casino context, the term generally points to PayID, not a conventional bank wire. The difference is the payment route. PayID is part of Australia’s real-time payment network, the New Payments Platform (NPP), built by the banking system. It lets people with an Australian bank account send or receive money using an identifier such as a mobile number or email address.
A bank wire works differently. Instead of using a PayID identifier, the sender needs the recipient’s banking details. For a casino wire deposit, those details can include the business name, bank account number and bank name; SWIFT, BIC or IBAN codes may also be required. The transfer then moves through the banking process rather than the NPP’s real-time route.
That distinction matters because “bank transfer” is a broad label, not a reliable timing promise. PayID can move funds in real time, while a wire deposit may take as long as seven business days to show in a casino account. A page that uses “instant bank transfer” without naming PayID can blur two materially different methods. I would treat the payment rail, not the headline, as the useful detail.
The word “instant” also needs a narrow reading. It describes the transfer network’s capability; it does not, by itself, establish how a casino handles the payment once it arrives. The casino’s own account processing is a separate matter. So “instant” should not be taken to mean that every part of a transaction—from sending funds to seeing them reflected in an account—happens at the same speed.
A wire’s slower arrival does not make it a failed transfer. It is simply a different mechanism, with more banking details involved and a longer possible journey before the casino account reflects the payment. PayID’s identifier-based route is designed for real-time payments; a conventional wire relies on the recipient’s account information. Different rails. Different clocks.
The distinction is useful beyond casino terminology. A payment page may group PayID and bank wire under “bank transfer,” even though they do not share the same infrastructure or expected arrival time. Checking which method is actually offered is more informative than relying on a general label. If the option is PayID, it uses the NPP; if it asks for the recipient’s business and bank-account details, it is a wire-style transfer.
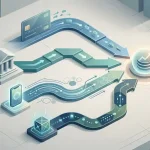
Uses the New Payments Platform (NPP) for real-time transfers via an identifier like email or phone.
Requires full bank-account details and may take up to seven business days to be credited.
There is also a legal boundary that promotional descriptions can obscure. Under Australia’s Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including pokies, to people physically located in Australia. Explaining payment terminology is not an endorsement of using an offshore casino service. The payment method does not change the legal status of the gambling service.
In short, “instant” usually signals PayID and its connection to the NPP, whereas a bank wire is a separate, account-detail-based route that can take substantially longer to appear. The label is not the mechanism.
A bank-transfer withdrawal has two separate gates: the casino must approve the request, then the payment has to reach the bank account. The first is an operator process; the second depends on the payment route. Treating both as one “payout time” makes a delay harder to diagnose.
For a bank transfer withdrawal, the account holder supplies bank details and completes KYC verification with supporting documents. The details need to match the account being used for the payout. A mismatch can bring the request back for clarification or additional checks, rather than sending it straight to the payment stage.
KYC verification is commonly required before a first withdrawal. Completing it before requesting a cash-out can reduce the chance that the payout pauses while documents are requested and reviewed. In practice, the review is not a formality detached from payment: the operator needs to establish who owns the account and whether the withdrawal can be released to it. Paperwork first. Money later.
Once the casino approves a withdrawal, the payment method matters. A specialist review of casino payment timelines describes bank transfers and card withdrawals as taking one to five business days to arrive after approval. The same review gives a shorter possible window for PayID and some e-wallet or cryptocurrency withdrawals: minutes to hours. Those are reported timeframes, not a promise for every operator or transaction.
That distinction matters when comparing a casino with bank transfer payout options. A transfer may be a suitable route for moving winnings to a bank account, but it should not be read as an instant cash-out merely because the deposit method was fast. Deposits and withdrawals are separate processes, and casino approval can add time before any payment rail begins moving funds.
There is also a practical reason to check the available withdrawal methods before relying on one. Operators may require a withdrawal to return through the deposit method where that is possible, while some casinos do not support PayID cash-outs. A backup method can therefore matter even when PayID was used to fund the account. The casino’s cashier terms should identify which routes are available and what account details are required.
A bank transfer can involve an additional step outside the casino. Players may be asked to visit a bank in person to confirm identity and make a transaction. That does not apply to every withdrawal, but it is worth allowing for when the operator or bank requests it. Keeping the casino account name and bank account details consistent also helps avoid an avoidable pause.
The useful comparison is not simply “fast” against “slow”. It is casino review time versus delivery time after approval. A bank transfer may take longer to arrive than some alternatives once released, while a pending verification check can hold up any method. Clear bank details, completed KYC verification and a withdrawal route the casino supports are the parts of the process that can be checked before requesting payment.
“Fast” can describe two different stages: how long a casino takes to review and approve a withdrawal, and how long the payment takes to reach a bank account after release. Combining them into one headline time obscures where a delay is occurring.
A specialist review reports that top-rated PayID casinos may accept withdrawal requests within 0–6 hours of submission. For verified accounts, the same kind of review puts the review-and-approval window at 2–6 hours. These are reported performance windows, not a promise that every request will be handled within them. Account checks or an operator’s own processing queue can change the result.
That distinction matters because a request being accepted is not the same as money being sent. A status such as “received” or “processing” indicates that the casino has the request; it does not establish that the payment network has begun moving funds. From the counter, this is where “instant” can become misleading. The clock may not have reached the bank yet.
PayID uses Australia’s New Payments Platform, which settles transfers in real time. Once a casino releases a PayID payment, the network can move it within minutes. A conventional bank transfer follows a different route and may take longer to appear. Specialist payment reviews describe bank-transfer and card withdrawals as taking one to five business days after casino approval; the payment method and processing arrangements matter.
So a quick PayID network cannot make an unreviewed withdrawal instant. If the request is waiting for casino approval, the payment rail has nothing to deliver. Conversely, once a payment has been released, a delay may lie with the bank or transfer route rather than the casino. Two clocks. Two responsible parties.
The same separation helps assess claims about a fast bank-transfer payout. A clear claim identifies the stage it measures: request acceptance, review and approval, or funds arriving in the bank account. A single “fast payout” label does not explain which event starts or stops the clock. Nor does a review window establish what an individual account will experience.
In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. Payment descriptions do not change that legal position. The timing details above explain how review and transfer stages are commonly distinguished in specialist coverage; they are not an endorsement of using an offshore casino.
When a delay occurs, the useful distinction is not simply “fast” or “slow.” It is whether the request is still being assessed or has been released for payment. That is the mechanics behind the label.
In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people in the country. Bonus wording does not change that legal position. The details below describe how bonus terms and payment records can interact; they are not an invitation to use an offshore casino.
A bonus-linked deposit has two separate records: the payment and the offer attached to the account. With PayID, an operator may rely on the payment reference to identify whose deposit has arrived. If its instructions require a player ID or username and that detail is missing, the deposit can remain pending until support matches it manually. That can leave the bonus uncredited or its status unclear while the payment is investigated. The reference is operational, not decorative.
I have seen “instant” used as if it described the whole transaction. It may describe the transfer arriving, but it does not settle whether a promotion applies, whether its terms have been met or whether a later cash-out qualifies. A no-deposit bonus label is similarly incomplete: the conditions, rather than the headline, determine what can be withdrawn. There is no shortcut. Read the rules.
The important conditions are usually grouped around:
These clauses work together. A game can be available on the site yet contribute little or nothing towards wagering; a bet can count as play while still breaching a promotion’s maximum-stake rule. The practical question is not simply whether a bonus appears in the account, but which actions preserve eligibility and what the rules say happens if a condition is missed.
Payment references matter before any promotion is considered. A correct reference can help connect a PayID deposit to the account; a missing or mistyped identifier can require manual processing. That administrative delay may complicate the timing of a bonus, but it does not alter the bonus terms. Keep the payment record and the offer terms distinct. One proves where money was sent; the other defines the conditions attached to it.
“Direct bank transfer” can describe money moving from a bank account through a payment service, rather than through a card network or e-wallet. In the Australian casino context, PayID is one such route: it uses an identifier, such as a mobile number or email address, and payments are settled in real time through the New Payments Platform (NPP).
That describes the movement of funds, not the legality of the service receiving them. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including pokies, to people physically located in Australia. A payment route does not change that rule.
The distinction between a transfer and a casino credit is important. The NPP can settle a PayID payment in real time, but that only concerns the banking side. The operator’s system must still recognise and apply the transaction to an account. A payment that has settled at the bank is not, by itself, proof that an account has been credited.
“Instant” is therefore a narrow description. PayID transfers can clear within minutes once released, while any separate processing by the receiving service remains outside the payment network. From the counter side, these are two different events: the bank confirms a transfer; the recipient’s system records it. Confusing them is where expectations go wrong.
A conventional bank transfer also moves money directly between accounts, but the label alone does not identify the rail or establish when funds will appear in a recipient’s system. PayID names a specific service operating through the NPP. The underlying mechanism is clear; the account treatment is separate.
No shortcut.
“Top” is a label, not a payment feature. In a specialist review, the label may refer to how quickly a casino acknowledges a withdrawal request, how long it takes to assess it, or whether the account has already passed KYC verification. Those are different stages, and combining them into one speed claim makes the result look clearer than it is.
One specialist review reports that top-rated PayID casinos accept withdrawal requests within 0–6 hours. The same type of review describes requests from verified accounts as being reviewed and approved within 2–6 hours. These are reported assessment windows, not a promise that every request will follow them or that funds will arrive at the same point. “Accepted” can mean the request has entered the queue; “approved” means the casino has completed its review.
I would treat a performance claim as meaningful only when it identifies the stage being timed and the account conditions attached to it. A figure for verified accounts cannot be assumed to cover an account still undergoing checks. Nor does a stated review window establish the time taken after approval.
There is a more basic limit in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in the country. A “top” label does not alter that legal position or establish that a service is authorised locally. It describes a review’s assessment, not a regulatory status.
Keep the wording in its lane. Request handling, casino approval and payment delivery are separate measures. A headline that blurs them is not a useful comparison.
PayID limits are controlled by the bank account sending the money, not by a single ceiling that applies across Australia. Banks set their own transaction and daily caps, so the amount available can differ between customers and institutions. Most major Australian banks permit PayID payments of AUD 1,000 to AUD 5,000 per transaction, with daily limits from AUD 10,000 to AUD 20,000. A bank may set a lower personal limit, so its app or account terms are the practical reference point.
A conventional bank transfer does not necessarily follow PayID’s bank-set limits. Its possible maximum can be broader: a specialist review describes bank transfers as having limits that may reach tens of thousands of dollars. That is not a universal allowance. The bank, transfer type and receiving account can all affect what is permitted.
The payment reference is a separate issue from the limit. It identifies where a deposit should be credited. If an operator requires a player ID or username, leaving it out can mean the payment is not matched automatically and remains pending while support handles it manually. A unique reference, entered exactly as instructed, reduces that risk. The recipient name should also be checked against the payment details before confirming anything; a correct reference cannot fix a payment sent to the wrong recipient.
In practice, PayID versus bank transfer is not just a choice between two labels. The sending bank’s cap determines what can leave the account, while the recipient’s instructions determine whether the payment can be identified on arrival. Both checks matter. No shortcut.
These mechanics do not make real-money online casino services lawful for operators to provide to people in Australia: the Interactive Gambling Act 2001 prohibits that service.
Some casinos process withdrawals by PayID, but availability depends on the operator. PayID itself can settle payments in real time; casino review and approval can take longer.
PayID casino deposits commonly start at AUD 10–20, and some accept as little as AUD 5. The maximum is set by the player's bank; most major Australian banks allow AUD 1,000–5,000 per transaction, with daily limits of AUD 10,000–20,000.
Some casinos allow PayID withdrawals, typically after internal review and identity checks. PayID payments can settle quickly once released, but the casino's approval process may take longer.
PayID casino deposits commonly start at AUD 10–20, with some accepting as little as AUD 5.