The Australian framework distinguishes operational safeguards from whether an online casino may lawfully offer games to residents.
“Safe” has two different meanings in the Australian casino context. It can describe how a website handles an account or transaction, but it can also imply that the service is lawful to offer in Australia. Those are not interchangeable claims. A site’s reassuring language does not change the legal position.
The starting point is the Interactive Gambling Act 2001. It prohibits domestic operators from offering online casino games to Australian residents. Put plainly, an online casino cannot become a lawful Australian service merely by presenting itself as a local business or by describing its offer as safe. The law concerns the provision of the service, not the strength of its branding.
That distinction matters because “safe online casino Australia 2026” can sound like a request for a simple quality label. There is no single label that settles the question. A claim about a secure account or a smooth transaction is not proof that the operator is permitted to provide casino games to people in Australia. Legal status has to be considered separately from any operational claim.
Choosing an online casino for Australia in 2026 calls for checking the details available about its licensing and practical terms. Use these short profiles as a starting point, and verify the current terms before signing up.
Neospin
Neospin is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts as taking under an hour and PayID payouts as taking 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed with a Curacao eGaming licence held by Roby Games Ltd.
Uptown Pokies
Uptown Pokies is listed as operating under a Curacao licence since 2017. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed with a Curacao licence and is operated by Dama N.V.
SpinsUp
SpinsUp is listed with a Curacao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams is listed with a Curacao licence. Its minimum deposit is A$20 when using POLi.
LuckyVibe
LuckyVibe is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed with a Curacao licence.
Bizzo Casino
Bizzo Casino is listed with a Curacao Gaming Control Board licence held by TechSolutions Group N.V.
The Act’s position on players is different. It does not explicitly criminalise an individual for using an offshore casino site. That is a narrow statement about the player’s criminal liability; it is not approval of the service, a declaration that an offshore operator may lawfully target Australians, or a promise that a player will have a reliable remedy if something goes wrong. The operator’s offer and the individual’s position are not the same legal question.
I have seen how easily those questions get blurred in commercial wording. “Available to Australian players” describes access as the site presents it. It does not establish that the service is lawful under Australian law. Likewise, an offshore licence, a familiar payment option or an Australian-facing page cannot be treated as an Australian authorisation. The wording may make a service feel ordinary. It does not alter the rule.
This is why calling a site a “safe casino” without saying what safe means can mislead. If the claim refers to technical handling, it says nothing by itself about whether the operator can offer online casino games here. If it refers to legality, the claim needs to fit the Australian framework rather than rely on how confidently the operator describes its status. A reassuring badge is not a legal determination.
The practical baseline is therefore less comfortable than the phrase suggests: the law prohibits the offer of online casino games to Australians, while it does not explicitly make an individual player’s use of an offshore site a criminal offence. Neither point turns the other into its opposite. The absence of an explicit player offence does not make the operator’s service lawful; the prohibition on the operator does not mean the law explicitly criminalises the player.
In my experience, the most useful correction is to separate “can be accessed” from “can lawfully be offered.” A website may be visible or may accept an account registration, but access is not proof of permission. Nor does a claim of safety remove the legal distinction between an operator serving Australian customers and an individual using an offshore site.
So, when “safe” appears beside an online casino aimed at Australians, it should not be read as a legal status. The relevant baseline is the Act’s restriction on operators and its different treatment of individual players. That is the line the wording often leaves out. Short version: access is not authorisation.
PayID is a payment route, not a safety certificate. Its presence on a casino payment page can tell something about how a transfer might be made; it cannot establish that an operator is lawful in Australia, that the service is trustworthy, or that money sent will be returned when requested.
The distinction matters because payment screens often place the method beside words such as “instant” or “secure”. “Instant” describes, at most, a transfer’s movement after release. It says nothing about the status of the gambling service receiving it. Under Australian law, operators cannot provide real-money online casino games to people in Australia. A fast payment does not change that position.
PayID transfers commonly use the New Payments Platform. A specialist review says they can clear quickly, sometimes within minutes after release. That timing is not a promise for every transaction. The account receiving the funds, payment processing and any approval step can affect when a transfer is actually released or credited.
That distinction between approval and transfer time is easy to miss. A payment may appear to be “pending” before it has been released; the time it then takes to move is a separate part of the process. A specialist review describes PayID and some e-wallets as potentially quick after approval, while bank transfers and cards may take several business days. Those are reported processing patterns, not a dependable timetable for a particular service.
From the operations side, I would never read a fast confirmation as proof that the whole transaction is safe. A transfer notification confirms a payment event. It does not validate the operator’s claims, settle a dispute, or guarantee that a balance shown on a screen can be withdrawn. Speed is useful information. It is not protection.
PayID is designed to identify a payment recipient through details associated with a bank account. That function belongs to the payment itself. It is separate from the question of whether the recipient is authorised to offer online casino games to Australians.
A payment method can work as described while the service behind it remains unlawful or unreliable. This is why “PayID accepted” should not be treated as equivalent to “safe casino”. Nor does a familiar bank-transfer process make an offshore gambling service licensed in Australia. The payment rail and the operator’s legal position are different things.
There is also a practical difference between a deposit being accepted and a customer having meaningful recourse if a later dispute arises. A successful transfer does not decide what happens if an account is questioned, a payment is not credited, or a withdrawal is refused. Those outcomes depend on the service and the protections available; the payment method alone cannot resolve them.
A “no deposit” offer may sound as though it removes payment risk, but the phrase does not establish that the casino is lawful or that its conditions are reliable. Where a service invites Australians to play online casino games for real money, a promotion or payment option does not alter the legal position. A bonus label is not authorisation.
I treat payment branding as a narrow operational detail, not an endorsement. The useful question is what the method actually confirms: whether a transfer was initiated, released or credited. It cannot confirm the broader claims often placed around it. No shortcut there.
For Australians, the core issue is therefore not whether PayID can move funds quickly. It is whether the gambling service is permitted to offer those games in the first place, and what protection exists if something goes wrong. PayID can answer neither question. A rapid transfer is still just a transfer.
“Real money” describes what is at stake in a casino game: funds are deposited, wagers are made, and a player may expect a balance to be paid out. It does not describe the legal status of the service. I have seen those two ideas blurred in reviews, where a smooth account experience is treated as evidence that a casino is safe for Australian players. It is not.
The legal distinction is between the person using a service and the operator supplying it. Under the Interactive Gambling Act 2001, an operator cannot offer online casino games to Australian residents. The Act does not explicitly make an individual player’s use of an offshore casino site a criminal offence. Those statements can both be true at once. The absence of an express player offence does not turn the operator’s offer into a lawful one.
That difference matters when a service accepts real-money play while operating from offshore. A site may describe itself as available to Australians, show a balance in Australian dollars or present an offshore licence as reassurance. None of those details changes the rule on providing online casino games to people in Australia. A licence issued elsewhere is not an Australian authorisation.
The practical mistake is to read “players are not criminalised” as “players are protected.” Those are separate questions. The first concerns whether the law expressly penalises an individual for playing. The second concerns what happens if a service disputes a balance, refuses a withdrawal or closes an account. Unlicensed gambling services lack consumer protections, and Australian laws may not assist if winnings are withheld. No explicit player offence is not a safety net.
This is why searches for a safe online casino for real money can lead to the wrong test. A site can have polished terms, customer support and a functioning cashier while still offering a service that it cannot lawfully provide to Australian residents. Operational competence is not the same as legal permission, and neither one by itself guarantees a player can enforce a claim.
I learned to separate the counter experience from the underlying position. From the service’s side, accepting a deposit may look routine: the account displays funds and play can begin. From the player’s side, the important issue is what legal protections apply if the relationship breaks down. A reassuring interface can make a transaction feel ordinary. It does not settle that issue.
The same caution applies to mobile real-money play. The screen size, app-like layout or ease of access says nothing about whether the operator may offer casino games in Australia. Nor does a review that calls a site “safe” establish that Australian residents have a reliable route to recover money in a dispute. The word needs a precise meaning. Safe from what, and protected by whom?
A careful account of the position does not accuse individual players of committing an offence where the Act does not explicitly create one. It also does not imply that offshore services are approved, or that the player has the same protections available in a regulated local market. Both claims would misstate the situation.
My conclusion is narrower, but more useful: a player’s legal position and an operator’s legal position are not interchangeable. The fact that one is not explicitly criminalised does not cure the other. Real money makes that distinction tangible. No dependable shortcut.
“Safe” is often doing several jobs in the same sentence. It may refer to an encrypted connection, a site’s account controls, or the legal standing of the service. Those are separate questions. A polished page can make them look like one.
I start with the specific claim, not the adjective. If a casino says it protects payment details, the relevant technical signal is whether it uses SSL encryption to safeguard transactions and sensitive information. Encryption helps protect information as it travels between a device and the service. It does not establish who operates the site, what happens to information after it arrives, or whether the service is authorised to offer online casino games in Australia.
That distinction is easy to lose in a row of reassuring badges. A padlock or a sentence about secure banking can relate to the connection only. It is not a finding that the business is trustworthy, that withdrawals will be honoured, or that a customer has effective recourse if something goes wrong. Security language has a narrower job than its marketing often suggests.
I learned to treat “certified” and “trusted” as claims that need a clear explanation, not as conclusions. The useful question is what the claim actually verifies and who stands behind it. If the page does not explain that, the label adds little. A technical feature can be real and still leave the central consumer risk untouched.
The same applies to lists promising the best safe casino online. A ranking can compare presentation or features, but a position on a page cannot turn an offshore gambling service into one authorised under Australian law. Nor does calling a service a safe bet settle the question of what protection is available if the operator disputes a payment or closes an account. I would separate the evidence from the sales language, then assess each on its own terms.
A practical review can therefore be modest. Confirm that the claimed protection is described in concrete terms; distinguish encryption from broader promises about safety; and do not treat a site’s own wording as independent verification. The aim is not to assemble a checklist that produces a guaranteed answer. It is to avoid letting one credible technical detail stand in for evidence about everything else.
“Safe slots” can be especially misleading as a phrase: it sounds as though the game itself carries a general assurance. A game’s appearance or the site’s security language says nothing by itself about the legal status of the service offering it. Free-play labels also do not convert a promotional claim into proof of protection. The wording may describe a mode of play, not the operator’s standing or the safeguards available to users.
My own mistake was once to read a visible security signal as a verdict on the whole service. It was not. Encrypted connection: useful. Broad promise: still unproven. A careful assessment keeps those statements apart and refuses to let reassuring design do the work of evidence.
ACMA is Australia’s primary regulator for online gambling. Its role is not to certify a casino as “safe” in the broad sense used in advertising. It enforces the Interactive Gambling Act 2001, including by seeking to block websites and issuing fines to operators that breach the law. Those are regulatory actions, not security checks or endorsements.
The distinction matters because a site can display polished terms, encrypted-payment claims and a convincing presentation without that resolving whether it may offer gambling services to people in Australia. From the operator side, compliance and customer-facing assurances are separate things. A reassuring label does not amount to ACMA approval.
Blocking is one of the tools ACMA uses against prohibited services. The authority can ask internet service providers to block websites offering those services to Australian customers. A block can make a site inaccessible through ordinary connections, though the existence of a block is an enforcement measure, not a verdict on every statement the site has made about itself.
The scale is substantial. Counting illegal gambling sites together with affiliate websites, ACMA had restricted access to 1,369 sites by the time of its published tally. That activity began with the regulator’s first blocking request in November 2019. The figure describes enforcement reach; it should not be read as a list of approved alternatives or as a measure of how secure any remaining site may be.
I have seen how easily a “safe” claim can borrow authority from nearby regulatory language. A page may mention Australian rules, ACMA or blocking and leave the impression that the service itself has been checked. Those references do not establish that. Regulatory enforcement concerns services that fall within the law; a site’s own use of official-sounding words is not an authorisation.
Promotions are another area where the boundary matters. Influencers who promote gambling services must disclose that promotion. A disclosure makes the commercial relationship clearer; it does not make an unlawful offer lawful, or turn a promotion into evidence of safety.
That is the practical limit of using ACMA activity to assess a site. It can show that the regulator is taking action against illegal gambling and affiliate websites, and its blocking powers can interrupt access. It cannot, by itself, tell a reader that an unblocked site is safe, authorised or dependable. No endorsement follows.
When assessing claims, the useful distinction is between a regulator’s action and a company’s sales language. ACMA’s enforcement record is evidence of oversight and intervention, not a shortlist of safe Australian casinos. In this market, those are different questions. A block is not a recommendation; absence from a block count is not approval.
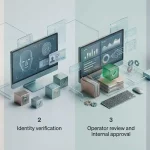
A deposit can appear straightforward because the payment is accepted at the point of entry. A withdrawal is a different stage: before releasing funds, a casino may require identity checks, commonly called KYC. The distinction matters. Payment approval confirms that a transaction was processed; it does not, by itself, complete the checks attached to a later withdrawal.
Verification commonly involves a photo ID, proof of address and evidence that the payment method belongs to the account holder. From the operator’s side, these documents connect the account identity with the person requesting the funds and the route used to deposit. From the customer’s side, the practical consequence is that a withdrawal request can prompt checks that were not visible during the initial payment.
I have seen payment journeys treated as one continuous process, when the operator handles them as separate steps. First, a deposit is accepted. Later, a withdrawal is requested; the account and payment details may then be reviewed before funds are released. If information is incomplete or does not match, the request may not move straight to processing. That is where friction appears—not necessarily at the moment the money leaves the account, but when the service asks for evidence tied to the account or payment method.
Withdrawal Process
Request
The player submits a withdrawal request from their account.
Verification
The operator performs KYC checks, requiring photo ID, proof of address, and payment method evidence.
Processing
Once identity and payment details are matched and approved, the funds are released through the available route.
The route also affects expectations. A card payment does not guarantee that a later withdrawal can travel back through the same channel. A specialist review describes card withdrawals as potentially slower or unavailable, depending on the processor. That is a qualified observation, not a rule that applies to every service or transaction. The processor’s role matters, and a payment option displayed for deposits should not be read as a promise about withdrawals.
This is why “pay safe” can be an incomplete description of a casino payment. It may refer to the transaction’s handling, while saying nothing about whether an account will pass verification or how a withdrawal will be handled. A secure payment screen and a completed identity review answer different questions. Neither should be treated as a guarantee of an uncomplicated payout.
For anyone assessing whether it is safe to play at an online casino, the payment sequence deserves the same scrutiny as the deposit interface. The withdrawal terms should explain what evidence may be requested and how payment methods are handled. If the stated deposit route and withdrawal route differ, that difference is material. If identity documents are requested, the handling of those documents also matters; the request should be understood before sensitive material is sent.
The useful distinction is simple: deposit acceptance is not withdrawal clearance. KYC sits between them. Different checks, different routes.
Australian law bars operators from providing online casino games to people in Australia. That includes slots and table games such as blackjack. A game’s presentation, software or return information does not change that status. “Safe” is doing two different jobs in this context: it can describe how a game behaves, or imply that the service offering it is lawful. Those are not the same thing.
RTP is a game-information figure, not a safety rating. It does not show whether an operator is permitted to offer the game in Australia, nor does it settle whether a particular version is being used. I keep those questions separate. A clear help screen can explain a game’s stated mechanics; it cannot make an unlawful offer lawful.
The RTP information for a pokie can be found in its information or help screen, often opened through an “i” symbol or a menu. The location varies by game interface, but the point is to inspect the game’s own information rather than infer a figure from its title or artwork. A prominent number is still only a description of the version in question.
The version matters. Some providers release the same game with different RTP settings, and the operator selects which version to run. So a figure attached to a game name elsewhere may not describe the version shown in a particular service. The title can match while the underlying setting does not. Small distinction. Material difference.
This is why RTP cannot answer broad questions about whether online casinos are safe. It says something about game configuration, not the legal position of the service or the status of its offer to Australians. Nor does a high-sounding return claim turn an online casino into a safe option. “Generous” is promotional language; the useful detail is whether the stated figure belongs to the version actually presented—and even then, it addresses only the game.
To find the RTP of a pokie, look for the information or help screen, which is typically accessed via an "i" symbol or a specific menu within the game interface.
Free-play labels can also blur the issue. A practice mode may let someone view a game without staking money, but that label alone does not establish the status of any real-money service connected to it. The game’s information and the legality of the offer are separate checks.
I read RTP narrowly: as a game setting to verify in the game’s own help or information panel, not as a verdict on the service. It is a number with a limited job. Nothing more.
A phone changes the route into a gambling service, not its legal status. A mobile-friendly page, saved login or app-like shortcut can make an account easier to reach, but none of those features makes an online casino lawful to offer in Australia. Online casino games remain prohibited for operators serving people physically in the country. “Mobile” describes the screen. Nothing more.
I separate that point from responsible-gambling controls. The Interactive Gambling Act requires licensed operators to meet strict responsible-gambling obligations, but that does not mean an offshore casino is licensed in Australia or that its safeguards carry Australian legal backing. A control displayed in an account is not proof of local authorisation.
A specialist review reports that some licensed online casinos let users set deposit limits by day, week or month. That describes the services covered by that review, not an established feature across the Australian market. Where a limit tool exists, its practical value depends on what it controls and whether it can be changed immediately. The label “responsible” can sound reassuring; the detail is in the settings.
Useful support information is different from a promotional message. Reputable gambling platforms provide information about gambling-related harm and direct people to professional support services in Australia. Gambling Help Online, the National Debt Helpline and BetStop are support services with distinct purposes; a casino’s link to help does not turn the casino into a regulated Australian service. Keep the two questions separate.
The same distinction applies to login security on a phone. A familiar-looking login page or smooth sign-in process says little about whether the service is permitted to take Australian customers. And a VPN is not a safety fix. Using one to access a casino may void winnings, close the account and cost the deposit. The location signal may be treated as a breach of the operator’s terms, leaving the account holder facing the consequences.
That is the trap: a VPN can make access appear possible while increasing the chance of a dispute over the account. It does not create Australian authorisation, and it does not create a route to recover funds if the operator refuses payment. No workaround.
When assessing a mobile gambling experience, I look past the ease of tapping in and ask what the service can actually offer: clear harm-support information, meaningful controls and terms that explain account restrictions. Those features may matter, but they do not change the legal position. A safe mobile experience cannot be inferred from a responsive design, a quick login or a reassuring badge.
When people ask whether an online casino is safe, two different questions often get folded into one: can the site protect information sent through it, and what happens if there is a dispute? Those are not the same test.
Casinos use SSL encryption to safeguard transactions and sensitive information. That addresses the handling of data between a user’s device and a site. It does not establish that the service is authorised to offer gambling in Australia, that its terms will be applied fairly, or that a player has an effective route to recover withheld winnings. “Secure” is a technical claim, not a promise of recourse.
I have seen how reassuring labels can do more work than the underlying feature. Encryption may be present, while the protections people associate with a regulated local service are absent. A polished payment page does not change that distinction. Nor does a security symbol answer who has authority over the operator or what remedy is available when a withdrawal becomes disputed.
For Australians, the practical answer to “is an online casino safe?” cannot rest on the encrypted connection alone. Unlicensed gambling services lack consumer protections, and Australian laws may not assist if winnings are withheld. That is the point where technical security stops being a meaningful substitute for legal protection. A transaction can be encrypted and still leave the customer exposed to the consequences of dealing with an unlicensed service.
ACMA is Australia’s primary online gambling regulator, but the existence of a regulator does not turn an offshore service into a locally protected one. So a list labelled “safe casinos in Australia” would be misleading if it treated encryption as proof of lawful status or reliable remedies. There is no shortcut in the word “safe”.
The distinction is plain, if not comforting: encryption can help protect information; it cannot guarantee fair treatment or ensure that a dispute will be resolved in the customer’s favour. Technical security matters. It is not the whole answer.
An account displayed in Australian dollars can look simpler than one that converts currency, but the currency label says little about how money leaves the account. A wallet or bank-linked option shown at deposit does not automatically appear as a withdrawal route. The cashier can present a neat one-way door.
POLi is mainly described as a deposit method in specialist reviews. That description should not be stretched into a promise that a balance can be returned through POLi. The payment option may be visible when funds go in and absent when funds come out. The distinction matters: a deposit button confirms only that the service accepts that route for deposits, not that it supports the reverse transaction.
Wallet searches create a similar assumption. “Wallet” can mean a payment service, an account balance held by the gambling operator, or simply a label in a payment menu. Those are not interchangeable. The name of a method, and the fact that it handles Australian dollars, do not establish that it can receive a withdrawal.
Cards are not a dependable fallback by definition. Specialist reviews note that card withdrawals can be delayed or unavailable, depending on the processor. That is a processing constraint, not a timing estimate that applies across services. A card accepted for a deposit may not be accepted for a payout; the payment route can be asymmetric.
I have seen payment menus do much of their selling before a customer has read the withdrawal terms. The useful comparison is therefore not the number of logos on the deposit screen, but whether the stated payout route matches the original method and currency. Where the terms are unclear, the uncertainty itself is material.
A “safe” wallet label can sound reassuring. In practice, it describes a payment feature, not a finding about the service behind it. An Australian-dollar balance likewise removes no uncertainty about whether a withdrawal route exists or whether a processor will handle it. The method matters at both ends.
A small distinction. A costly one.
PayID transfers and some e-wallets can be quick once approved and released, while bank transfers and card payments may take several business days. Identity checks or other approval steps can add time before the transfer is released.
The Interactive Gambling Act 2001 does not explicitly make an individual player’s use of an offshore casino a criminal offence. However, that does not make the operator’s offer of online casino games to Australians lawful.
The methods mentioned include PayID, e-wallets, bank transfers and cards; POLi is mainly for deposits, and card withdrawals may be slower or unavailable. Availability and processing time can vary by method.
Licensed operators provide deposit limits that can be set daily, weekly or monthly. Reputable platforms also share information about gambling-related harm and direct players to professional support services in Australia.