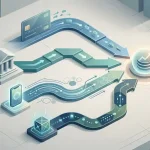
A payout estimate covers different stages, from balance eligibility and internal review to the transfer reaching its destination.
“Fast payout” sounds like a single clock running from the moment a withdrawal is requested until money appears in an account. In practice, the phrase can cover several separate stages. I read it as a description of a process, not a promise about when funds will be usable.
The first stage is whether the balance is eligible to be withdrawn. A displayed balance and a withdrawable balance are not always the same thing: account conditions can still apply, and a request may not move forward until they are satisfied. The key distinction is between money shown on screen and money the operator has accepted for payment. A speed claim that does not explain what must happen before acceptance leaves out an important part of the timing.
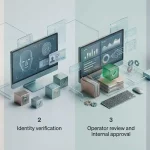
Once a withdrawal request is submitted, the operator may need to review it and approve it internally. That is processing time: the period before the operator releases the payment. It is separate from the transfer time, which begins after approval and concerns how long the payment takes to reach its destination. When an advertised estimate refers only to the operator’s processing, it does not by itself describe the full wait.
This is why the wording around a payout matters. “Processed quickly” and “received quickly” are not interchangeable. The first can describe an internal decision; the second suggests the whole route has been considered. The distinction can be easy to miss in promotional copy, where a short processing estimate may be presented as if it were the complete withdrawal timeline. Read the verb, not just the headline.
A payment can also be pending for reasons unrelated to the transfer network. If an account has not completed the operator’s checks, the withdrawal may pause before approval. A specialist review describes first-withdrawal verification as potentially involving identity documents and proof of address, with a selfie holding identification requested in some cases. That does not mean every operator follows the same procedure, but it shows why account readiness belongs in any realistic assessment of payout claims. Identity and address documents should be verified before a first withdrawal is needed, rather than left until funds are waiting.
From the inside, the first cash-out is often the point at which a process that looked simple becomes procedural. The deposit may have appeared immediately, but that does not establish that the withdrawal will follow the same route or speed. A deposit and a withdrawal are different transactions, with different checks and stages. The operational question is not merely whether a site displays a payment method; it is what happens between submitting a withdrawal and the payment being released.
After approval, the transfer itself still has to arrive. The stated estimate for a transfer after the finance team approves a cash-out is typically one to three business days. That estimate belongs to the post-approval stage, not to the time spent waiting for the request to be reviewed. It also describes a typical interval, not a guaranteed arrival time for every transaction. Weekends and the handling of a particular payment can affect how a timeline is understood, so a claim should be checked for the point at which its clock starts and stops.
I would separate any payout statement into three questions: what makes the balance eligible, how long internal review and approval can take, and how long the transfer takes after release. If the terms give only one figure, it may be describing just one of those stages. A clean-looking number can conceal a longer process when its starting point is left undefined.
The same discipline applies to comparisons. A “fast” label cannot establish that all withdrawals are handled alike, or that every account will clear without a pause. The useful detail is the process attached to the claim: whether approval is included, whether checks may still be outstanding, and whether the arrival estimate begins only after release. If those points are unclear, the label offers little basis for predicting the total wait.
Minimum deposit figures do not answer that question either. A specialist review may report deposit thresholds, but the size of an initial deposit says nothing about how quickly a later withdrawal is reviewed or transferred. Nor does a fast-looking deposit flow prove that the cash-out process is equally direct. Two different clocks.
A practical reading of “fast payout online casino” claims therefore starts before the payment method is considered. First, establish whether the balance can be withdrawn. Then account for any checks and internal approval. Finally, distinguish the operator’s release of funds from the transfer’s arrival. Only the last stage is captured by a post-approval transfer estimate; the full experience includes every stage before it.
The point is not that a short payout claim is necessarily false. It may describe one part accurately. But without a clear start point and a clear end point, “fast” is incomplete information. Approval is not arrival.
A fast cash-out and a pokie’s return setting describe different parts of the experience. The first concerns how a withdrawal is handled; the second concerns the game’s stated return behaviour over time. A claim about one cannot establish anything about the other. “Fast payout” is a description of a payment process, not evidence that a game offers a higher return or that a player is more likely to win.
RTP, or return to player, is a theoretical measure of how much a game is designed to return across a very large number of plays. It is not a forecast for an individual session. A single result can be far above or below that theoretical figure, and a run of losses does not mean a winning result is due. Nor does a past win indicate that the next spin is more likely to pay. The distinction is easy to lose in promotional language, where a return figure can sit beside a payout-speed claim as though the two reinforce each other.
They do not. A casino could process withdrawals quickly while offering a game with a lower RTP setting than the same game elsewhere. Conversely, a higher stated return does not tell anything about how quickly a withdrawal request will be handled. Different mechanisms, different questions.
There is another detail that can sit behind an RTP figure: some providers give casinos a choice of settings for a particular pokie. A specialist review has reported that the same game can therefore be configured with different return percentages at different casinos. That does not mean every game has selectable settings, or that a particular casino has chosen a particular one. The useful point is narrower: a familiar game name, by itself, may not identify the setting in use.
I would not treat a game title as a complete specification. The relevant information is the return setting for the version actually offered, where that setting is disclosed. If the information is absent or unclear, the title alone cannot fill the gap. “Same game” may mean the same basic game design, not necessarily the same theoretical return configuration.
The outcome of each pokie spin is determined independently by a Random Number Generator. Independence matters. The previous spin does not set up the next one, and a sequence that looks patterned does not create a reliable prediction. A result may feel overdue after repeated misses, but that feeling is not evidence that the machine is compensating. The generator selects each outcome separately.
This is also why RTP should not be mistaken for a personal repayment promise. It is a theoretical property of the game, not a schedule that returns a particular amount to a particular player. It does not say when a win will occur, how large it will be, or whether a short session will come close to the long-run expectation. The variation between individual outcomes is precisely why a theoretical figure cannot be read as a session result.
The same caution applies when a site describes its pokies as suitable for fast payouts. That wording can make it sound as though a game itself determines cash-out speed. It does not. A spin produces a game outcome; a withdrawal depends on the separate payment process. Even a pokie with a clearly stated RTP cannot establish how the casino will handle a later payment, while a fast-payout claim cannot establish the game’s RTP setting.
I separate those claims before assessing them. For a game, the question is what return setting applies and what the figure actually represents. For a withdrawal, the question is how the payment is processed. Putting both details on one page does not make either claim proof of the other.
That distinction also prevents a misleading leap from a stated RTP to trustworthiness. A return percentage is not, on its own, proof of fairness, and it says nothing about the quality of the payment process. Likewise, describing a site as trusted because it advertises fast payouts does not verify the settings used by its games. One label cannot do the work of another.
The practical reading is plain: treat the game’s return information as a feature of the game, and payout timing as a separate operational claim. A higher theoretical return does not mean a faster withdrawal. A fast withdrawal does not make a pokie more generous. Neither changes the randomness of the next spin.
A withdrawal request is not the same thing as money released. Once it is submitted, the operator may still need to confirm who owns the account and whether the payment request meets its rules. That is where a headline about speed can meet a less visible condition: the account has to pass checks before the cash-out can proceed.
Specialist reviews report that many casinos require identity verification before a first withdrawal. The requested material can include a photo of government-issued identification and proof of address; some operators also ask for a selfie showing the account holder with their ID. These documents are intended to connect the person making the request with the account and its details. Until the checks are complete, a fast processing claim does not mean the withdrawal is ready to be paid.
The practical distinction is between having documents on file and having them accepted. A submission may need review, and an operator can ask for another document if the original is unclear or does not meet its stated requirements. This creates a pause after the withdrawal request, even if the payment method itself is not the source of delay. In my experience, the phrase “fast payout” tends to describe a stage of the process, not every condition that must be satisfied before funds are accessible.
The useful check is therefore not just whether a site advertises a short processing time. Its terms should explain what identity and address evidence is required, when it must be provided, and what happens if the documents are rejected or need replacing. Completing verification before making a first withdrawal can reduce the chance that the request becomes the moment the operator first asks for basic account evidence. No shortcut. Just preparation.
Caps can create a separate constraint. A specialist review reports that some casinos set weekly or monthly withdrawal limits in the $5,000–$10,000 range. Under a limit of that kind, a $50,000 jackpot could be paid in portions over a multi-year period rather than as one transfer. The amount shown as a balance and the amount that can leave the account at once are not necessarily the same thing.
A cap is not the same as a delay in processing. A request may be handled promptly but still be restricted to the maximum allowed for the relevant period. If the terms state a weekly or monthly ceiling, the schedule for receiving a large balance depends on that ceiling and on how the operator applies it. The headline payout speed cannot answer that question.
The wording matters. A limit may apply per request, across a set period, or to a particular account category; the terms need to make clear which. If the relevant rule is hard to find, or the site describes the cap only in broad promotional language, the actual withdrawal arrangement is difficult to assess. “Quick” can be technically accurate about processing while saying little about how much can be released or when the remainder becomes eligible.
I have seen payout discussions focus on the time between approval and transfer, because that is the easiest figure to put in a headline. Verification and caps sit earlier or alongside that measure, but they shape the practical result just as much. A casino with fast payouts still has to clear the withdrawal, and its own conditions decide what “cleared” means: identity accepted, request permitted, and any applicable limit observed.
For a meaningful comparison, the terms should be read as a sequence of conditions, not as one speed promise. Check the verification requirements and the withdrawal cap before treating a displayed balance as immediately available. The distinction is plain. Processing is only one part.
A fast payout claim describes what an operator says it will do, not what happens if it refuses to release winnings. That distinction matters when real-money play takes place with an offshore casino. If the operator withholds a balance, an Australian player has no legal recourse in Australia to compel payment.
I have seen how the word “reputable” can do more work in a headline than it can in a dispute. It suggests stability and fair dealing, but it does not itself create an enforceable right to a withdrawal. Nor does a smooth-looking site, a history of positive comments or a promise of quick transfers close the gap between an operator’s claim and the player’s ability to make it stick.
This is a different risk from a delay. A delayed transfer may eventually arrive; a refusal means the operator is not paying, and the local remedy described above is unavailable. The practical consequence is that a displayed balance cannot be treated as money already in hand. The player’s position depends on the operator choosing to honour the withdrawal, not simply on the wording of its payout promise.
The phrase “real-money fast payout casino” can make speed sound like the defining measure of safety. It is not. A rapid payment, if it occurs, says something about that transaction; it does not establish what protection exists if a later request is rejected. The same applies to an online casino advertising fast withdrawals or an e-wallet cash-out. The payment route cannot resolve the underlying problem of an offshore operator withholding funds.
That is why I separate operational performance from recourse. One concerns how an operator handles a payment when it agrees to pay. The other concerns what happens when it does not. They are often bundled together in promotional language, but they answer different questions. A site may make a confident claim about payout speed while leaving the central question—what can an Australian customer do if winnings are refused—unanswered.
A “reputable” label is also not a substitute for protection. Reviews and public feedback can describe other people’s experiences, but they do not guarantee the same outcome for a particular withdrawal. A record of payments cannot ensure that a future payment will be honoured, and a fast payout report does not establish a local route for recovering funds after a refusal. Reassuring signals. Not a remedy.
The wording of an offer or withdrawal page can therefore be less important than the operating arrangement behind it. A promise may be precise about timing yet say little about the consequences of non-payment. The risk is not that every offshore operator will withhold winnings; the risk is that, if one does, the player cannot rely on legal recourse in Australia to secure them. That is a material difference between a service claim and a dependable form of consumer protection.
In practical terms, the advertised speed should not be read as a guarantee that funds will arrive, or as evidence that a player can recover them if the operator refuses. The label “fast payout” describes an intended or reported process. It cannot remove the exposure created by dealing with an offshore service that does not pay. No wording can make those two things equivalent.
A bonus can appear in an account before it is available to cash out. The condition that controls this is the wagering requirement: a multiplier applied to the bonus, or sometimes to the combined deposit and bonus. Until the required turnover is recorded, bonus-related funds can remain locked, regardless of how quickly a casino says it processes withdrawals.
The wording matters. “Bonus” can sound like extra cash, but it may be a conditional balance with a separate withdrawal gate. I have seen the distinction disappear in headline offers: the amount is prominent, while the calculation sits in the terms. That is where the real cost becomes visible.
A specialist review uses a $500 bonus with a 40x requirement to illustrate the arithmetic: $500 multiplied by 40 means $20,000 in bets before winnings can be withdrawn. If the multiplier applies to the deposit plus bonus instead, a $500 deposit and $500 bonus at 35x produce $35,000 in required bets. The same multiplier can therefore mean substantially different turnover depending on its calculation base.
These figures explain the mechanism, not a promise that a particular offer will follow it. A specialist review suggests treating requirements of 35x or less as the more manageable end of its assessment, while describing anything above 40x as punishing. That is an editorial judgement, not a rule that makes a bonus favourable. The terms still determine which funds count, which games contribute and when the requirement is considered complete.
A no-deposit offer does not escape the same scrutiny. With no initial deposit, the headline may seem especially attractive, but any wagering condition can still keep resulting winnings from being withdrawable until the specified turnover is met. The label “no deposit” describes how the offer starts; it does not by itself establish that winnings can be cashed out without conditions.
Free spins have a related catch. A specialist review notes that an offer can limit the winnings eligible for cash-out. In that case, meeting a wagering requirement may not make the full displayed balance withdrawable: a separate cap can restrict what is released. The cap and the turnover rule do different jobs, so checking only one leaves part of the offer’s mechanics hidden.
Bonus Calculation
Identify Multiplier Base
Determine if the wagering requirement applies to the bonus alone or to the combined deposit and bonus.
Calculate Required Turnover
Multiply the bonus amount (e.g., $500) by the requirement (e.g., 40x) to find the total bets needed ($20,000).
Check for Caps
Verify if a separate cap restricts the maximum amount of winnings that can be released after requirements are met.
Payment wording does not change this calculation. Whether an offer is discussed alongside Bitcoin or another payment method, a fast transfer claim concerns movement of funds after they are eligible for withdrawal. It does not make bonus funds eligible sooner, remove a turnover condition or raise a cap. “Fast payout” is not the same as “immediately withdrawable.”
I would read the offer in this order: identify whether the multiplier applies to the bonus alone or to deposit plus bonus; check the exact turnover figure; then look for a separate cash-out cap on free-spin winnings. Also note which play contributes to turnover, because a stated multiplier is meaningful only alongside its counting rules. A large headline number can be less useful than a smaller offer with clearer, lighter conditions.
This is the point where promotional value and accessible money part company. The bonus may increase the balance shown on screen, while the terms determine how much of that balance can eventually leave the account. Conditions first. Headline second.
Fast payouts can make a real difference when choosing an online casino, but the available payment details vary. Use this list to check which operators have specific payout or deposit information and which are included without further details.
Neospin
Neospin is listed with a Curaçao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Ricky Casino
Ricky Casino lists crypto payouts in under an hour and PayID payouts in 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
Roby Casino
Roby Casino is listed with a Curaçao eGaming licence held by Roby Games Ltd.
Uptown Pokies
Uptown Pokies is listed as operating since 2017 under a Curaçao licence. Its minimum deposit is A$20.
7Bit Casino
7Bit Casino is listed as operating under a Curaçao licence, with Dama N.V. as its operator.
SpinsUp
SpinsUp is listed with a Curaçao Gaming Control Board licence, OGL/2023/174/0082, held by Dama N.V.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi and holds a Curaçao licence.
LuckyVibe
LuckyVibe is listed with a Curaçao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
Golden Pokies
Golden Pokies is listed with a Curaçao licence.
Bizzo Casino
Bizzo Casino is listed with a Curaçao Gaming Control Board licence held by TechSolutions Group N.V.
“Top” sounds like a judgement about speed, but it can conceal a separate constraint: how much can leave the account over a set period. A withdrawal claim may describe how quickly a request is processed, while the cap determines how much of a balance can actually be paid out at once. Those are different measures.
I treat a payout figure as incomplete until the applicable withdrawal limit is read alongside it. A specialist review has reported casinos with weekly or monthly caps of $5,000–$10,000. Under that kind of restriction, a $50,000 jackpot could become a multi-year payout plan. The headline amount exists on the account; access to it is spread across the operator’s permitted payment schedule.
That distinction changes what “fast” means in practice. A quick first transfer does not establish that the full balance can be withdrawn quickly. If a cap applies, the time needed to receive the entire amount depends on the cap’s period and the amount eligible for each payment. A page that highlights processing speed but leaves the cap in small print is describing only one part of the transaction.
The wording matters. A weekly ceiling and a monthly ceiling do not operate in the same way, even if the stated amount looks similar. A cap may also apply to total withdrawals rather than a single request. The terms need to be read for the scope of the limit, not just its figure. Small print. Big effect.
A “top” payout claim is therefore not a dependable comparison by itself. It may refer to processing, transfer timing, maximum withdrawal, or some combination of those. Without separating those meanings, the label can make a restricted payout arrangement appear more generous than it is.
The useful measure is not simply whether a cash-out is described as fast. It is whether the stated speed applies to the amount involved, and whether a weekly or monthly ceiling stretches the payout into instalments. A large balance and a low cap can coexist. The cap decides the pace of access.
That is why a payout claim should be read as a set of conditions, not as a promise about the whole balance. The limit may be the detail that determines whether “fast” has any practical meaning beyond the first payment.
“Fast” attached to a crypto withdrawal is a claim about a process, not proof of how quickly money will be accessible. A digital transfer has more than one step: the operator must release it, and the receiving service must handle it. A headline that collapses those stages into one promise leaves the important detail unclear.
I have seen payout language do this in other payment contexts: it presents the transfer as if it starts the moment a withdrawal is requested. That skips the operator’s own handling and the point at which a payment is actually sent. For crypto, the label alone cannot establish either stage or a reliable completion time. Nor does it establish which digital assets or services a particular site supports. Those details have to be stated and substantiated separately.
There is a wider payment complication in Australia. A specialist gambling review reports that Australian banks and card companies are increasingly blocking transactions to known gambling sites. That is a report about payment restrictions, not evidence that a crypto transfer avoids them, or that a crypto cash-out will be approved or completed on a particular schedule. Payment routes and controls can change; a method’s name is not a guarantee of access.
“Crypto payout” can sound like a single, direct movement of funds. In practice, that phrase may conceal who initiates the transfer, what service receives it and what conditions apply before funds are available. Without those details, a speed claim cannot be compared meaningfully with another one. Fast at which stage? Released by the operator, or usable after the transfer reaches its destination? The wording should answer that distinction rather than blur it.
I would treat a crypto speed promise as unsubstantiated unless it clearly defines what is being timed and what event marks completion. A payment label is not a timetable. And a timetable, even when stated, does not establish that a withdrawal will be accepted or paid.
PayID is not a separate wallet. It is an alias service within Australia’s New Payments Platform (NPP): a transfer can be addressed using an email address, mobile number or Australian Business Number instead of bank-account details. The NPP is available through all major banks and protects transfers with end-to-end encryption. Those are features of the payment infrastructure, not a guarantee about the business receiving a payment.
For real-money casino payments, PayID has to be linked to a bank account first. That link matters: the transfer still depends on the account and the bank’s handling of the transaction. A specialist review has reported that some banks, including major Australian banks, may block PayID payments to gambling merchants they recognise. A payment option displayed on a site can therefore be different from an option that works for every account. No certainty there.
I have seen “fast” used as if a payment label settled the question of speed. It does not. A method used to send money to an operator does not, by itself, establish how quickly a withdrawal is processed or received. Deposit support and payout support are separate claims; the terms for each need to be read separately.
The same distinction applies to PayPal. Its name or logo on a payment page cannot establish the timing or conditions of a withdrawal. Without clear, applicable withdrawal terms, the label alone is not evidence of a fast payout. It also says nothing about the operator’s legal status, whether games are fair, or whether return-to-player information is transparent.
That is the limit of what a payment badge can prove. PayID’s integration with the NPP describes the transfer rail, not the conduct of a casino using it. PayPal support, where claimed, is likewise a payment claim rather than a quality check. A quick-looking deposit route can coexist with unanswered questions about withdrawals and the operator behind them. The distinction is easy to miss in a banner. It matters.
A new operator can describe its cash-outs as fast, but a launch announcement does not show how the process works once a real withdrawal is requested. There may be little operating history to assess, and a polished payment page cannot establish how consistently requests are handled. I treat “new” as a reason to look for evidence, not as a quality in itself.
One specialist gambling review reports that casinos commonly ask for identity checks before a first withdrawal. The documents may include a photograph of an identity document and proof of address; a selfie holding the document may also be requested. That account describes reported practice, not a rule that every operator follows. The practical point is that verification can be part of the route to a first cash-out, so an advertised speed alone does not explain when funds become available.
For a newly launched site, the terms should make clear what documents are needed, where they are submitted and what happens if a document is rejected or needs replacing. Those details matter before funds are tied up in an account. Vague wording leaves the operator with room to decide later what counts as sufficient proof. That is not a minor omission.
I have seen how a short claim such as “fast payouts” can compress several separate steps into one reassuring phrase. It says little about whether the first account check has been completed or whether the requested evidence will be accepted. A new site has not had much time to demonstrate that its written process matches its handling of actual requests. The claim is not proof.
Identity and address documents should be verified before the first withdrawal is attempted, rather than treated as an afterthought at that point. If the requirements are unclear, the uncertainty belongs to the process itself—not to the speed label attached to it. Verify first.
A “fast payout” claim does not change the legal status of the service behind it. Under the Interactive Gambling Act 2001, companies cannot provide real-money online pokies to people in Australia without a domestic licence. No Australian online-casino licences have been issued, so there is no locally licensed online casino market to distinguish one operator from another.
The law is directed at operators, not individual players. That distinction matters: it does not make an offshore service lawful just because a person can access it or the site accepts Australian customers. ACMA, the Australian Communications and Media Authority, enforces the Act and can block access to illegal offshore gambling sites. Internet service providers must comply with its blocklist. A blocked site may therefore be inaccessible, regardless of what its payment or payout claims say.
BetStop has a narrower role. It applies to Australian-licensed operators and does not bind offshore gambling sites. It should not be treated as a barrier that prevents an offshore service from accepting an account or as a safeguard that governs that service. The boundary is important. Different rules apply to domestic licensed gambling, and there are no domestic online-casino licences.
The legal age for gambling in Australia, including online pokies, is 18. That age rule does not create a lawful online-casino option: age eligibility and the legality of an operator are separate questions.
I have seen promotional language blur those distinctions. “Australian-facing” describes an audience, not a licence. “Fast payout” describes a claim about handling withdrawals, not regulatory approval. Neither phrase resolves whether a company is permitted to provide the service in Australia. The legal position is the starting point, not a badge attached to a payment promise.
There is no Australian-licensed online casino, and Australian players have no legal recourse in Australia if an offshore casino refuses to pay winnings. Check that the operator explains its identity-verification and withdrawal process, but this does not remove that legal risk.
Yes. Some game providers let casinos choose from multiple RTP settings for the same pokie, so its return percentage can differ between casinos. Each spin is still an independent random event.
You must be at least 18 years old to gamble online in Australia.
It is the amount you must bet, usually expressed as a multiple of a bonus, before you can withdraw winnings tied to it. For example, a $500 bonus with a 40x requirement calls for $20,000 in bets.